



FTSE 100 outlook: Investors brace for a busy week
Last week saw the FTSE shake off its short-term bearish spell, and looked set to have another go at that August record just above 9,360, only for a last minute turnaround late in the day on Friday to spoil the bullish party.
Share this:
Last week saw the FTSE shake off its short-term bearish spell, and looked set to have another go at that August record just above 9,360, only for a last minute turnaround late in the day on Friday to spoil the bullish party. The index closed lower but still eked out a gain for the week, its second in as many weeks. The index remains a spitting distance away from its record, so the FTSE 100 outlook remains bullish heading into a busy week of economic data, central bank decisions and company earnings.
Bullish technical FTSE 100 outlook remains intact
Before discussing the macro factors impacting the FTSE 100 outlook, let’s first take a look at the chart:
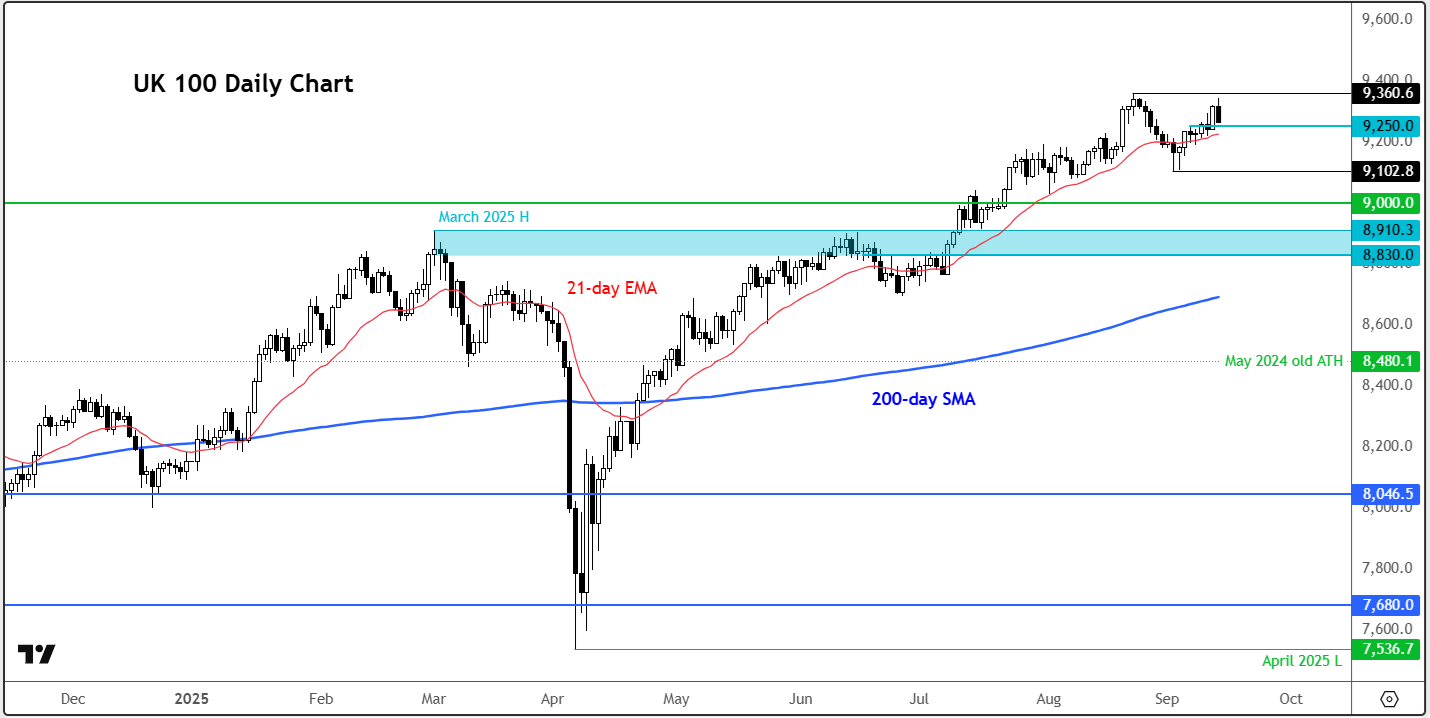
In recent days, the UK 100 has bounced cleanly off the 21-day exponential moving average, keeping its short-term bullish bias intact. Short-term support is seen around 9,250, followed by 9,190. If we see the index stay above these key levels in the week ahead, then we will probably break higher, but lose the lower support of 9,150 and a slide back towards the 9,000 handle comes into view. Personally, I’d lean bullish while we hold above that support.
Key interim resistance sits at 9,305 — previously support on intraday charts. A sustained break above this level could spark renewed buying momentum towards the all-time high near 9,360.
Here’s a refined rephrasing of your text for improved flow, clarity, and conciseness, while keeping the professional market commentary tone intact:

FOMC: Rate Cut Priced In, Focus on Forward Guidance
The coming week is packed with central bank meetings, with the Fed’s decision on Wednesday, September 17, being the highlight. Signs of slowing consumer demand and a weakening labour market justify further easing, even as CPI remains elevated at 2.9% and tariffs threaten to keep it sticky. The Fed is widely expected to deliver a 25bp cut, making the move itself unlikely to jolt the US dollar. Instead, market reaction will hinge on the Fed’s tone—its forward guidance in the statement, updated dot plots, and Powell’s press conference will shape expectations for additional policy easing later this year.
FTSE 100 Outlook: BoE Decision in Focus
The Bank of England announces policy on Thursday, September 18, following last month’s deeply divided vote to cut rates by 25bp. This time, a hold is expected. Recent stronger data—including robust retail sales, upbeat PMIs, and accelerating CPI at 3.8%—combined with the later autumn budget, have pushed expectations for the next cut from November to December. A hawkish-leaning MPC would likely cap the FTSE’s gains, while the vote split will be key in gauging divisions. If only two or fewer members back a cut, sterling could rally. As for forward guidance, no major shift in tone is anticipated just a month after the previous meeting, unless wage or CPI data earlier in the week deliver major surprises.
UK Economy Stagnates in July
Ahead of the BoE rate decision, we saw evidence of UK economy stagnating. Economic data released Friday morning painted a mixed-to-weak picture, as output flatlined in July, as expected, but the surprise came from a 1.3% drop in manufacturing production, where a modest rise had been anticipated. Gains in construction output and a slightly stronger services sector were not enough to lift the pound, nor did the news provide a reason for equities to rally. Despite the soft data, the Bank of England is unlikely to cut rates again until December. This delay should offer support for sterling, potentially limiting the FTSE’s upside in the near term.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.