



US open: Futures hold steady ahead of the Fed minutes
US futures are holding steady on Wednesday after a mixed closed in the previous session, which saw tech stocks take a hammering.
Share this:
US futures
Dow futures -0.04% at 31934
S&P futures +0.06% at 3945
Nasdaq futures +0.08% at 11780
In Europe
FTSE +0.51% at 7526
Dax +0.15% at 13950
Euro Stoxx +0.26% at 3657
Learn more about trading indices
Key data & FOMC minutes due
US futures are holding steady on Wednesday after a mixed closed in the previous session, which saw tech stocks take a hammering.
The Nasdaq closed 2.3% lower, the S&P -0.8% and the Dow Jones managed a positive finish up 0.15%.
The mood in the market remains cautious as the deteriorating macroeconomic picture, reflected in weaker data, is starting to show up in corporate America, unnerving the markets.
US durable goods orders could shed more light on the health of the US economy. Expectations are orders to rise 0.5% in April after a 1.1% gain in May.
Looking ahead attention is on the release of the minutes from the May FOMC meeting when the Federal Reserve raised interest rates by 50 basis points and announced their plan for reducing the balance sheet, starting at $47.5 billion and ramping up to $95 billion by June.
More recently, and in light of the softer economic data, expectations of an overly aggressive Fed have eased.
The market expects two 50 basis point rate hikes from the Federal Reserve in June and July. However, should the minutes show that the Fed is reluctant to plan much beyond there, risk sentiment could take another hit.
In corporate news:
Nvidia is due to report after the close. Wall Street is expecting EPS of $1.30 on revenue of $8.13 billion. Attention will be on whether data centre sales overshadow gaming sales which could see growth slow as the economy reopened.
Where next for the S&P500?
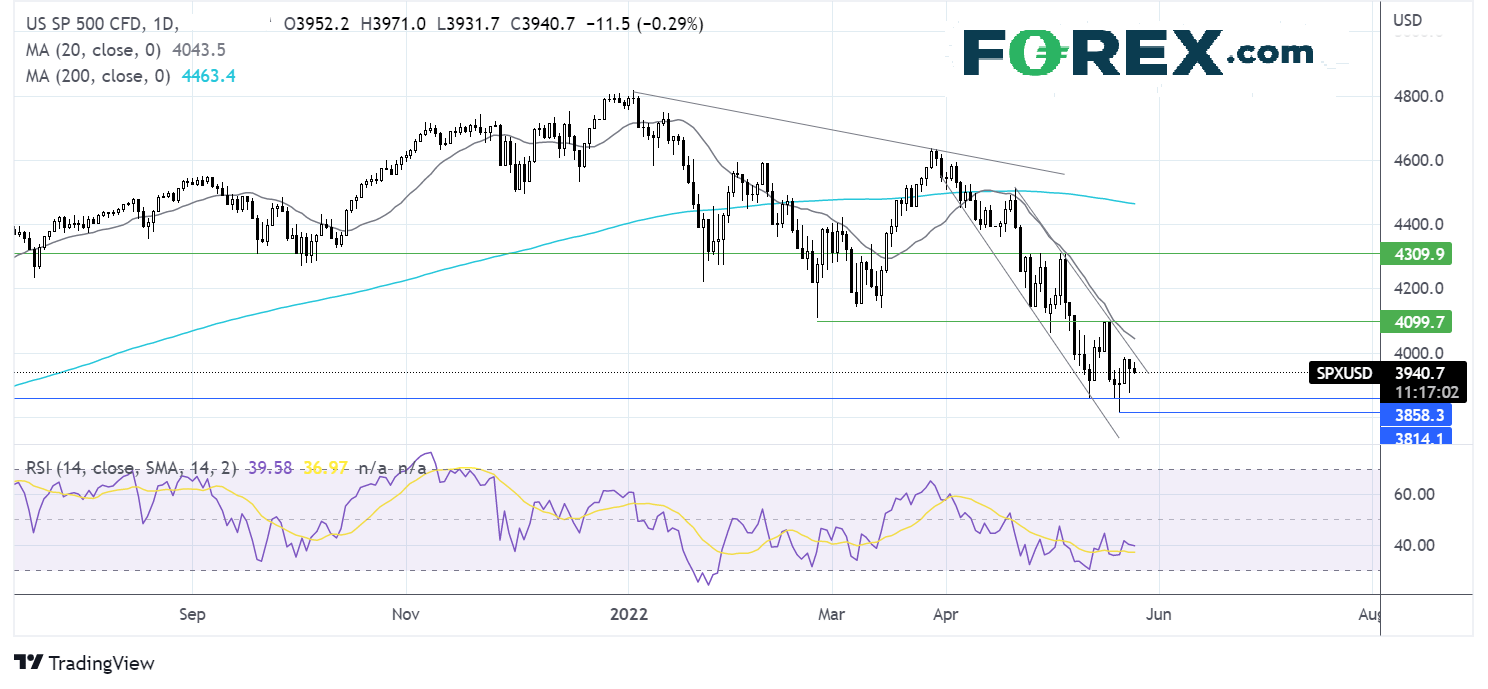
The S&P500 continues to trade within a falling channel dating back to early December. Whilst the price has picked up off 3810 but has run into resistance around 3980 the weekly high. The RSI is at 39, below the 50 level so indicates that there could be more downside to come. Sellers need to break below 3860 the May 12 low in order to test 3810 the 2022 low and continue the bearish trend. Buyers look for a move over 3980 the weekly high to expose the 20 sma at 4043. It would take a move over 4100 the mid May high, to create a higher high.
FX markets – USD rises, EUR falls
USD is rising from a monthly low, trading treasury yields higher ahead of key US data and the minutes to the May FOMC meeting. The US dollar has come under pressure recently as the economic downturn, evident in weaker US data forced markets to rein in aggressive Fed bets.
NZD/USD has failed to hold onto gains after the RBNZ hikes interest rates by 50 basis points, taking the rate to 2%. The move was widely expected and is the second outsized rise in as many meetings. The central bank also signaled to more 50 basis point rate hikes to come.
EUR/USD is falling after a strong start to the week. The EUR trades lower despite an upward revision to German Q1 GDP data to 3.8% YoY, up from 3.7%. However, QoQ the growth rate was confirmed 0.2%. German consumer confidence steadied at -26 in June, just mildly off the record low of -26.6 reached in May.
NZD/USD -0.06% at 0.6468
EUR/USD -0.6% at 1.0675
Oil edges higher
Oil prices continue to trade in a tight range as investors weigh up the prospect of stronger demand as the US driving season ramps up, against the prospect of tighter supply as buyers avoid Russian oil.
The EU still hasn’t approved its phased-in ban of Russian oil imports but optimism remains among ministers and within the oil markets that this will be achieved soon. Given the lengthy delay since the proposal and Hungary still not getting behind the deal, it is by no means fully priced in. With that in mind, any signs of the deal being agreed on will likely lift oil prices.
Meanwhile, in the US Memorial Day travel is expected to be the busiest in two years which will cause a rise in fuel demand, despite high prices. The ramping up of the driving season is already being noted in API data which showed that gasoline inventories fell by 4.2 million barrels last week.
EIA crude oil stock pile data is due later today.
WTI crude trades +0.8% at $110.17
Brent trades +0.79% at $111.00
Learn more about trading oil here.
Looking ahead
13:30 US durable goods orders
15:30 EIA crude oil inventories
19:00 FOMC minutes
21:30 API oil inventories
US futures
Dow futures -0.04% at 31934
S&P futures +0.06% at 3945
Nasdaq futures +0.08% at 11780
In Europe
FTSE +0.51% at 7526
Dax +0.15% at 13950
Euro Stoxx +0.26% at 3657
Learn more about trading indices
Key data & FOMC minutes due
US futures are holding steady on Wednesday after a mixed closed in the previous session, which saw tech stocks take a hammering.
The Nasdaq closed 2.3% lower, the S&P -0.8% and the Dow Jones managed a positive finish up 0.15%.
The mood in the market remains cautious as the deteriorating macroeconomic picture, reflected in weaker data, is starting to show up in corporate America, unnerving the markets.
US durable goods orders could shed more light on the health of the US economy. Expectations are orders to rise 0.5% in April after a 1.1% gain in May.
Looking ahead attention is on the release of the minutes from the May FOMC meeting when the Federal Reserve raised interest rates by 50 basis points and announced their plan for reducing the balance sheet, starting at $47.5 billion and ramping up to $95 billion by June.
More recently, and in light of the softer economic data, expectations of an overly aggressive Fed have eased.
The market expects two 50 basis point rate hikes from the Federal Reserve in June and July. However, should the minutes show that the Fed is reluctant to plan much beyond there, risk sentiment could take another hit.
In corporate news:
Nvidia is due to report after the close. Wall Street is expecting EPS of $1.30 on revenue of $8.13 billion. Attention will be on whether data centre sales overshadow gaming sales which could see growth slow as the economy reopened.
Where next for the S&P500?
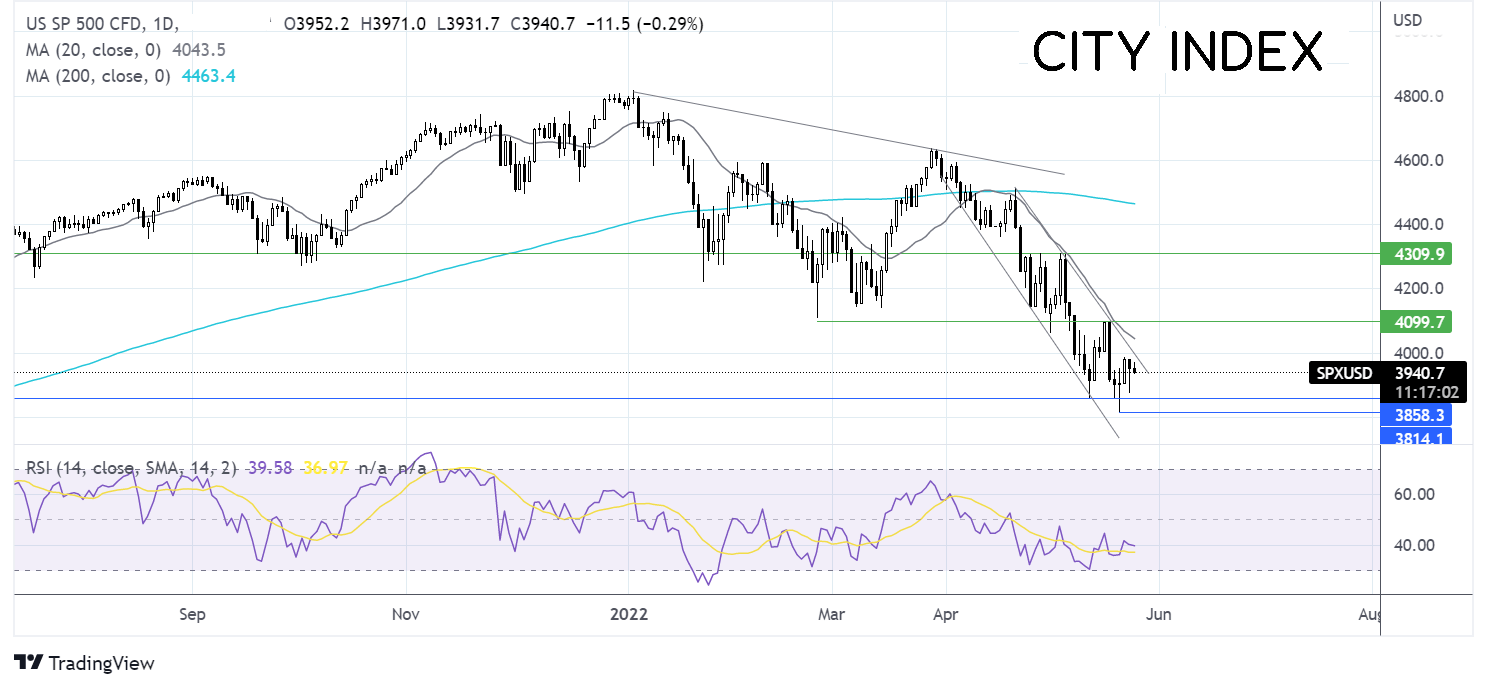
The S&P500 continues to trade within a falling channel dating back to early December. Whilst the price has picked up off 3810 but has run into resistance around 3980 the weekly high. The RSI is at 39, below the 50 level so indicates that there could be more downside to come. Sellers need to break below 3860 the May 12 low in order to test 3810 the 2022 low and continue the bearish trend. Buyers look for a move over 3980 the weekly high to expose the 20 sma at 4043. It would take a move over 4100 the mid May high, to create a higher high.
FX markets – USD rises, EUR falls
USD is rising from a monthly low, trading treasury yields higher ahead of key US data and the minutes to the May FOMC meeting. The US dollar has come under pressure recently as the economic downturn, evident in weaker US data forced markets to rein in aggressive Fed bets.
NZD/USD has failed to hold onto gains after the RBNZ hikes interest rates by 50 basis points, taking the rate to 2%. The move was widely expected and is the second outsized rise in as many meetings. The central bank also signaled to more 50 basis point rate hikes to come.
EUR/USD is falling after a strong start to the week. The EUR trades lower despite an upward revision to German Q1 GDP data to 3.8% YoY, up from 3.7%. However, QoQ the growth rate was confirmed 0.2%. German consumer confidence steadied at -26 in June, just mildly off the record low of -26.6 reached in May.
NZD/USD -0.06% at 0.6468
EUR/USD -0.6% at 1.0675
Oil edges higher
Oil prices continue to trade in a tight range as investors weigh up the prospect of stronger demand as the US driving season ramps up, against the prospect of tighter supply as buyers avoid Russian oil.
The EU still hasn’t approved its phased-in ban of Russian oil imports but optimism remains among ministers and within the oil markets that this will be achieved soon. Given the lengthy delay since the proposal and Hungary still not getting behind the deal, it is by no means fully priced in. With that in mind, any signs of the deal being agreed on will likely lift oil prices.
Meanwhile, in the US Memorial Day travel is expected to be the busiest in two years which will cause a rise in fuel demand, despite high prices. The ramping up of the driving season is already being noted in API data which showed that gasoline inventories fell by 4.2 million barrels last week.
EIA crude oil stock pile data is due later today.
WTI crude trades +0.8% at $110.17
Brent trades +0.79% at $111.00
Learn more about trading oil here.
Looking ahead
13:30 US durable goods orders
15:30 EIA crude oil inventories
19:00 FOMC minutes
21:30 API oil inventories
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.