





ISM Services PMI A Few Worrying Signs
ISM Services hit a 3-year low but, until we see further weakness from the sub-sectors, the potential for a rebound remains.
Share this:

There was more anticipation than usual for this month’s ISM Non-Manufacturing PMI. Why? As it’s much older brother, the ISM manufacturing PMI essentially rolled over and went into the fetal position.
Fears of a global slowdown were already weighing on sentiment ahead of ISM manufacturing sinking to a 10-year low, until the dire number finally saw equity markets roll over from their highs. As we outlined previously, the service sector has remained in growth since the last recession in 2009 whilst manufacturing had sent 2 false recession signals over the same period. Therefore, we’d prefer to see service PMI fall alongside manufacturing to better assess the likelihood of a US recession. And it appears the service sector is now closing the gap to the downside, although the numbers aren’t all that bad.
There are a few worrying signs within the service sector, although it remains expansive none the less.
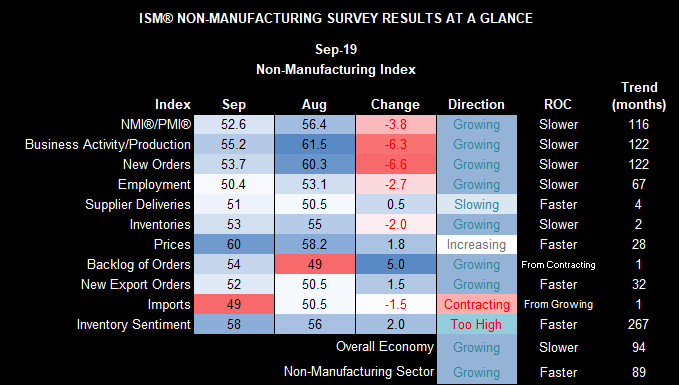
- The service sector is expanding at its slowest rate in 3 years, at 52.6
- Falling 8.2 from its peak, it’s the largest decline from its peak during the entire expansion. We’d have to 2007 to see a fall from its high of a greater magnitude.
- September was a -2 standard deviation change. Whist technically the industry remains in growth territory, it has had quite a knock to the head.
- Employment barely grew at 50.4 and is its slowest rate since 2013
- Imports contracted for the first time since February
- New orders and business activity/production fell -6.6 and -6.3 points respectively in September. However, they remain elevated at 53.7 and 55.2 and the monthly changes are quite volatile
But it’s not all bad. And, unlike the manufacturing sector, there are some good numbers within the sub sectors:
- Prices are their highest in 10 months at 60 (inflationary)
- Only imports declined, and new orders and business production remain expansive.
- Backlog of orders sits just above its 1-year average at 54
Key takeaway: It may not have been a great month for services by historical standards, but with new orders, business production and backlog of orders remaining expansive, it leaves potential for a bounce. Particularly if US and China sign that famous trade deal. Sure, if we see this move into contraction then the probability of a US recession goes up, but we’d prefer to see if there are signs of weakness in new orders, production and backlog of orders next month before calling Armageddon for the financial markets.
Still, traders have increased the probability of a Fed rate cut this month to 86% from 77% the day before. We think it’s unlikely they’ll pull the trigger on a 50- bps cut simply because they’re easing from the lowest peak in history, and they’d prefer to leave such a move for if or when the markets are truly in turmoil.
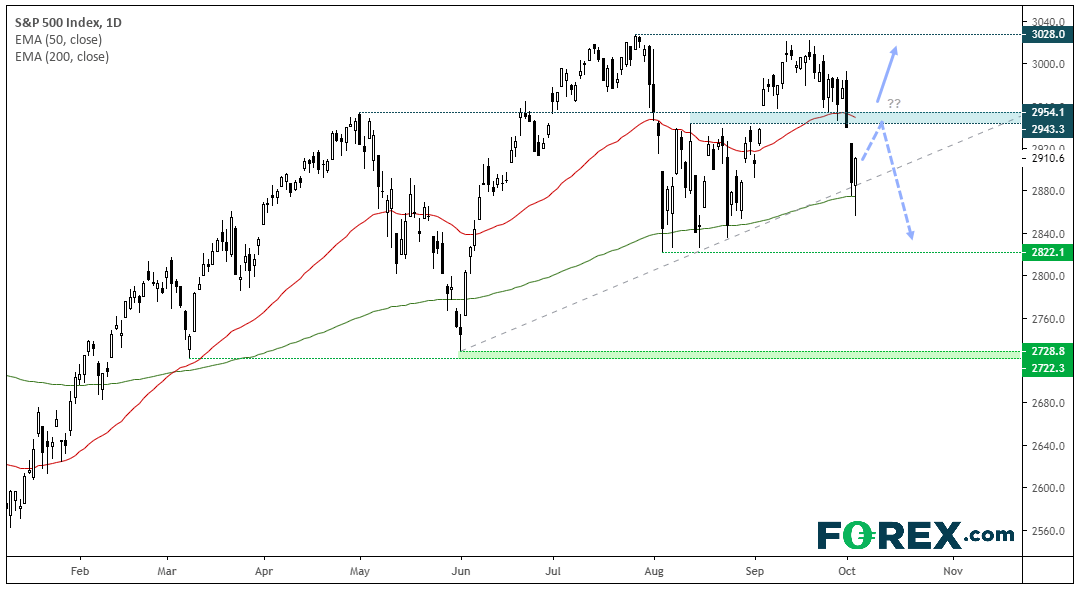
The S&P500 recovered as it headed into the end of the session and trades back above 2,900. An initial sell-off threatened a break of its June trendline, until the 200-day eMA saved the day. A 2-day reversal pattern in form of a bullish piercing line suggests the initial breakdown could have been a bear-trap but we also have the 50-day MA as a likely resistance level. Furthermore, yesterday’s bullish candle needs to be taken in context of the initial decline, so bulls may not yet be out of the woods just yet.
- Unless we see prices rebound sharply, bears could consider fading into low volatility moves below the 2,950 (prior support) or wait for a lower high to form beneath the key level.
- However, if we see a sharp rebound then bulls could assume the low is in and target the all-time highs once more.
- Higher expectations of a rate cut are supportive of stocks, so a weak Nonfarm payroll report could throw bulls another lifeline. Conversely, a strong employment report could cap gains.
Related analysis:
NFP Preview: Another Weak Report Could Cement a Fed Rate Cut This Month
NFP could be the Last Horse in the Trifecta
Manufacturing PMI Gets Even Uglier, But Is It The End Of The World? | DJT, FDX
There was more anticipation than usual for this month’s ISM Non-Manufacturing PMI. Why? As it’s much older brother, the ISM manufacturing PMI essentially rolled over and went into the fetal position.
Fears of a global slowdown were already weighing on sentiment ahead of ISM manufacturing sinking to a 10-year low, until the dire number finally saw equity markets roll over from their highs. As we outlined previously, the service sector has remained in growth since the last recession in 2009 whilst manufacturing had sent 2 false recession signals over the same period. Therefore, we’d prefer to see service PMI fall alongside manufacturing to better assess the likelihood of a US recession. And it appears the service sector is now closing the gap to the downside, although the numbers aren’t all that bad.
There are a few worrying signs within the service sector, although it remains expansive none the less.
- The service sector is expanding at its slowest rate in 3 years, at 52.6
- Falling 8.2 from its peak, it’s the largest decline from its peak during the entire expansion. We’d have to 2007 to see a fall from its high of a greater magnitude.
- September was a -2 standard deviation change. Whist technically the industry remains in growth territory, it has had quite a knock to the head.
- Employment barely grew at 50.4 and is its slowest rate since 2013
- Imports contracted for the first time since February
- New orders and business activity/production fell -6.6 and -6.3 points respectively in September. However, they remain elevated at 53.7 and 55.2 and the monthly changes are quite volatile
But it’s not all bad. And, unlike the manufacturing sector, there are some good numbers within the sub sectors:
- Prices are their highest in 10 months at 60 (inflationary)
- Only imports declined, and new orders and business production remain expansive.
- Backlog of orders sits just above its 1-year average at 54
Key takeaway: It may not have been a great month for services by historical standards, but with new orders, business production and backlog of orders remaining expansive, it leaves potential for a bounce. Particularly if US and China sign that famous trade deal. Sure, if we see this move into contraction then the probability of a US recession goes up, but we’d prefer to see if there are signs of weakness in new orders, production and backlog of orders next month before calling Armageddon for the financial markets.
Still, traders have increased the probability of a Fed rate cut this month to 86% from 77% the day before. We think it’s unlikely they’ll pull the trigger on a 50- bps cut simply because they’re easing from the lowest peak in history, and they’d prefer to leave such a move for if or when the markets are truly in turmoil.
The S&P500 recovered as it headed into the end of the session and trades back above 2,900. An initial sell-off threatened a break of its June trendline, until the 200-day eMA saved the day. A 2-day reversal pattern in form of a bullish piercing line suggests the initial breakdown could have been a bear-trap but we also have the 50-day MA as a likely resistance level. Furthermore, yesterday’s bullish candle needs to be taken in context of the initial decline, so bulls may not yet be out of the woods just yet.
- Unless we see prices rebound sharply, bears could consider fading into low volatility moves below the 2,950 (prior support) or wait for a lower high to form beneath the key level.
- However, if we see a sharp rebound then bulls could assume the low is in and target the all-time highs once more.
- Higher expectations of a rate cut are supportive of stocks, so a weak Nonfarm payroll report could throw bulls another lifeline. Conversely, a strong employment report could cap gains.
Related analysis:
NFP Preview: Another Weak Report Could Cement a Fed Rate Cut This Month
NFP could be the Last Horse in the Trifecta
Manufacturing PMI Gets Even Uglier, But Is It The End Of The World? | DJT, FDX
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nasdaq 100 forecast: Nvidia troubles put AI recovery into question
The recovery for major indices this week has helped repair much of the technical damage inflicted by last week’s sell-off, but the latest developments with Nvidia suggest investors are not quite ready to put the underlying risks behind them. The Nasdaq 100 led other US index futures lower overnight, with falls of around 0.8%.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.