



Lyft Q4 Results Preview
The pressure is on Lyft to speed up to profitability
Share this:

When:
Tuesday 11th February after US market close
Tuesday 11th February after US market close
Expectations:
- Losses $1.38 cents per share
- Revenue: +47% $984 billion vs 63% increase in Q3
Look back at Q3
Lyft’s Q3 revenue soared 63% to $955.6 million. Active riders climbed 28% yet it still posted a net loss of $463.5 million, significantly worse that the $249.2 million from the same period a year earlier. Yet despite eye watering losses Lyft remained confident, announcing it expected to be profitable (EBITDA) basis by Q4 2021.
Lyft’s Q3 revenue soared 63% to $955.6 million. Active riders climbed 28% yet it still posted a net loss of $463.5 million, significantly worse that the $249.2 million from the same period a year earlier. Yet despite eye watering losses Lyft remained confident, announcing it expected to be profitable (EBITDA) basis by Q4 2021.
Profitable?
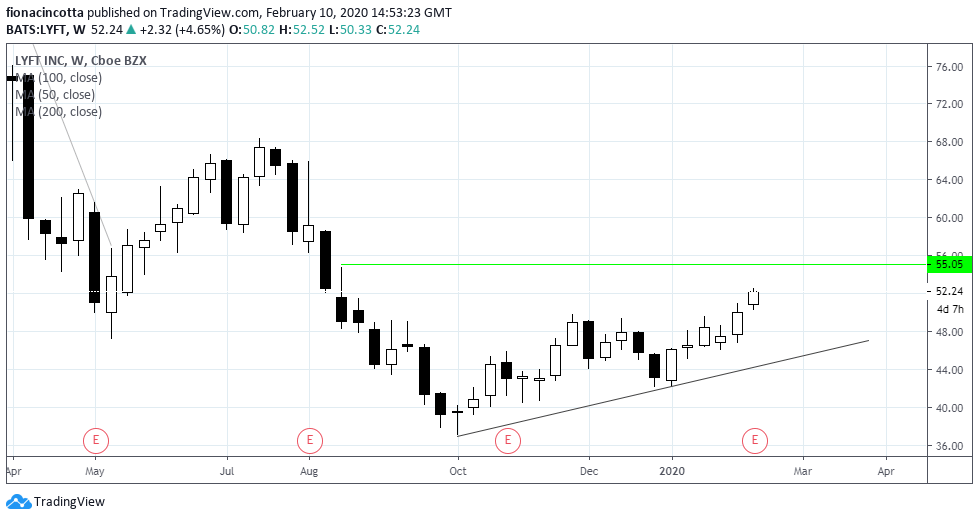
So far Lyft has failed to live up to its IPO hype. As the ride sharing business continues to lose money, traders will be paying particular attention to the firms progress towards profitability goals. Lyft has lost around 1/3 of its value since its IPO last March as management attempt to convince investors that it can keep driving growth whilst gradually shrinking losses. Lyft highlights modest price increases and focus on high value modes as means to arrive at profitability faster. Traders will scrutinize growth in the core ride hailing segment as well as segments that Lyft believes will drive profits.
So far Lyft has failed to live up to its IPO hype. As the ride sharing business continues to lose money, traders will be paying particular attention to the firms progress towards profitability goals. Lyft has lost around 1/3 of its value since its IPO last March as management attempt to convince investors that it can keep driving growth whilst gradually shrinking losses. Lyft highlights modest price increases and focus on high value modes as means to arrive at profitability faster. Traders will scrutinize growth in the core ride hailing segment as well as segments that Lyft believes will drive profits.
Restructuring
Days ago, Lyft announced that it was laying off around 90 worker (2% of its workforce) as it restructures its sales and marketing team, in order to reach its 2020 business goals. Across 2019 Lyft underwent several rounds of job cuts, slimming down the business. Traders will be looking for more details on the restructuring and what it means for profitability.
Days ago, Lyft announced that it was laying off around 90 worker (2% of its workforce) as it restructures its sales and marketing team, in order to reach its 2020 business goals. Across 2019 Lyft underwent several rounds of job cuts, slimming down the business. Traders will be looking for more details on the restructuring and what it means for profitability.
Lyft vs Uber
Comparisons will of course be drawn between Uber and Lyft. Last week Uber said that it expected to report adjusted profit in Q4 2020, ahead of its previous projection following a narrower than expected loss in Q4. The share price soared 10%.
So the pressure is on Lyft to follow Uber’s path to quicker profitability. Failure to do so could hit Lyft’s share price.
Regulation
Lyft, like Uber, must address regulatory issues. California recently enacted a new law which is currently being challenged, which raises questions over the standards at which a worker is considered an employee and is entitled to sick pay and benefits. If this results in a change to the Lyft business model consumers could face 100% of the bill increase. Traders will be keen to hear Lyft elaborate on the potential impact to the business. A cautious tone could send the share price lower.
When:
Tuesday 11th February after US market close
Tuesday 11th February after US market close
Expectations:
- Losses $1.38 cents per share
- Revenue: +47% $984 billion vs 63% increase in Q3
Look back at Q3
Lyft’s Q3 revenue soared 63% to $955.6 million. Active riders climbed 28% yet it still posted a net loss of $463.5 million, significantly worse that the $249.2 million from the same period a year earlier. Yet despite eye watering losses Lyft remained confident, announcing it expected to be profitable (EBITDA) basis by Q4 2021.
Lyft’s Q3 revenue soared 63% to $955.6 million. Active riders climbed 28% yet it still posted a net loss of $463.5 million, significantly worse that the $249.2 million from the same period a year earlier. Yet despite eye watering losses Lyft remained confident, announcing it expected to be profitable (EBITDA) basis by Q4 2021.
Profitable?
So far Lyft has failed to live up to its IPO hype. As the ride sharing business continues to lose money, traders will be paying particular attention to the firms progress towards profitability goals. Lyft has lost around 1/3 of its value since its IPO last March as management attempt to convince investors that it can keep driving growth whilst gradually shrinking losses. Lyft highlights modest price increases and focus on high value modes as means to arrive at profitability faster. Traders will scrutinize growth in the core ride hailing segment as well as segments that Lyft believes will drive profits.
So far Lyft has failed to live up to its IPO hype. As the ride sharing business continues to lose money, traders will be paying particular attention to the firms progress towards profitability goals. Lyft has lost around 1/3 of its value since its IPO last March as management attempt to convince investors that it can keep driving growth whilst gradually shrinking losses. Lyft highlights modest price increases and focus on high value modes as means to arrive at profitability faster. Traders will scrutinize growth in the core ride hailing segment as well as segments that Lyft believes will drive profits.
Restructuring
Days ago, Lyft announced that it was laying off around 90 worker (2% of its workforce) as it restructures its sales and marketing team, in order to reach its 2020 business goals. Across 2019 Lyft underwent several rounds of job cuts, slimming down the business. Traders will be looking for more details on the restructuring and what it means for profitability.
Days ago, Lyft announced that it was laying off around 90 worker (2% of its workforce) as it restructures its sales and marketing team, in order to reach its 2020 business goals. Across 2019 Lyft underwent several rounds of job cuts, slimming down the business. Traders will be looking for more details on the restructuring and what it means for profitability.
Lyft vs Uber
Comparisons will of course be drawn between Uber and Lyft. Last week Uber said that it expected to report adjusted profit in Q4 2020, ahead of its previous projection following a narrower than expected loss in Q4. The share price soared 10%.
So the pressure is on Lyft to follow Uber’s path to quicker profitability. Failure to do so could hit Lyft’s share price.
Regulation
Lyft, like Uber, must address regulatory issues. California recently enacted a new law which is currently being challenged, which raises questions over the standards at which a worker is considered an employee and is entitled to sick pay and benefits. If this results in a change to the Lyft business model consumers could face 100% of the bill increase. Traders will be keen to hear Lyft elaborate on the potential impact to the business. A cautious tone could send the share price lower.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nasdaq Rips, 8% Off the Lows – Are Bulls Back in Control?
The AI trade is getting a push this morning following the earnings results from Coreweave, and with the Nasdaq already up more than 8% from last week’s lows the big question is whether a low is in place.
S&P 500 Update: SPX Records Its Biggest Selloff of the Year Ahead of NFP
The trading week has not been particularly favorable for risk appetite in the short term, and this is now becoming increasingly evident in the performance of the S&P 500. During today's session, the index is down nearly 4.2%, marking its largest intraday decline of 2026.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.