



Morrisons turns a corner
Morrisons’ appeal goes further than special dividend and expanded Amazon deal
Share this:

Morrisons’ appeal goes further than special dividend and expanded Amazon deal
Wm. Morrisons’ special dividend announcement caps a half-year performance by the number-four UK supermarket that looks relatively solid, considering its less than optimal industry position and underlying sales growth that’s seen it pace only the worst performer among established chains, Sainsbury’s, for several quarters. The stock is faring better than its larger rival as the latter continues to lick its wounds after failing to buy Asda. MRW’s 4% so far this year fall compares with a 19% slump by SBRY. That nevertheless demonstrates widely disparate sentiment versus market leader, Tesco, whose long-standing efficiency and growth drive is now reaping benefits warranting a 2019 advance of 25%.
True, Morrisons’ key second-quarter sales—at stores open for at least a year and excluding fuel—were always going to struggle to match Q2 2018’s 6.3% surge. Then, the entire sector was buoyed by beautiful British weather, a royal wedding and the World Cup. In the end though, a 1.9% fall over the quarter to early August this year wasn’t as bad as widely expected. An in-line interim dividend garnished with a ‘special’ one-off payment helps convey the expectation that Morrisons’ strategy is showing increasing traction.
The strategy includes an expanded partnership with Amazon, that ought to provide further reassurance of some protection from the disruptive e-commerce giant. Morrison’s storefront on the platform will now distribute to more UK cities. In fact though, a move that MRW trumpets less than the Amazon deal, its tie-in with McColl’s, holds even higher medium-term potential. The arrangement to supply 300 additional units of the McColl’s chain adds volume, whilst a trial conversion of some units to Morrisons stores could boost the move towards higher joint participation. As such, there are now deeper inroads towards the upper end of a targeted £75m-£125m cumulative pre-tax profit after MRW booked £54m mostly from lower finance costs.
Major challenges remain, at both industry level (see Brexit) and for £4.8bn Morrisons. Sales growth per square foot continues to inch up, but growth remains more fragile than top rivals. MRW also still lacks a well-defined convenience format, leaving it vulnerable to challenges that go alongside the problematic online history with Ocado. The group is still catching up. Still, Ebitda margin expansion of 20 basis points in H1 and a £15m rise in underlying free cash flow back the view that an upturn has been seen. Against an action-packed industry backdrop, to say the least, a major takeaway for investors is that Morrisons remains on track to hit milestones that can open the door to further higher than expected cash returns.
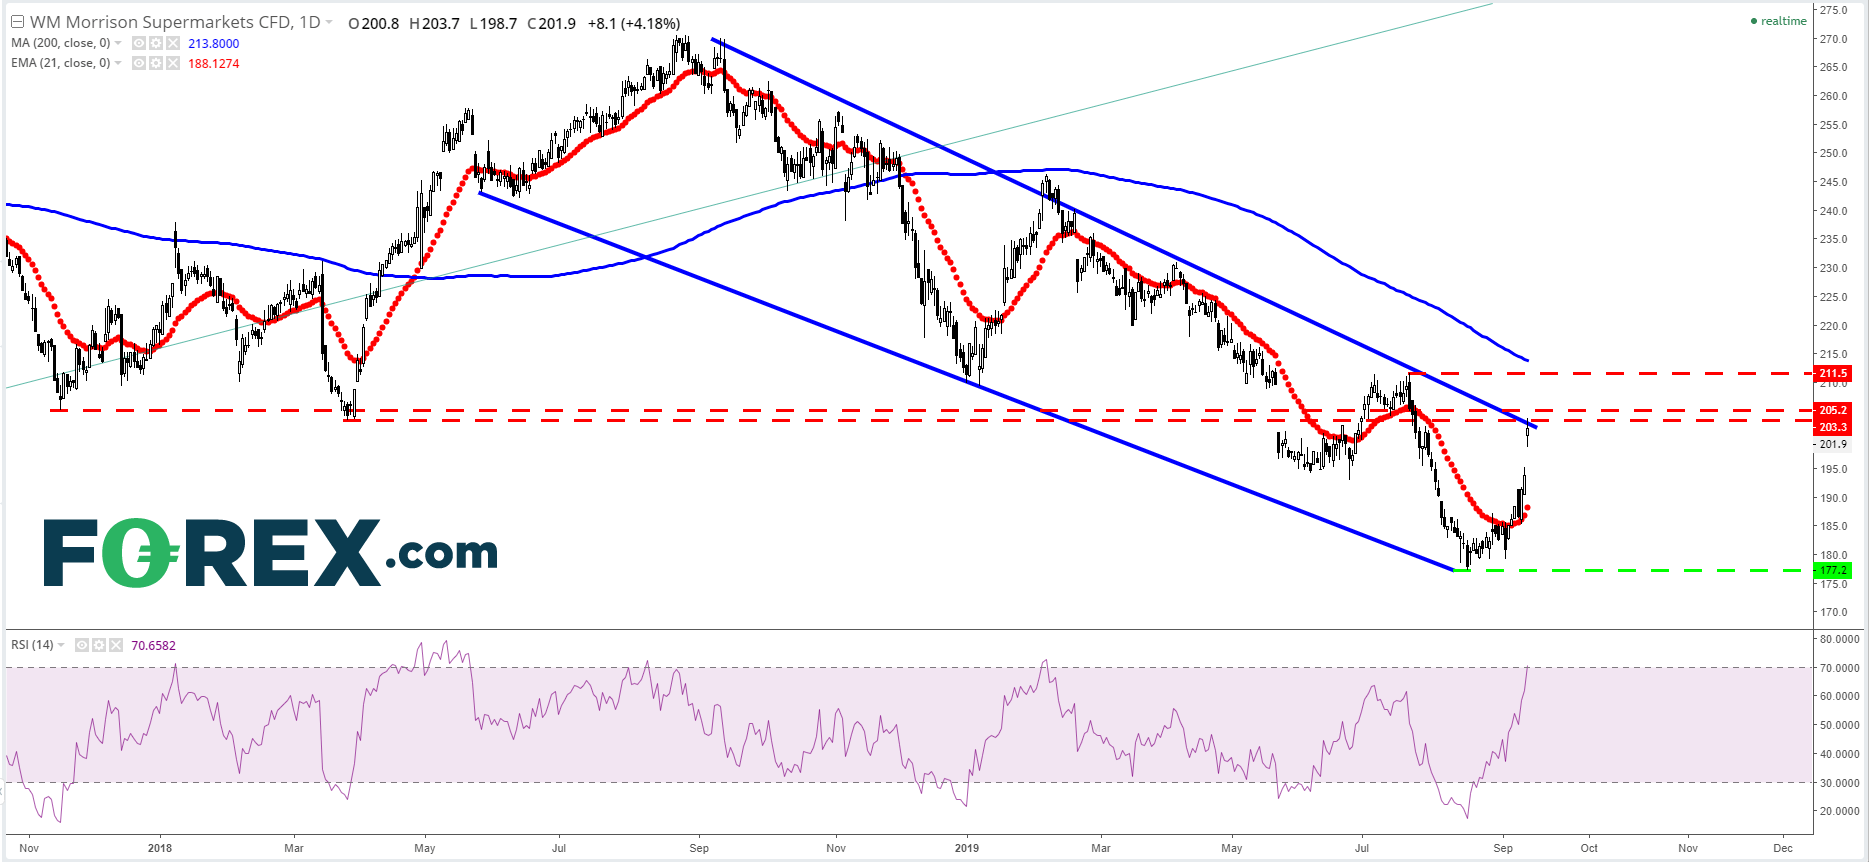
Chart thoughts
- An almost 3-year uptrend was broken last November, posing an overarching selling bias since then
- Some corroboration of that is shown by MRW’s falling channel in place for almost exactly a year; note Thursday’s rally hit the upper wall of the pattern
- The stock has also rallied to resistance from strongly defended November 2017 and March/April 2018 lows of around 205p and 203p respectively
- Failure here would imply another look at the 177p kick back low from August for support
- The 200-day moving average trends downwards encapsulating long-term weakness, but the 21-day exponential average is a ray of light. Its recent supports points to a possible trend change as it curves attractively upwards
- A break above 22nd July’s 211.5p failure high which was just short of the upper wall looks like it would confirm a turning point for buyers
WM Morrisons CFD – Daily
Source: City Index
Morrisons’ appeal goes further than special dividend and expanded Amazon deal
Wm. Morrisons’ special dividend announcement caps a half-year performance by the number-four UK supermarket that looks relatively solid, considering its less than optimal industry position and underlying sales growth that’s seen it pace only the worst performer among established chains, Sainsbury’s, for several quarters. The stock is faring better than its larger rival as the latter continues to lick its wounds after failing to buy Asda. MRW’s 4% so far this year fall compares with a 19% slump by SBRY. That nevertheless demonstrates widely disparate sentiment versus market leader, Tesco, whose long-standing efficiency and growth drive is now reaping benefits warranting a 2019 advance of 25%.
True, Morrisons’ key second-quarter sales—at stores open for at least a year and excluding fuel—were always going to struggle to match Q2 2018’s 6.3% surge. Then, the entire sector was buoyed by beautiful British weather, a royal wedding and the World Cup. In the end though, a 1.9% fall over the quarter to early August this year wasn’t as bad as widely expected. An in-line interim dividend garnished with a ‘special’ one-off payment helps convey the expectation that Morrisons’ strategy is showing increasing traction.
The strategy includes an expanded partnership with Amazon, that ought to provide further reassurance of some protection from the disruptive e-commerce giant. Morrison’s storefront on the platform will now distribute to more UK cities. In fact though, a move that MRW trumpets less than the Amazon deal, its tie-in with McColl’s, holds even higher medium-term potential. The arrangement to supply 300 additional units of the McColl’s chain adds volume, whilst a trial conversion of some units to Morrisons stores could boost the move towards higher joint participation. As such, there are now deeper inroads towards the upper end of a targeted £75m-£125m cumulative pre-tax profit after MRW booked £54m mostly from lower finance costs.
Major challenges remain, at both industry level (see Brexit) and for £4.8bn Morrisons. Sales growth per square foot continues to inch up, but growth remains more fragile than top rivals. MRW also still lacks a well-defined convenience format, leaving it vulnerable to challenges that go alongside the problematic online history with Ocado. The group is still catching up. Still, Ebitda margin expansion of 20 basis points in H1 and a £15m rise in underlying free cash flow back the view that an upturn has been seen. Against an action-packed industry backdrop, to say the least, a major takeaway for investors is that Morrisons remains on track to hit milestones that can open the door to further higher than expected cash returns.
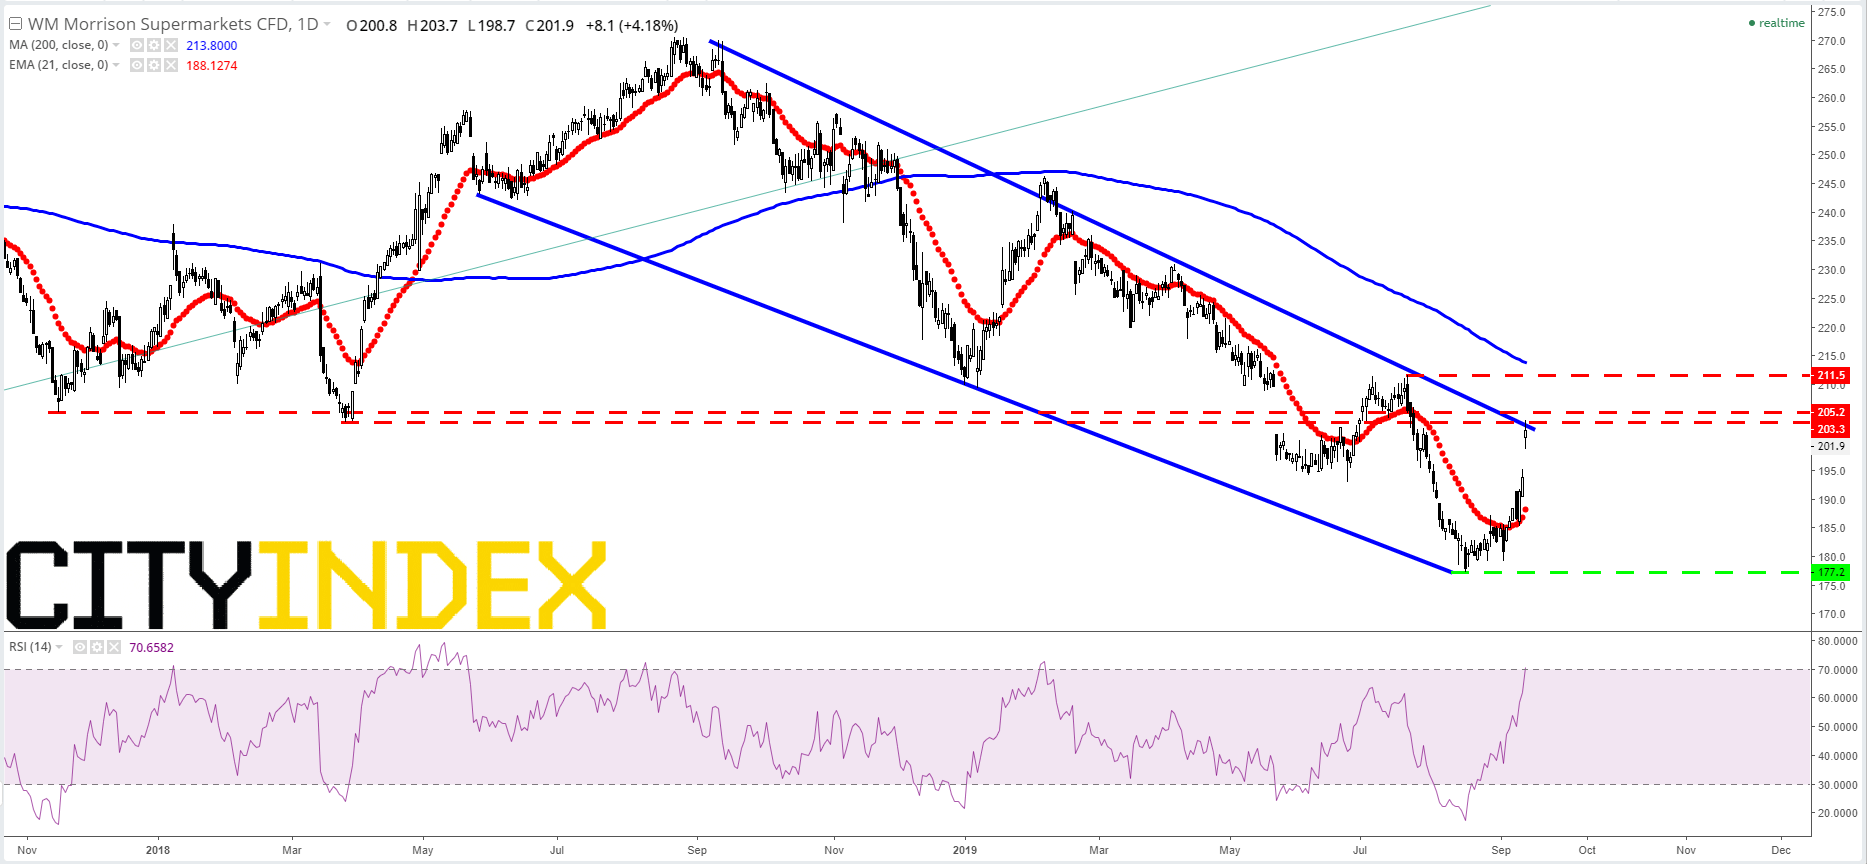
Chart thoughts
- An almost 3-year uptrend was broken last November, posing an overarching selling bias since then
- Some corroboration of that is shown by MRW’s falling channel in place for almost exactly a year; note Thursday’s rally hit the upper wall of the pattern
- The stock has also rallied to resistance from strongly defended November 2017 and March/April 2018 lows of around 205p and 203p respectively
- Failure here would imply another look at the 177p kick back low from August for support
- The 200-day moving average trends downwards encapsulating long-term weakness, but the 21-day exponential average is a ray of light. Its recent supports points to a possible trend change as it curves attractively upwards
- A break above 22nd July’s 211.5p failure high which was just short of the upper wall looks like it would confirm a turning point for buyers
WM Morrisons CFD – Daily
Source: City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.


Nasdaq Rips, 8% Off the Lows – Are Bulls Back in Control?
The AI trade is getting a push this morning following the earnings results from Coreweave, and with the Nasdaq already up more than 8% from last week’s lows the big question is whether a low is in place.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.