




OPEC+ set for existing deal despite China, overcompliance concerns
The OPEC and its allies (OPEC+) are continuing to slowly relax the output cuts they introduced in 2020
Share this:

The OPEC+ meets again on Thursday and once again it is expected to confirm a previously agreed output hike of 430,000 barrels per day in June.
The OPEC and its allies (OPEC+) are continuing to slowly relax the output cuts they introduced in 2020 when demand collapsed as major economies went into lockdowns to curb the spread of Covid. The group is set to increase output targets by 432K bpd every month until the end of September. At that point, the remaining production cuts should be fully unwound.
But demand has recovered strongly from the lows of 2020 and oil prices have gushed higher, before surging again on the back of Russia’s invasion of Ukraine. Against this backdrop, you would think the OPEC+ would be keen to add oil more quickly than they have been doing so. Yet, they have continually refused to do that, while many members have been unable to ramp up their production to levels called for under the supply deal.
This begs the question: What is the point of ratifying another increase in production month after month, if the alliance is not able to reach it? Why are they still going at it?
The short answer is that the OPEC does not want to send the wrong signal. It has already come under a lot of scrutiny by not being able or willing to raise its output more than it has done so far. If it were to set the productions targets even lower, this would give some members more excuse not to hit the production target, and thus keep the market undersupplied. Even if the OPEC+ collectively wanted to raise output even more slowly, it would not look good on their part. Yes, you have a slowing Chinese economy, but this is to be offset by falling Russian oil exports as Western nations attempt to phase out their dependence on Russian energy.
EU unveils plan to ban Russian oil imports
On Wednesday, the EU announced a phased embargo on Russian oil. The plan, which needs to be ratified by all 27 EU member states, will see Russian supply of crude oil phased out within six months and crude products by the end of the year. If it manages to convince its members to ratify the plan and prevent Hungary and Slovakia to buy more oil than they need, then this will have a huge impact on Russian oil exports.
Overcompliance
At some point, the OPEC will need to address over-compliance. According to a Reuters survey, OPEC’s April oil production rose only by 40K bpd from March. As a result, OPEC compliance with pledged cuts was 164%, compared to 151% in March. With the exception of February, the OPEC has consistently undershot the pledged hikes since October.
The problem is that many producers lack the capacity to pump more crude. This is because of insufficient investment, which was exacerbated by the pandemic. Among the OPEC members, Libya and Nigeria have struggled to raise their production the most. In the case of the former, it was losing more than 550,000 bpd from blockades on fields and terminals at one point in April. Libya is among the exempt members from making output cuts. Although Saudi Arabia and to a lesser degree Iraq have moved to offset the production short falls, this has not been near enough to meet the group’s target.
As any investment in the industry will take time to help increase supply, it looks very unlikely that the OPEC will address the overcompliance issues at this meeting. It will also point to the situation in China as a reason to remain cautious. As a result, we expect the OPEC to stick to a deal reached last July and hike output by another 432K bpd.
What does it all mean for oil prices?
In short, we are more likely to see elevated levels of Brent and WTI prices than lower, especially given the difficultly the OPEC has had in raising its oil output of late. In other words, the market is likely to remain tight for a while yet. Oil prices will thus remain supported on the dips, hurting consumer incomes and underpinning inflationary pressures. The only caveat to that view is that if China ramps up its lockdowns due to its zero Covid policy and the recent spread of the virus there. Indeed, the OPEC+ will be keen to highlight this risk as it explains why it is not opting for higher output quotas than planned.
Brent likely to climb around $110-$120 range
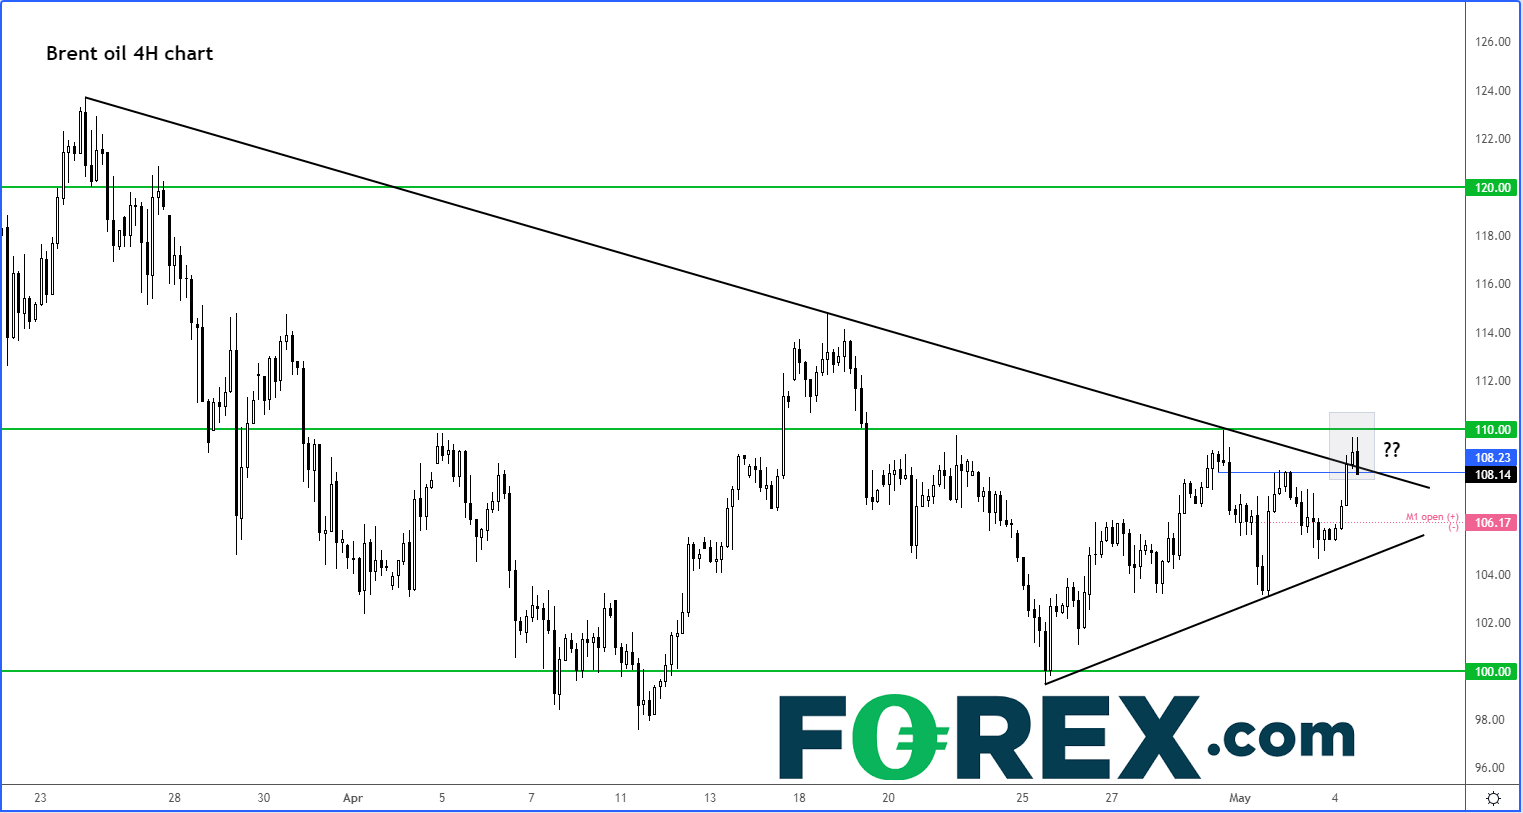
Brent may have formed a base around $100.00 after spending several weeks in consolidation above this psychologically important level. If it manages to hold the breakout above the trend line shown on the 4-hour chart, then prices may find a new range between $110 to $120 per barrel, especially in light of the Russian oil export ban and OPEC’s ongoing policy stance.
Source: StoneX and TradingView.com
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
The OPEC+ meets again on Thursday and once again it is expected to confirm a previously agreed output hike of 430,000 barrels per day in June.
The OPEC and its allies (OPEC+) are continuing to slowly relax the output cuts they introduced in 2020 when demand collapsed as major economies went into lockdowns to curb the spread of Covid. The group is set to increase output targets by 432K bpd every month until the end of September. At that point, the remaining production cuts should be fully unwound.
But demand has recovered strongly from the lows of 2020 and oil prices have gushed higher, before surging again on the back of Russia’s invasion of Ukraine. Against this backdrop, you would think the OPEC+ would be keen to add oil more quickly than they have been doing so. Yet, they have continually refused to do that, while many members have been unable to ramp up their production to levels called for under the supply deal.
This begs the question: What is the point of ratifying another increase in production month after month, if the alliance is not able to reach it? Why are they still going at it?
The short answer is that the OPEC does not want to send the wrong signal. It has already come under a lot of scrutiny by not being able or willing to raise its output more than it has done so far. If it were to set the productions targets even lower, this would give some members more excuse not to hit the production target, and thus keep the market undersupplied. Even if the OPEC+ collectively wanted to raise output even more slowly, it would not look good on their part. Yes, you have a slowing Chinese economy, but this is to be offset by falling Russian oil exports as Western nations attempt to phase out their dependence on Russian energy.
EU unveils plan to ban Russian oil imports
On Wednesday, the EU announced a phased embargo on Russian oil. The plan, which needs to be ratified by all 27 EU member states, will see Russian supply of crude oil phased out within six months and crude products by the end of the year. If it manages to convince its members to ratify the plan and prevent Hungary and Slovakia to buy more oil than they need, then this will have a huge impact on Russian oil exports.
Overcompliance
At some point, the OPEC will need to address over-compliance. According to a Reuters survey, OPEC’s April oil production rose only by 40K bpd from March. As a result, OPEC compliance with pledged cuts was 164%, compared to 151% in March. With the exception of February, the OPEC has consistently undershot the pledged hikes since October.
The problem is that many producers lack the capacity to pump more crude. This is because of insufficient investment, which was exacerbated by the pandemic. Among the OPEC members, Libya and Nigeria have struggled to raise their production the most. In the case of the former, it was losing more than 550,000 bpd from blockades on fields and terminals at one point in April. Libya is among the exempt members from making output cuts. Although Saudi Arabia and to a lesser degree Iraq have moved to offset the production short falls, this has not been near enough to meet the group’s target.
As any investment in the industry will take time to help increase supply, it looks very unlikely that the OPEC will address the overcompliance issues at this meeting. It will also point to the situation in China as a reason to remain cautious. As a result, we expect the OPEC to stick to a deal reached last July and hike output by another 432K bpd.
What does it all mean for oil prices?
In short, we are more likely to see elevated levels of Brent and WTI prices than lower, especially given the difficultly the OPEC has had in raising its oil output of late. In other words, the market is likely to remain tight for a while yet. Oil prices will thus remain supported on the dips, hurting consumer incomes and underpinning inflationary pressures. The only caveat to that view is that if China ramps up its lockdowns due to its zero Covid policy and the recent spread of the virus there. Indeed, the OPEC+ will be keen to highlight this risk as it explains why it is not opting for higher output quotas than planned.
Brent likely to climb around $110-$120 range
Brent may have formed a base around $100.00 after spending several weeks in consolidation above this psychologically important level. If it manages to hold the breakout above the trend line shown on the 4-hour chart, then prices may find a new range between $110 to $120 per barrel, especially in light of the Russian oil export ban and OPEC’s ongoing policy stance.
Source: StoneX and TradingView.com
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

US dollar rally loses yield support as Nvidia looms
US yields are retreating, but the dollar isn't following. With risk aversion potentially keeping it supported, Nvidia's results could determine whether emerging reversal signals in AUD/USD and EUR/USD develop further.

GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.


EUR/USD outlook: euro back above 1.1000 as dollar rally loses steam
EUR/USD has recovered back above 1.1000 after a brief break lower, a sign the dollar's inflation-driven rally may be losing momentum. With a December Fed hike largely priced in and oil a potential tailwind for the euro, the risks are starting to tilt to the upside.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.