



Q4 2021 US Reporting Season Preview
Q4 reporting season picks up speed this evening with reports from financial heavyweights JP Morgan, Wells Fargo, Citigroup, and Blackrock, before 114 companies report next week. See below the key themes and trends we'll be monitoring.
Share this:
Macro Overview
2021 saw the S&P500 hit fresh record highs on an astonishing 70 separate days. It is noticeable that the first two weeks of 2022 have seen a continuation of the volatility that marked the final months of 2021.
US inflation recently reached an almost 40 year high, hitting an annualised 7% in December. To counter this, the Federal Reserve has become increasingly hawkish.
In response, market expectations have shifted towards faster balance sheet normalization, with "quantitative tightening" to begin in September after Fed lift-off in June or possibly as early as March. A prospect that has rattled tech stocks.
Meanwhile, surging Omicron cases have left hospitals straining under the weight of numbers, disrupting global supply chains and grocery shelves empty. A development that will weigh on Q1 growth, likely to be reflected in some company's forward guidance.
Earnings
Despite the headwinds outlined above, S&P500 companies are expected to deliver strong earnings growth again. According to Factset, "For Q4 2021, the estimated earnings growth rate for the S&P 500 is 21.7%."
Presuming this is the confirmed growth rate for the quarter, it will mark the fourth straight quarter of earnings growth above 20% and lift full years earning growth to more than 40% for the full year.
Guidance
As noted by FactSet in the first week of January, "93 S&P 500 companies have issued EPS guidance for the fourth quarter. This number is slightly below the 5-year average of 100. Of these 93 companies, 56 have issued negative EPS guidance, and 37 have issued positive EPS guidance."
This marks the first time since Q2 2020 that S&P500 companies have issued more negative EPS guidance than positive guidance. Despite this, the estimated (year over year) earnings growth for Q4 2021 is above the expectations from the start of Q4.
Sector Performance
As noted by Factset, the Energy sector led by companies such as Exxon Mobil and Chevron have recorded the largest percentage increase in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at 40.8% (to $28.1 billion from $20.0 billion).
The Consumer Discretionary sector led by Amazon.com has recorded the largest percentage decrease in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at -15.1% (to $27.1 billion from $32.0 billion).
S&P500 Technical Outlook
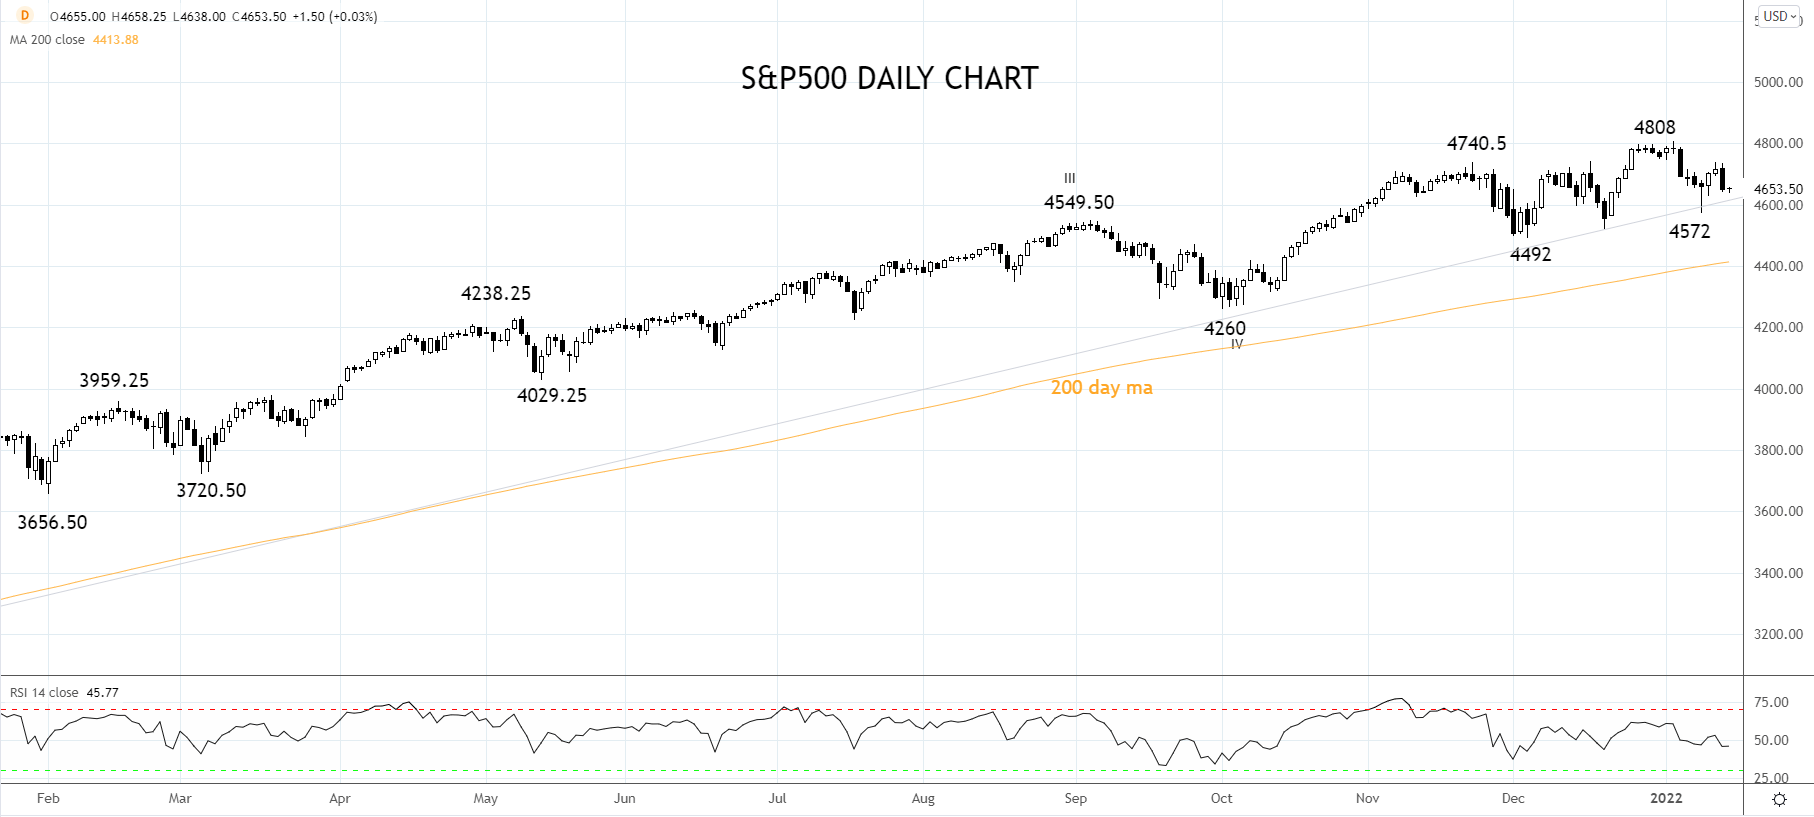
The overnight decline has the S&P500 eyeing important trendline support at 4620/00ish from the March 2020, 2174 low.
Providing the S&P500 remains above 4620/00 (closing basis), look for a push towards 5000 during the first quarter of 2022.
However, should a sustained break below 4620/00ish occur, the risks are for a deeper pullback towards 4400.
Source Tradingview. The figures stated areas of January 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Macro Overview
2021 saw the S&P500 hit fresh record highs on an astonishing 70 separate days. It is noticeable that the first two weeks of 2022 have seen a continuation of the volatility that marked the final months of 2021.
US inflation recently reached an almost 40 year high, hitting an annualised 7% in December. To counter this, the Federal Reserve has become increasingly hawkish.
In response, market expectations have shifted towards faster balance sheet normalization, with "quantitative tightening" to begin in September after Fed lift-off in June or possibly as early as March. A prospect that has rattled tech stocks.
Meanwhile, surging Omicron cases have left hospitals straining under the weight of numbers, disrupting global supply chains and grocery shelves empty. A development that will weigh on Q1 growth, likely to be reflected in some company's forward guidance.
Earnings
Despite the headwinds outlined above, S&P500 companies are expected to deliver strong earnings growth again. According to Factset, "For Q4 2021, the estimated earnings growth rate for the S&P 500 is 21.7%."
Presuming this is the confirmed growth rate for the quarter, it will mark the fourth straight quarter of earnings growth above 20% and lift full years earning growth to more than 40% for the full year.
Guidance
As noted by FactSet in the first week of January, "93 S&P 500 companies have issued EPS guidance for the fourth quarter. This number is slightly below the 5-year average of 100. Of these 93 companies, 56 have issued negative EPS guidance, and 37 have issued positive EPS guidance."
This marks the first time since Q2 2020 that S&P500 companies have issued more negative EPS guidance than positive guidance. Despite this, the estimated (year over year) earnings growth for Q4 2021 is above the expectations from the start of Q4.
Sector Performance
As noted by Factset, the Energy sector led by companies such as Exxon Mobil and Chevron have recorded the largest percentage increase in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at 40.8% (to $28.1 billion from $20.0 billion).
The Consumer Discretionary sector led by Amazon.com has recorded the largest percentage decrease in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at -15.1% (to $27.1 billion from $32.0 billion).
S&P500 Technical Outlook
The overnight decline has the S&P500 eyeing important trendline support at 4620/00ish from the March 2020, 2174 low.
Providing the S&P500 remains above 4620/00 (closing basis), look for a push towards 5000 during the first quarter of 2022.
However, should a sustained break below 4620/00ish occur, the risks are for a deeper pullback towards 4400.
Source Tradingview. The figures stated areas of January 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.


S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.

Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.