



S&P 500 outlook: Oil and bond yields rebound
Investor sentiment was marginally firmer early on Thursday, although optimism quickly faded as crude prices turned positive again on reports that Iran’s supreme leader has issued a directive that its uranium must stay in Iran. Whether that is a dealbreaker remains to be seen, but oil did pop higher by $4 on the news, while European markets and US index futures slipped back into the red.
Share this:
Investor sentiment was marginally firmer early on Thursday, although optimism quickly faded as crude prices turned positive again on reports that Iran’s supreme leader has issued a directive that its uranium must stay in Iran. Whether that is a dealbreaker remains to be seen, but oil did pop higher by $4 on the news, while European markets and US index futures slipped back into the red. For now, markets remain stuck in a cautious holding pattern rather than embracing a full risk-on rally. A deal would likely send stocks sharply higher in Europe and less so on Wall Street. But the longer the stalemate continues, the situation in energy markets will become a significant headwind for global growth, and stocks. At the same time, even another set of exceptional results from Nvidia failed to inject fresh momentum into equities in the way many would normally expect. All eyes are on oil prices which will determine the near term direction of risk assets and the S&P 500 outlook.
Oil markets still dictating the narrative
Crude prices fell sharply in the previous session after fresh optimism emerged surrounding a potential agreement between Washington and Tehran. That helped to ease fears over a prolonged supply disruption in the Strait of Hormuz and pointed to a potential agreement. But Reuters’ report that Iran’s supreme leader has issued a directive that its uranium must stay in Iran does complicate the picture, if true. So, the geopolitical premium on oil remains. Trump repeated that military action remained on the table if negotiations failed and suggested there was little urgency to reach an agreement quickly. That rhetoric helped stabilise prices and reminded investors that energy-driven inflation risks remain very much alive.
This is not the first time markets have attempted to price in a diplomatic breakthrough. Earlier optimism this month faded almost as quickly as it arrived, and traders now appear far less willing to aggressively chase headlines without concrete progress. The increasingly hostile tone from both sides has only reinforced that caution.
Bond markets becoming increasingly important
Attention has also been on US Treasury yields, which continue to send warning signals for risk assets. The 30-year Treasury yield briefly touched 5.20% on Wednesday — its highest level since 2007 — before easing back alongside crude prices later in the day. Today, both are bouncing back, and so stock markets are coming under a bit of pressure again.
Only a few months ago, markets were steadily moving towards a softer inflation outlook, with investors increasingly convinced that the Federal Reserve would eventually deliver additional rate cuts. But the escalation in Middle East tensions and concerns over the Strait of Hormuz triggered a sharp repricing across global bond markets.
What has been remarkable, however, is how resilient US equities — particularly technology stocks — have remained throughout the move higher in yields. The Nasdaq 100 only recently pulled back from record highs despite borrowing costs surging again.
That resilience may now face a tougher test. If yields resume their climb, pressure on the high-valuation momentum trade is likely to intensify, increasing the risk of a broader correction across equity markets. Equally, any meaningful de-escalation in the Middle East would probably trigger a rally in bonds, lower yields and provide renewed support for equities. Much still hinges on oil and developments around the Strait of Hormuz.
Technical S&P 500 outlook: Momentum is beginning to cool
From a technical standpoint, the broader trend still remains constructive despite recent volatility. However, markets are increasingly showing signs of becoming stretched in the short term, raising the probability of either consolidation or a modest pullback.
From a technical standpoint, the broader trend still remains constructive despite recent volatility. However, markets are increasingly showing signs of becoming stretched in the short term, raising the probability of either consolidation or a modest pullback.
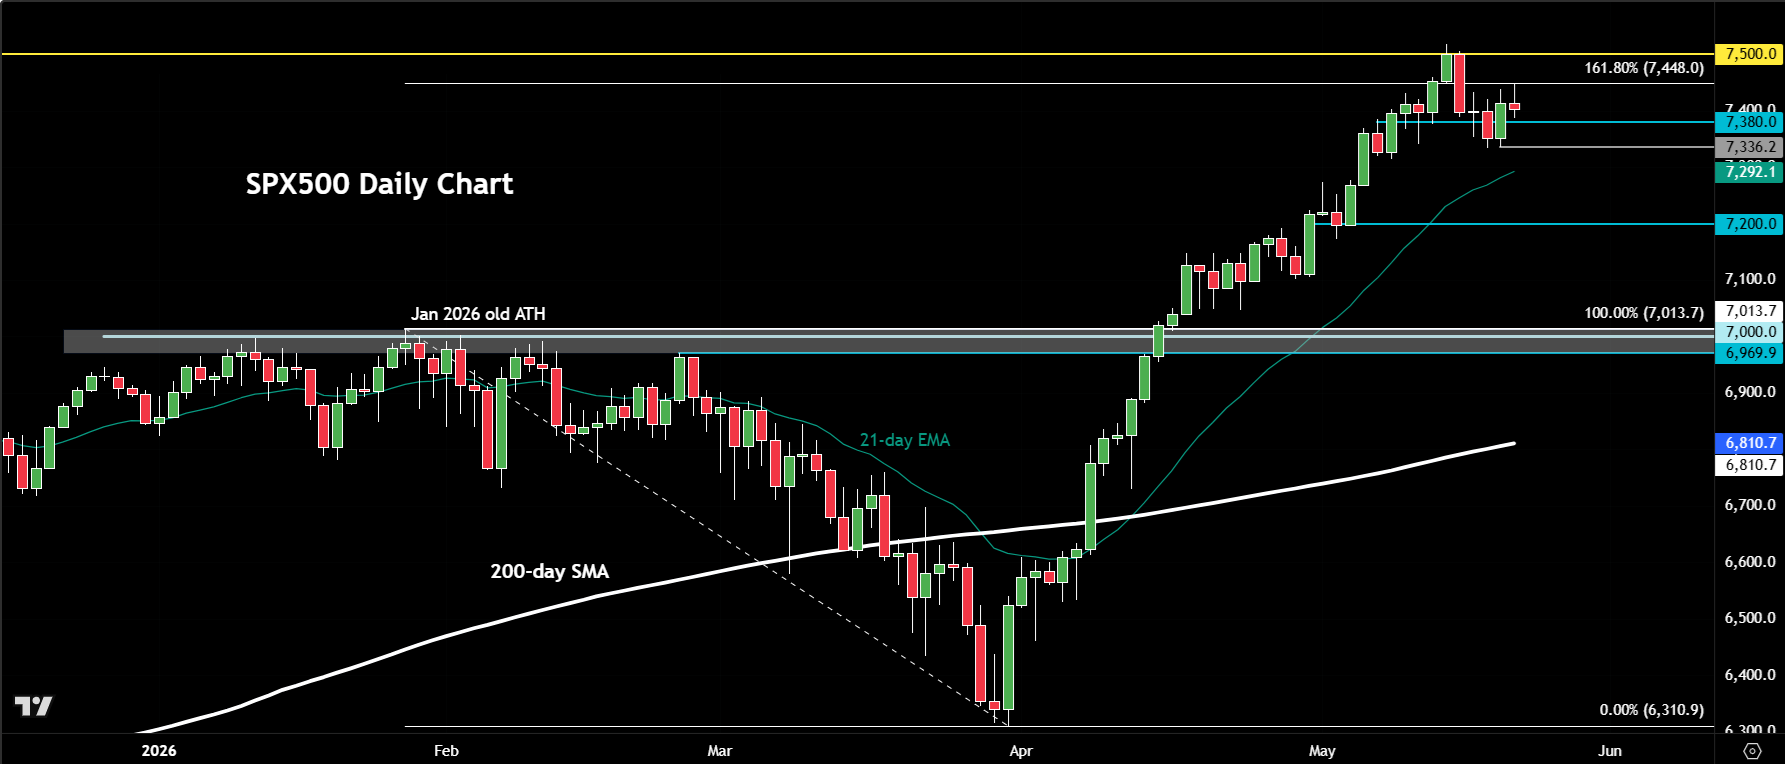
In many respects, that pause may already be underway. The S&P 500 has spent roughly the past week trading around similar levels, suggesting momentum has stalled rather than accelerated. The next phase now depends heavily on the direction of oil prices and bond yields.
The index has already extended into the 161.8% Fibonacci extension of the major downswing that began in late January and bottomed towards the end of March. That extension sits near the 7,448 region and has started to attract profit-taking activity.
Initial support is seen around 7,380. However, a move below yesterday’s low near 7,336 could expose a deeper retracement towards 7,300 and then 7,200.
Longer term, the more significant support zone remains around 7,000— effectively the previous all-time highs established earlier this year. Reaching those levels would likely require a renewed escalation in geopolitical tensions alongside another sharp rise in both crude prices and Treasury yields.
On the upside, resistance levels remain relatively thin beyond the psychologically important 7,500 area, while last Thursday’s record high near 7,540 remains the next obvious reference point for traders watching for signs of exhaustion.
For now, any weakness still appears likely to remain relatively contained. A more meaningful correction would probably require clearer evidence that underlying momentum across the broader market is beginning to deteriorate more decisively.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.