



S&P 500 hints at swing high following Powell’s hawkish speech: The Week Ahead
Hawkish comments from Jerome Powell with the threat of further hikes snapped Wall Street’s 8-day wining streak, and hints at a swing high on the S&P 500 heading into the weekend. And that puts traders on high alert for next week’s inflation report, not to mention the threat of a government shutdown if the debt ceiling is not raised by Friday.
Share this:

S&P 500 hints at swing high following Powell’s hawkish speech: The Week Ahead
Hawkish comments from Jerome Powell with the threat of further hikes snapped Wall Street’s 8-day wining streak, and hints at a swing high on the S&P 500 heading into the weekend. And that puts traders on high alert for next week’s inflation report, not to mention the threat of a government shutdown if the debt ceiling is not raised by Friday.
The week that was:
- Wall Street rallied in the first half of the week with an 8-day winning streak (its best streak in two years) despite hawkish comments from some Fed members
- Yet a hawkish speech from Jerome Powell snapped the winning streak, seeing the S&P 500, Nasdaq 100 and Dow Jones formed bearish engulfing days on Thursday
- Powell warned that the Fed are not yet confident policy is tight enough and that they will not hesitate to hike again if need be
- Bond yields recouped some of last week’s losses, with the 2-year nearly recouping all by Thursday’s close (the 2-year is more sensitive to monetary policy expectations)
- The RBA Hiked their cash rate by 25bp to 4.35%, yet traders positioned for a hawkish hike were disappointed without a firm commitment to further hikes in the statement
- Oil prices continued to unwind with TWI crude oil falling to a 3-month low amid concerns over demand from the US and China
- China’s consumer prices slipped back into deflation at -0.2% y/y and -0.1% m/m, to show the level if stimulus to revive the economy remains inadequate
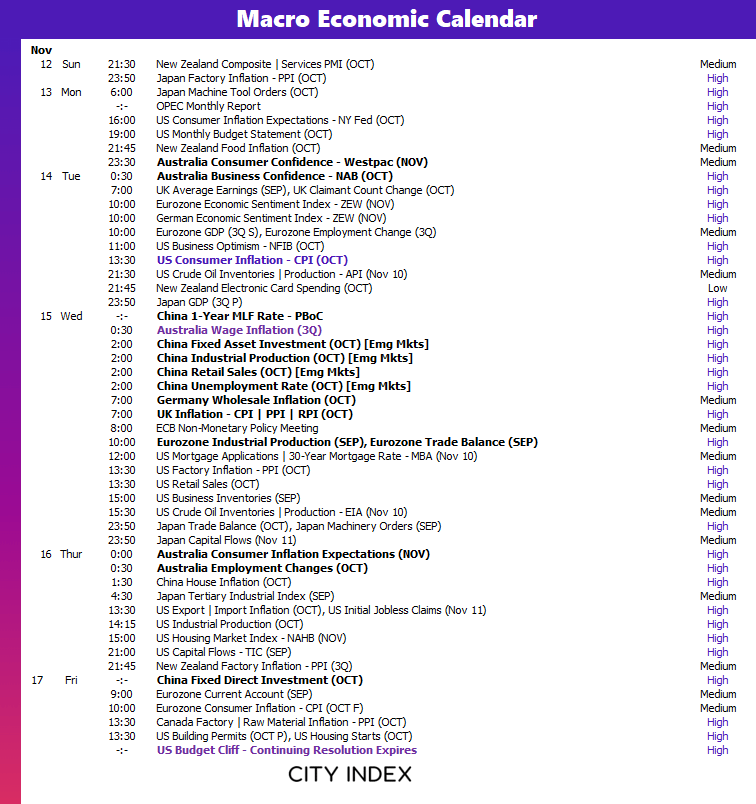
The week ahead (calendar):

This content will only appear on City Index websites!
Earnings This Week
Look at the corporate calendar and find out what stocks will be reporting results in Earnings This Week.
The week ahead (key events and themes):
The week ahead (key themes and events):
- US government shutdown
- US inflation
- Australian wage inflation employment data
- China data
US government shutdown
This topic keeps on resurfacing, and it certainly seems it is popping up with an increased frequency. But once again the US government is approaching a shutdown unless a resolution can be found ahead of November 17th, when the government is expected to run out of money. Mike Johnson, the new Republican house speaker, is expected to reveal his plans of how to avoid the catastrophe over the next coupe of days. But if history is anything to go by, talks will run to the final hour and could weigh on risk appetite, before the debt ceiling is inevitably raised once more to potentially see risk bounce.
Market to watch: EURUSD, USD/JPY, WTI Crude Oil, Gold, S&P 500, Nasdaq 100, Dow Jones
S&P 500 technical analysis (daily chart)
The S&P 500 rallied just over 7% from the October 26 low to the daily high ahead of Powell’s speech, in a relatively straight line with a couple of bullish gaps along the way. Then Jerome Powell delivered his hawkish speech, traders took note, forcing bulls out and bears to reinitiate and close the day with a prominent bearish engulfing day.
This places a potential swing high around a cluster of technical levels including gap resistance, October highs, 4400 handle and a bearish trendline. As we head into the weekend, we might see the S&P 500 try and close the bullish gap around 4320, a break beneath which brings the 200-day EMA and lower bullish gap into focus.
US inflation
With markets still absorbing hawkish comments from Jerome Powell, next week’s inflation report becomes the more important because any signs of rising price pressures could see markets reprice the potential for another hike. With core CPI rising 0.3% m/m for the past two months and the annual rate still at 4.1%, it is difficult for the Fed not to maintain a hawkish narrative. And that could keep a lid on appetite for risk unless we’re treated to a refreshingly soft set of inflation numbers next week.
Market to watch: EURUSD, USD/JPY, WTI Crude Oil, Gold, S&P 500, Nasdaq 100, Dow Jones
Australian wage inflation employment data
Despite a new governor at the helm, the RBA’s approach to hiking seems very familiar; do it as little as possible. When inflation data was broadly higher than expected, producer price and retail sales also beat, many economists upgraded their forecasts for two more hikes this year. So when they RBA delivered the 25bp hike alongside a slightly tweaked statement to suggest incoming data will decide if more hikes are to follow, some AUD/USD bulls were caught on guard. But now we know that the RBA remain very much in a data-dependent mode, that clearly makes incoming data the more important.
For the hawks calling for another hike or two, a hotter wage price index alongside okay or better employment data could be the key.
Market to watch: AUD/USD, NZD/USD, AUD/NZD, NZD/JPY, AUD/JPY, ASX 200
Data from China and Japan
Japan’s GDP is expected to contract by -0.1% in Q3 and post a trade deficit in October due to the weaker yen, according to ING. A slew of data from China is also in focus, including industrial production, investment and retail sales. Whilst retail sales are expected to rise, it’s likely down to a basing effect as last year’s lockdowns drop out of the annual figure. And with inflation and PMIs coming in softer, there’s now an expectation for industrial production and investment to follow suit. Whilst this is deflationary for the rest of the world, it also points to slower global growth.
Market to watch: USD/CNH, USD/JPY, S&P 500, Nasdaq 100, Dow Jones, VIX, AUD/JPY
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nasdaq 100 forecast: Nvidia troubles put AI recovery into question
The recovery for major indices this week has helped repair much of the technical damage inflicted by last week’s sell-off, but the latest developments with Nvidia suggest investors are not quite ready to put the underlying risks behind them. The Nasdaq 100 led other US index futures lower overnight, with falls of around 0.8%.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.