



Stocks Potential Risks That May Derail Rally
Looking ahead, there are a few key risks facing European and global stock markets in general.
Share this:

The global stock market rally that began in early January continued for another day yesterday and continued this morning in Europe, although indices here momentarily gave up their gains while US index futures turned flat. This morning’s brief dip came about after Bloomberg reported that a meeting between Presidents Donald Trump and Xi Jinping to sign an agreement to end the US-China trade war won’t occur this month and is more likely to happen in April at the earliest. Apparently, this was according to three people familiar with the matter. Truth be told, if this story turns out to be correct, it shouldn’t come as major surprise given that Trump himself has already hinted at the prospects of delay when he said the US was not “in a hurry” to a sign a deal. Thus, there is a possibility that any weakness related to US-China trade talks being delayed could prove to be short-lived.
Looking ahead, though, there are a few key risks facing European and global stock markets in general. But sentiment is currently positive given the sharp year-to-date gains for China (nearly 20%), although the rally here has stalled a little over the past few days, while in the US the S&P 500 hit a new high for the year yesterday. Sentiment has so far been boosted by various factors, including:
- Hopes over (an eventual) trade deal between US and China
- Falling bond yields amid renewed dovishness from major central banks, boosting the appeal of the riskier equity markets
- Introduction of various fiscal and monetary stimulus measures from China
- Global economy not performing as poorly at the start of this year as had been expected
But despite the sharp gains for the US and China, European markets are lagging behind slightly. Here, investors are not as jubilant in part because of ongoing Brexit concerns and weak economic performances across the Eurozone. As well as exports being hit by falling Chinese demand, the recent emerging market currency crisis in places like Turkey has also weighed on growth. But with the ECB introducing new long-term loans for banks and pushing back its rate hike expectations, investors have been warming towards European equities of late. Still, the markets face a few major risks, which among other things, include:
- Potential for a disorderly Brexit
- Possibility of US-China trade talks to break down (not to mention the positivity being nearly price in)
- The imposition of more tariffs on European exports by the US
- Further economic slowdown in Europe
- Profit-taking after big gains
- Q1 US earnings being more disappointing than expected, with mavens at FactSet predicting S&P 500 Q1 earnings to be -3.4%, which would be the first year-over-year decline in earnings since Q2 2016. According to FactSet’s estimates, the forward 12-month price to earnings ratio for the S&P is 16.0, which is below the 5-year average of 16.4.
So, investors are faced with elevated levels of risks as we head towards the first quarter. While the recent falls in bond yields amid the prospects of interest rates remaining low for longer may keep the downside limited, I am sceptical that the gains we have seen so far this year can be repeated in the upcoming months. Above all, there’s the potential for profit-taking with indices looking a little overstretched again.
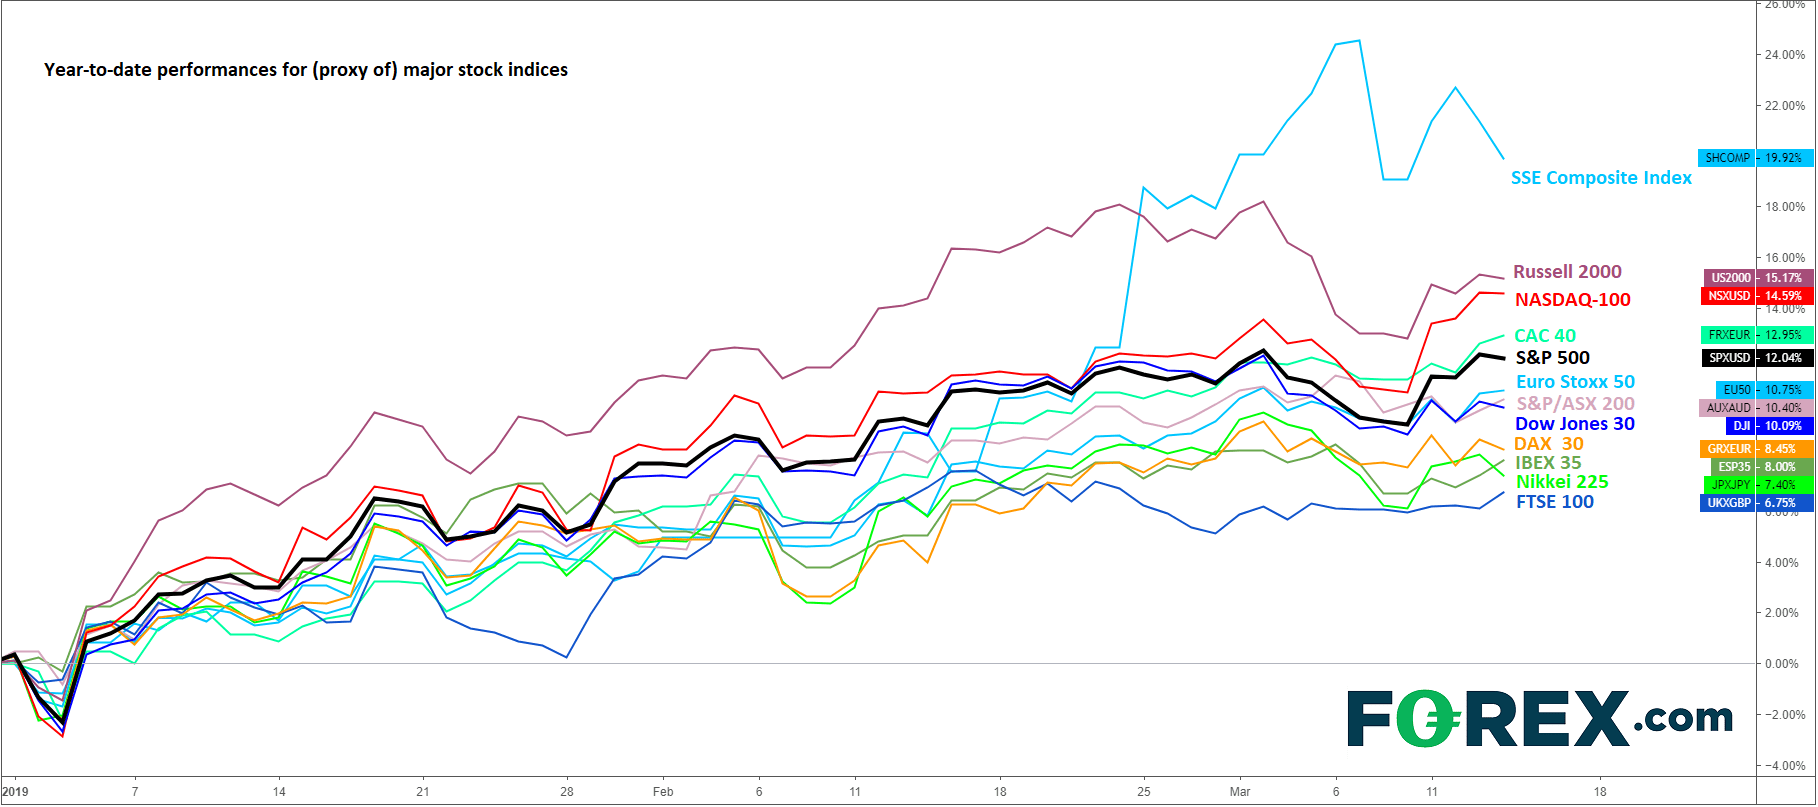
Source: TradingView and FOREX.com. Please note, this product is not available to US clients
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.

Dow Jones Analysis: Is the DJIA Making a Comeback?
Recent trading sessions have become increasingly relevant for the Dow Jones, as the index has started to regain bullish momentum heading into the end of the week. Over the last three sessions, the DJIA has advanced by more than 0.6%, allowing buying pressure to regain prominence and raising the possibility of a more consistent short-term recovery.
ASX 200 Slides as Oil, Yields and Rate Risks Hit Sentiment
The ASX 200 suffered its worst week in six months as surging oil, higher bond yields and renewed rate-hike bets drove a broad risk-off move.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.