



US open: Stocks rise as recession fears are pushed aside for now
US stocks are rising despite recession fears lingering. The mood had improved even if the data hasn’t.
Share this:

US futures
Dow futures +0.73% at 30900
S&P futures +0.85% at 3825
Nasdaq futures +0.87% at 11796
In Europe
FTSE +1.5% at 7137
Dax +0.7% at 13035
Euro Stoxx +1.5% at 3491
New home sales, consumer confidence due
US stocks are set to rise after solid gains in the previous session after Powell wrapped up his appearance in Congress and ahead of today’s consumer confidence data.
The leading indices appear set to book gains across the week after three weeks of declines.
Federal Reserve President Powell was clear that the Fed is committed to bringing down soaring inflation, even if it means pushing the US into recession and lifting unemployment.
Risk sentiment has undoubtedly improved over the past two days, even if the data hasn’t. Yesterday the composite PMI fell to 51.2, down from 53.8, highlighting the slowdown in business activity and the likelihood of a recession.
Recession fears have perhaps been best played out in the commodity sector, which has seen base metal, and oil trends lower across the week on demand concerns.
Today’s attention is now turning to US new home sales, which are expected to show that the housing market continues to cool as mortgage rates rise and affordability challenges grow.
Looking out later in the session, US Michigan consumer confidence will be under the spotlight after falling to a record low preliminary reading of 52 in June.
.
In corporate news:
FedEx is on the rise after the delivery giant reported upbeat quarterly earnings and better-than-expected guidance.
Netflix is also rising pre-market after announcing that it will cut 300 jobs, equating to around 4% of the workforce.
Where next for the Nasdaq?
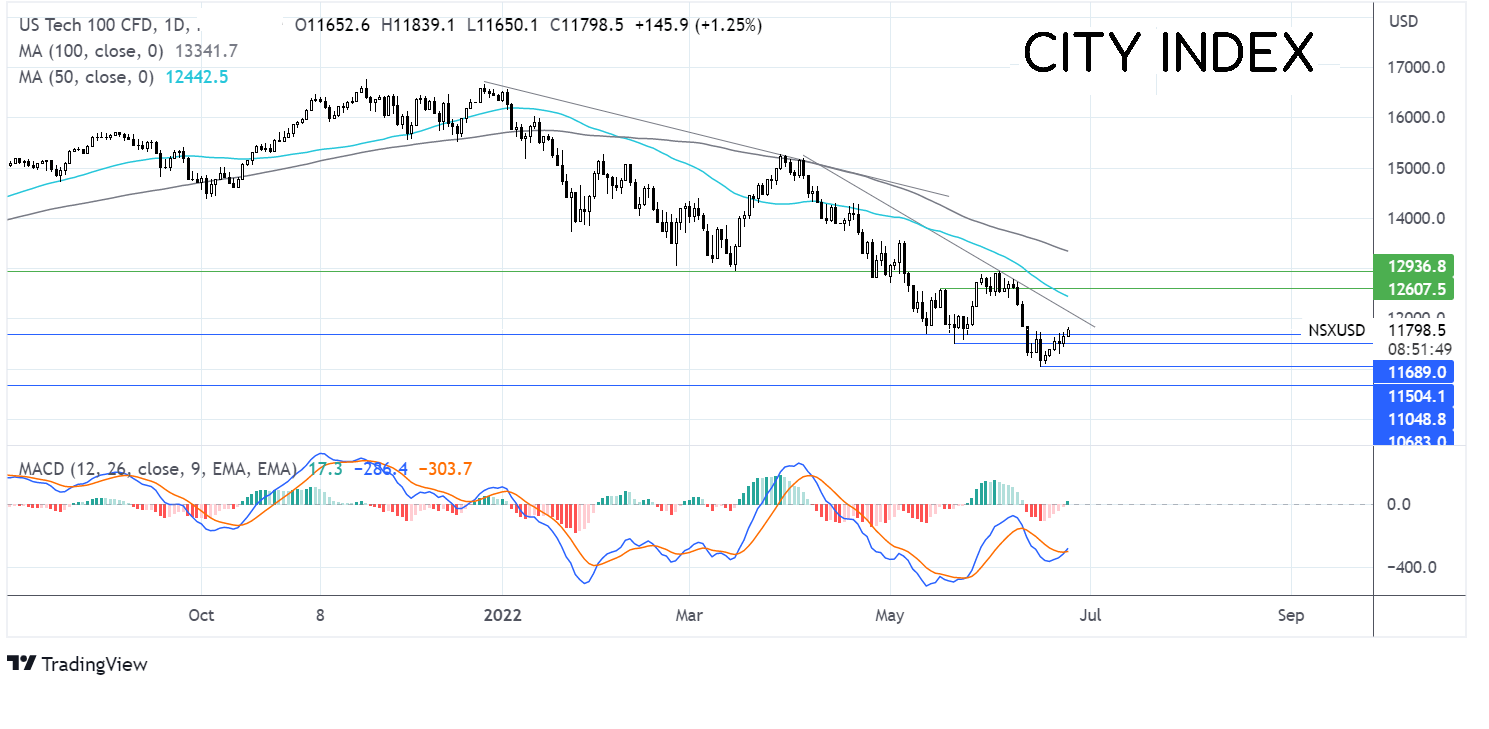
The Nasdaq is extending its rebound off the 2022 low of 11035, taking out resistance at 11500 and 11700, the May 11 low. This, combined with the bullish crossover on the MACD, keeps buyers hopeful of further upside. Buyers will look for a move over 12065, the falling trendline support, and the 50 sma at 12477. A rise over 12900 could see buyers gain traction.
FX markets – USD steady, markets quiet.
USD is holding steady after mild gains in the previous session, although the USD is set to decline across the week. Concerns of a recession in the US have seen bond yields ease, pulling the USD lower.
EURUSD is holding steady despite German IFO business sentiment falling further in May. Concerns over gas security in some European countries, including German, could also be weighing on demand for the euro. Meanwhile, the stronger equity market is supporting the pair.
GBP/USD is holding steady in quiet trade despite retail sales falling in May. Sales declined -0.5% MoM, after a downwardly revised 0.4% rise in April. The slide in sales, particularly supermarket sales suggests that consumer are changing their shopping habits as inflation rises.
GBP/USD +0.18% at 1.2267
EUR/USD +0.47% at 1.0557
Oil rises but sees losses across the week
Oil prices are rising today as tight supply concerns are in focus ahead of the OPEC meeting next week. However, across the week, oil prices are set to decline for a second straight week.
Fears over a recession in the US have raised concerns over the demand outlook and driven prices lower. They are pulling oil off by 10% in just two weeks.
Supply concerns are in focus as OPEC member Libya is experiencing an almost complete shutdown of output due to unrest in the country.
OPEC will meet next week and is expected to stick with the higher output agreed at the start of the month. Of course, given Libya’s position, compliance with output quotas is questionable.
WTI crude trades +0.8% at $109.56
Brent trades +0.8% at $113.22
Looking ahead
15:00 US new home sales
15:00 Michigan consumer confidence
18:00 Baker Hughes rig count
How to trade with City Index
You can trade with City Index by following these four easy steps:
1. Open an account, or log in if you’re already a customer
2. Search for the company you want to trade in our award-winning platform
3. Choose your position and size, and your stop and limit levels
4. Place the trade


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.