



US open: Futures rise cautiously ahead of a critical week
Stocks are set to rise, paring losses from the previous week as investors lok ahead to inflation data and the Federal Reserve interest rate decision later in the week.
Share this:

US futures
Dow futures +0.3% at 33550
S&P futures +0.3% at 3945
Nasdaq futures +0.3% at 11600
In Europe
FTSE -0.27% at 7449
Dax -0.32% at 14317
All eyes on Tuesday’s inflation data & Wednesday’s FOMC
US stocks are set to open modestly higher on Monday after losses across the previous week and as investors look ahead to a critical week that will see the release of US inflation data and the final Federal Reserve interest rate decision of the year.
Stocks fell last week, with the Dow Jones dropping 2.8% in its worst weekly performance since September after stronger-than-expected data raised concerns over the Fed’s ability to slow down the pace of aggressive rate hikes, as guided for by fed chair Jerome Powell in a speech at the end of November.
The market is currently pricing in a 75% probability of a 50 basis point rate hike and a 25% chance of a 75 basis point rate hike. The Federal Reserve’s rate decision will come after the release of U.S. consumer price inflation data on Tuesday, which is expected to cool to 7.3% from 7.7% in October. The inflation data is unlikely to deter the Fed from a 50 basis point hike this month. However, cooling inflation could raise the chances of a 25 basis point rate hike in January.
Corporate news:
Microsoft will be in the spotlight after announcing that it will take a 4% stake in the London Stock Exchange Group as part of a new strategic partnership.
Rivian falls pre-market after pressing pause on its joint venture with Mercedes-Benz.
Where next for the Nasdaq?
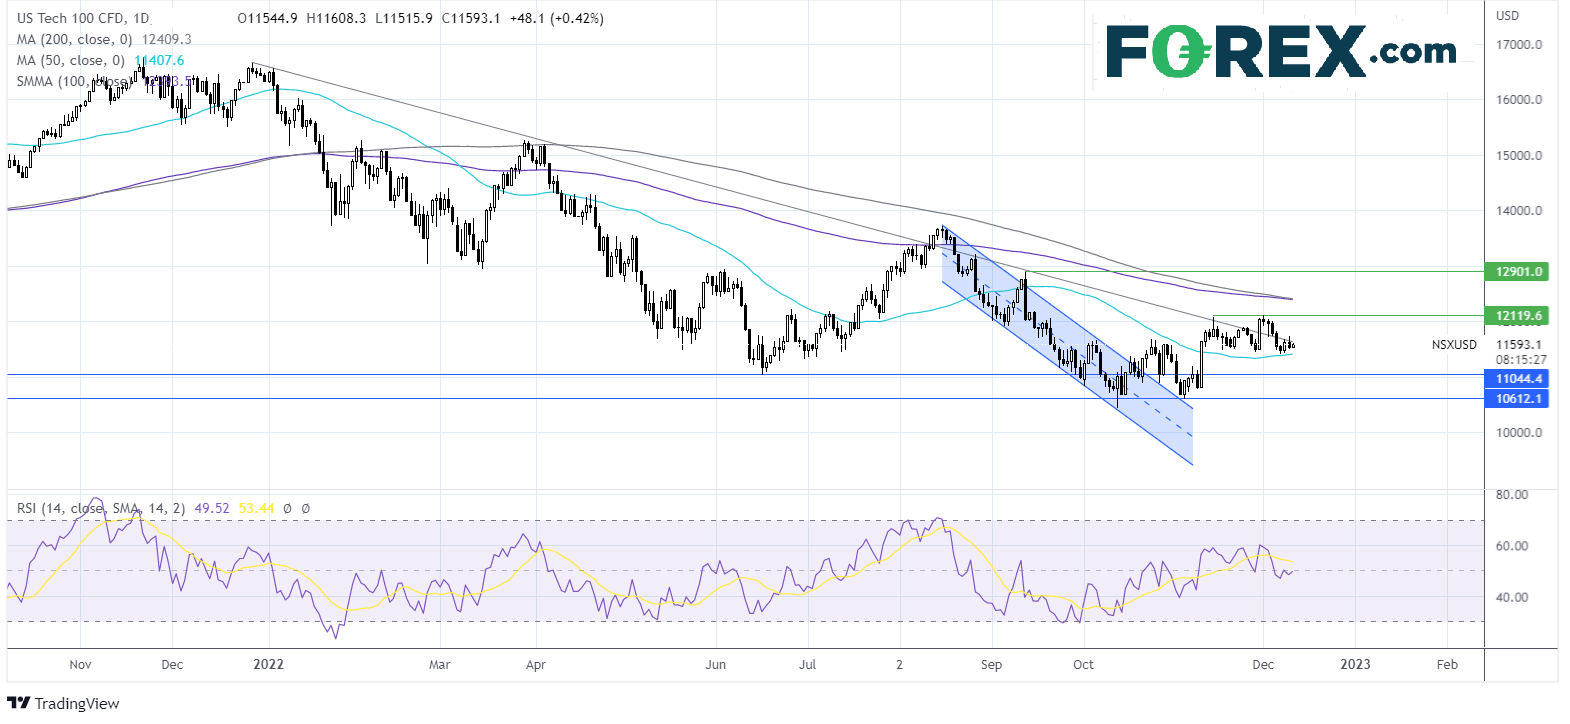
The Nasdaq has been trading range bound since mid-November, capped on the upside by 12,120 and on the lower side by the 50 sma at 11,370. The RSI is neutral at 50, giving away a few clues. The price has slipped below year long falling trend line. A rise above the trendline at 11,650 is needed before buyers can test resistance once again at the December high of 12,120. A move above here exposes the 100 and 200 sma at 12,450, with a rise above the latter significant because the price has traded below the 200 sma since February. On the downside, sellers will be looking for a break below 50 sma to bring 11,000, the June low, into play ahead of 10600, the November low.
FX markets – USD rises, GBP jumps.
The USD is falling, paring gains from last week as investors look ahead to the Federal Reserve interest rate decision on Wednesday. The Fed is widely expected to raise interest rates by 50 basis points, a downshift from the 75 basis point hikes at the past four meetings.
EURUSD is heading higher as the market mood improves and despite a quiet economic calendar today. This is set to change tomorrow with the release of German inflation figures and German ZEW economic sentiment data ahead of the ECB rate decision later in the week,
GBP/USD trades higher after the UK economy rebounded faster than expected in October. GDP rose 0.5% MoM in October after contracting 0.6% in September owing to the Royal funeral. Even so, the UK economy is still expected to tip into recession in the current quarter.
GBP/USD +0.20% at 1.2291
EUR/USD +0.3% at 1.0560
Oil extends declines
Oil prices are heading lower after falling almost 11% last week ask, as concerns over a slowing global economy offset supply concerns coming from the closure of a key pipeline and amid Russian threats of a production cut.
President Putin said he could cut production and refuse to sell oil to countries imposing a price cap on Russian oil, which hurt the supply outlook. Furthermore, news that the keystone oil pipeline leak in the USA remains unrepaired with no timeline as to when operations will resume is also hurting supply prospects.
Oil markets continue to digest the news that China, the world's largest oil importer, is loosening strict Covid policies. However, with infections in China continuing to rise sharply, the market remains nervous over whether China will proceed with exiting the economically damaging policies if hospitalisations keep rising.
WTI crude trades -0.4% at $71.00
Brent trades at -0.6% at $75.85
Looking ahead
19:25 BoC’s Macklem speech
US futures
Dow futures +0.3% at 33550
S&P futures +0.3% at 3945
Nasdaq futures +0.3% at 11600
In Europe
FTSE -0.27% at 7449
Dax -0.32% at 14317
Learn more about trading indices
All eyes on Tuesday’s inflation data & Wednesday’s FOMC
US stocks are set to open modestly higher on Monday after losses across the previous week and as investors look ahead to a critical week that will see the release of US inflation data and the final Federal Reserve interest rate decision of the year.
Stocks fell last week, with the Dow Jones dropping 2.8% in its worst weekly performance since September after stronger-than-expected data raised concerns over the Fed’s ability to slow down the pace of aggressive rate hikes, as guided for by fed chair Jerome Powell in a speech at the end of November.
The market is currently pricing in a 75% probability of a 50 basis point rate hike and a 25% chance of a 75 basis point rate hike. The Federal Reserve’s rate decision will come after the release of U.S. consumer price inflation data on Tuesday, which is expected to cool to 7.3% from 7.7% in October. The inflation data is unlikely to deter the Fed from a 50 basis point hike this month. However, cooling inflation could raise the chances of a 25 basis point rate hike in January.
Corporate news:
Microsoft will be in the spotlight after announcing that it will take a 4% stake in the London Stock Exchange Group as part of a new strategic partnership.
Rivian falls pre-market after pressing pause on its joint venture with Mercedes-Benz.
Where next for the Nasdaq?
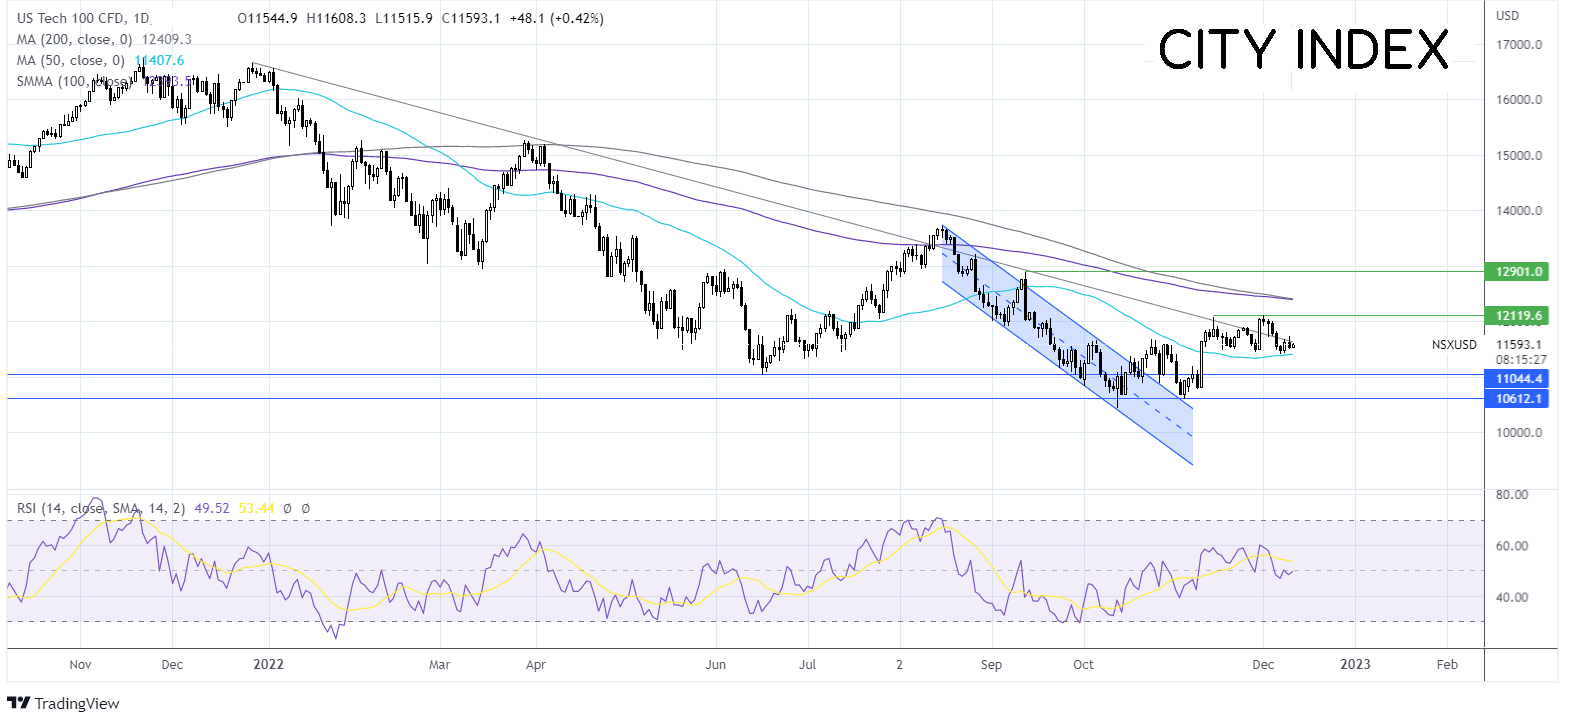
The Nasdaq has been trading range bound since mid-November, capped on the upside by 12,120 and on the lower side by the 50 sma at 11,370. The RSI is neutral at 50, giving away a few clues. The price has slipped below year long falling trend line. A rise above the trendline at 11,650 is needed before buyers can test resistance once again at the December high of 12,120. A move above here exposes the 100 and 200 sma at 12,450, with a rise above the latter significant because the price has traded below the 200 sma since February. On the downside, sellers will be looking for a break below 50 sma to bring 11,000, the June low, into play ahead of 10600, the November low.
FX markets – USD rises, GBP jumps.
The USD is falling, paring gains from last week as investors look ahead to the Federal Reserve interest rate decision on Wednesday. The Fed is widely expected to raise interest rates by 50 basis points, a downshift from the 75 basis point hikes at the past four meetings.
EURUSD is heading higher as the market mood improves and despite a quiet economic calendar today. This is set to change tomorrow with the release of German inflation figures and German ZEW economic sentiment data ahead of the ECB rate decision later in the week,
GBP/USD trades higher after the UK economy rebounded faster than expected in October. GDP rose 0.5% MoM in October after contracting 0.6% in September owing to the Royal funeral. Even so, the UK economy is still expected to tip into recession in the current quarter.
GBP/USD +0.20% at 1.2291
EUR/USD +0.3% at 1.0560
Oil extends declines
Oil prices are heading lower after falling almost 11% last week ask, as concerns over a slowing global economy offset supply concerns coming from the closure of a key pipeline and amid Russian threats of a production cut.
President Putin said he could cut production and refuse to sell oil to countries imposing a price cap on Russian oil, which hurt the supply outlook. Furthermore, news that the keystone oil pipeline leak in the USA remains unrepaired with no timeline as to when operations will resume is also hurting supply prospects.
Oil markets continue to digest the news that China, the world's largest oil importer, is loosening strict Covid policies. However, with infections in China continuing to rise sharply, the market remains nervous over whether China will proceed with exiting the economically damaging policies if hospitalisations keep rising.
WTI crude trades -0.4% at $71.00
Brent trades at -0.6% at $75.85
Learn more about trading oil here.
Looking ahead
19:25 BoC’s Macklem speech
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.