



US open: Futures rise with midterm elections in focus
Stocks are rising with all eyes on the midterm elections. Is a gridlock government coming?
Share this:

US futures
Dow futures +0.2% at 32916
S&P futures +0.2% at 3816
Nasdaq futures +0.4% at 11029
In Europe
FTSE +0.09% at 7306
Dax +0.41% at 13590
Gridlock in Washington?
US stocks are pointing to modest gains on the open, extending the winning run for stocks into a third straight day as investors look ahead to the crucial midterm elections.
The latest polls suggest that the Republican party is likely to take back with House of Representatives and could potentially take back the Senate as well. Let’s not forget that Americans will be heading to the polls at a time when inflation is at multi-decade highs and a recession is looming.
Should Republicans take control of Congress, or at least the House of Representatives, it would result in gridlock in Washington, making it much harder for President Biden to push through his agenda, which includes antitrust regulations on big tech and social spending programmes, which could add to the inflationary environment.
With additional spending risks moderated, the Fed may need to do less to rein in inflation, with is good news for stocks. Additionally, historically speaking, the S&P500 has booked high annualised returns when there is a Democrat in the White House, and Republicans take control of Congress.
The results could be in quickly in the case of a massive wave of Republican support. However, there is also a realistic chance that results won’t be known until tomorrow or later in the week.
Aside from the midterm elections, the economic calendar is quiet. The main focus will be on Thursday’s CPI inflation data, which could provide fresh clues as to the likely move by the Fed in December.
Corporate news:
Lyft trades 19% lower and is flirting with all-time lows after the passenger numbers missed expectations, fueling fears that it is losing market share to larger rivals,
Disney is due to report Q4 earnings after the close. The theme parks and entertainment segment is expected to see revenue jump 39%. Disney+ streaming figures are also likely to impress, rising by 9.3 million.
Tesla is rising pre-market, rising from a yearly low as investors questioned whether Elon Musk would need to sell shares as Twitter losses mount.
Where next for the Dow Jones?
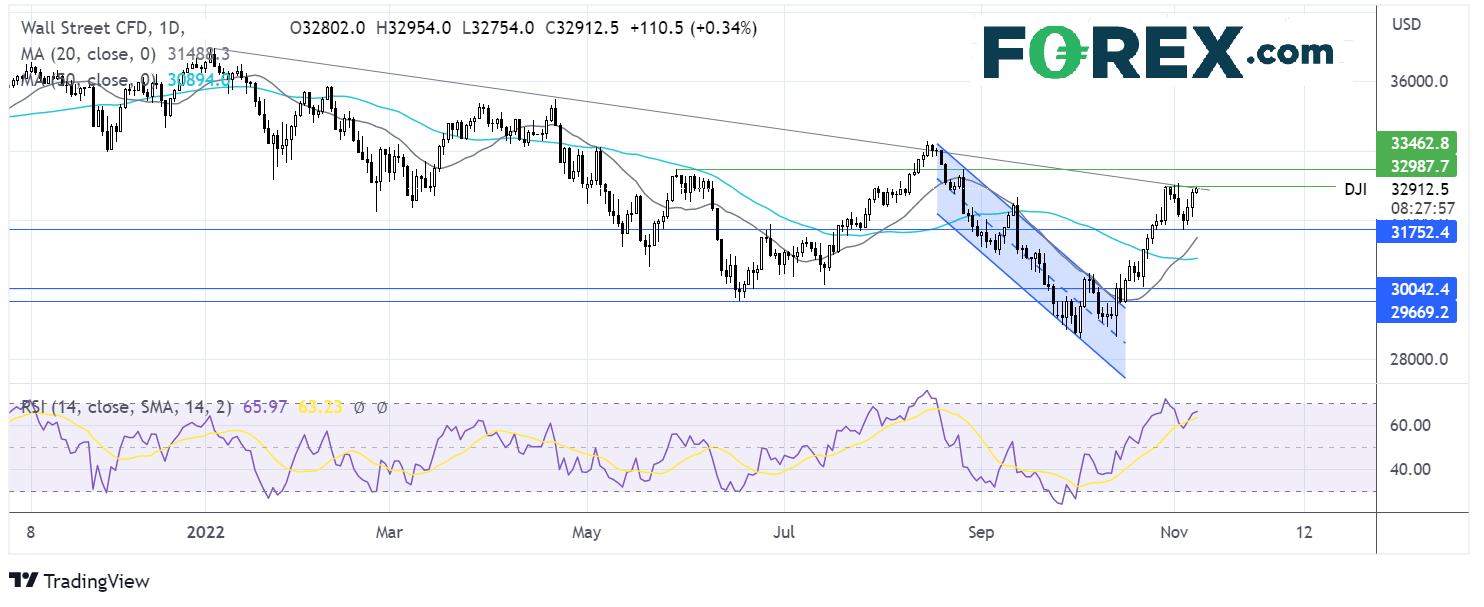
The Dow Jones is pushing higher, targeting 33,000, last week’s high, the round number and the falling trendline resistance. The RSI is over 50, and the 20 sma has crossed over the 50 sma, keeping buyers optimistic of further upside. Buyers will look for a rise over 33,000 to create a higher high before bringing 33460, the August 26 high, into focus. Sellers will look for a move below 317100 to expose the 20 sma at 31300 and the 50 sma at 30850.
FX markets – USD rises GBP falls
The USD is rising after several days of losses as attention turns to the midterm elections and political uncertainty. A gridlock in Washington could be USD-negative if fewer spending programmes are passed.
EURUSD falling on USD strength, despite retail sales coming in as expected. Sales rose 0.4% MoM in September after falling -0.3% in August. Even so, with inflation at a record high, this is unlikely to be a turning point in consumption.
GBPUSD is falling, paring some of yesterday’s strong gains. Talk of cooperation with Europe and hopes of a gas deal with the US lifted sterling yesterday. Today, the bleak outlook is once again dragging on the pound.
GBP/USD -0.62% at 1.1456
EUR/USD -0.2% at 0.9980
Oil jumps on China optimism.
Oil prices are moving mildly lower on Tuesday as recession worries and concerns over COVID in China hurt the demand outlook.
The COVID picture in China lacks clarity. On the one hand, optimism appears to be growing and rumours are swirling that China could be looking to end its strict zero-COVID policy. On the other hand, the Chinese health authority doubled down on its commitment to zero COVID over the weekend.
Meanwhile, cases number are at a six-month high, which means broader lockdown measures could be implemented. The fear of COVID restrictions widening is hurting the demand outlook, pulling oil prices lower.
API stockpile data is due later today.
WTI crude trades -0.74% at $90.20
Brent trades -0.65% at $97.72
Looking ahead
21:30 API crude oil stockpiles
US futures
Dow futures +0.2% at 32916
S&P futures +0.2% at 3816
Nasdaq futures +0.4% at 11029
In Europe
FTSE +0.09% at 7306
Dax +0.41% at 13590
Learn more about trading indices
Gridlock in Washington?
US stocks are pointing to modest gains on the open, extending the winning run for stocks into a third straight day as investors look ahead to the crucial midterm elections.
The latest polls suggest that the Republican party is likely to take back with House of Representatives and could potentially take back the Senate as well. Let’s not forget that Americans will be heading to the polls at a time when inflation is at multi-decade highs and a recession is looming.
Should Republicans take control of Congress, or at least the House of Representatives, it would result in gridlock in Washington, making it much harder for President Biden to push through his agenda, which includes antitrust regulations on big tech and social spending programmes, which could add to the inflationary environment.
With additional spending risks moderated, the Fed may need to do less to rein in inflation, with is good news for stocks. Additionally, historically speaking, the S&P500 has booked high annualised returns when there is a Democrat in the White House, and Republicans take control of Congress.
The results could be in quickly in the case of a massive wave of Republican support. However, there is also a realistic chance that results won’t be known until tomorrow or later in the week.
Aside from the midterm elections, the economic calendar is quiet. The main focus will be on Thursday’s CPI inflation data, which could provide fresh clues as to the likely move by the Fed in December.
Corporate news:
Lyft trades 19% lower and is flirting with all-time lows after the passenger numbers missed expectations, fueling fears that it is losing market share to larger rivals,
Disney is due to report Q4 earnings after the close. The theme parks and entertainment segment is expected to see revenue jump 39%. Disney+ streaming figures are also likely to impress, rising by 9.3 million.
Tesla is rising pre-market, rising from a yearly low as investors questioned whether Elon Musk would need to sell shares as Twitter losses mount.
Where next for the Dow Jones?
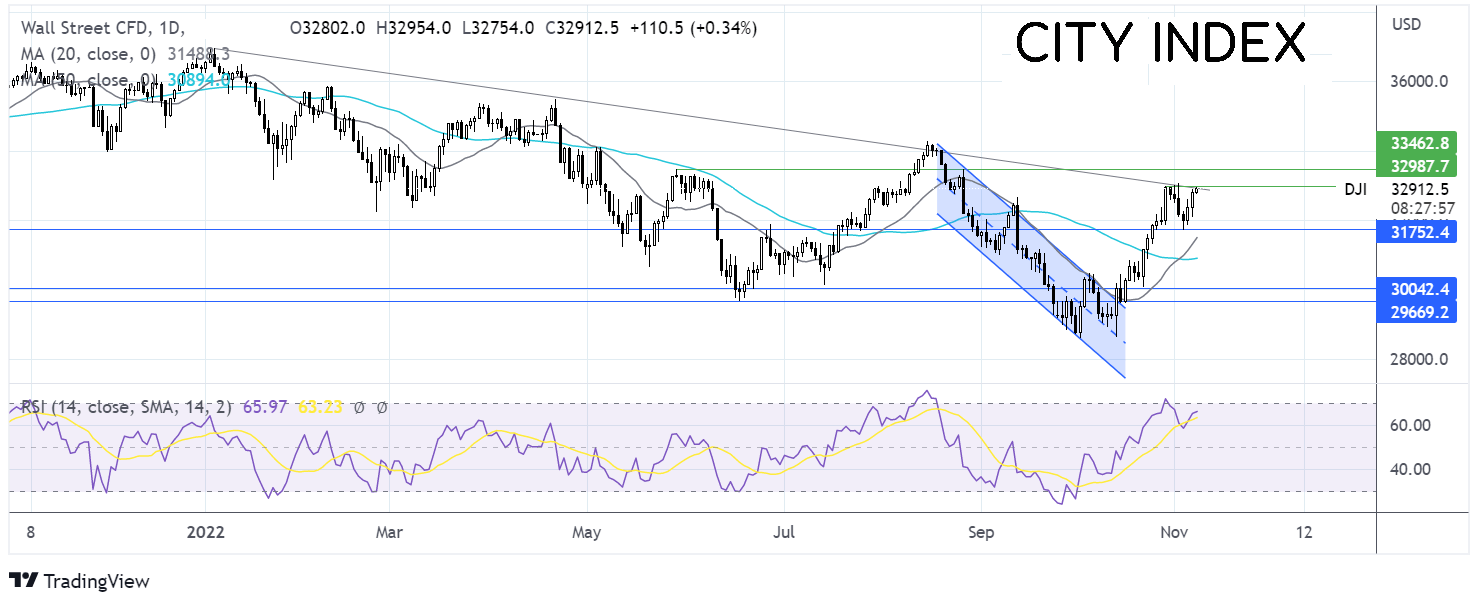
The Dow Jones is pushing higher, targeting 33,000, last week’s high, the round number and the falling trendline resistance. The RSI is over 50, and the 20 sma has crossed over the 50 sma, keeping buyers optimistic of further upside. Buyers will look for a rise over 33,000 to create a higher high before bringing 33460, the August 26 high, into focus. Sellers will look for a move below 317100 to expose the 20 sma at 31300 and the 50 sma at 30850.
FX markets – USD rises GBP falls
The USD is rising after several days of losses as attention turns to the midterm elections and political uncertainty. A gridlock in Washington could be USD-negative if fewer spending programmes are passed.
EURUSD falling on USD strength, despite retail sales coming in as expected. Sales rose 0.4% MoM in September after falling -0.3% in August. Even so, with inflation at a record high, this is unlikely to be a turning point in consumption.
GBPUSD is falling, paring some of yesterday’s strong gains. Talk of cooperation with Europe and hopes of a gas deal with the US lifted sterling yesterday. Today, the bleak outlook is once again dragging on the pound.
GBP/USD -0.62% at 1.1456
EUR/USD -0.2% at 0.9980
Oil jumps on China optimism.
Oil prices are moving mildly lower on Tuesday as recession worries and concerns over COVID in China hurt the demand outlook.
The COVID picture in China lacks clarity. On the one hand, optimism appears to be growing and rumours are swirling that China could be looking to end its strict zero-COVID policy. On the other hand, the Chinese health authority doubled down on its commitment to zero COVID over the weekend.
Meanwhile, cases number are at a six-month high, which means broader lockdown measures could be implemented. The fear of COVID restrictions widening is hurting the demand outlook, pulling oil prices lower.
API stockpile data is due later today.
WTI crude trades -0.74% at $90.20
Brent trades -0.65% at $97.72
Learn more about trading oil here.
Looking ahead
21:30 API crude oil stockpiles
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.


EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.