



US open: Recession fears send stocks tumbling lower
US stocks are dropping sharply and are set for steep weekly losses after the Fed rate hike raised fears of a recession.
Share this:

US futures
Dow futures -1.22% at 29718
S&P futures -1.2% at 3708
Nasdaq futures -1.3% at 11350
In Europe
FTSE -1.7% at 7027
Dax -2.1% at 12270
Investors continue digesting the Fed meeting
US stocks are heading for losses on the open, adding to losses in the previous session, as recession fears build and the dollar appears to be the only place to hide.
Stocks on Wall Street are heading for steep weekly losses after the Federal Reserve hiked rates by 75 basis points earlier in the week and pledged to keep fighting inflation aggressively.
The market is still repricing and repositioning for the idea that the Fed will keep pushing rates higher for longer and then keep them there.
Attention is now turning to the PMI business activity data for clues on how the US private sector is holding up as the risk of recession rises and as inflation and interest rates rise. The manufacturing PMI is expected to slip to 51.1, which is still expanding. The services PMI is expected to rise to 45 from 43.7, contracting but at a slower pace.
Corporate news:
Costco is falling pre-market after the big box retailer reported a squeeze on margins as higher freight and labour costs eat into margins.
Where next for the Nasdaq?
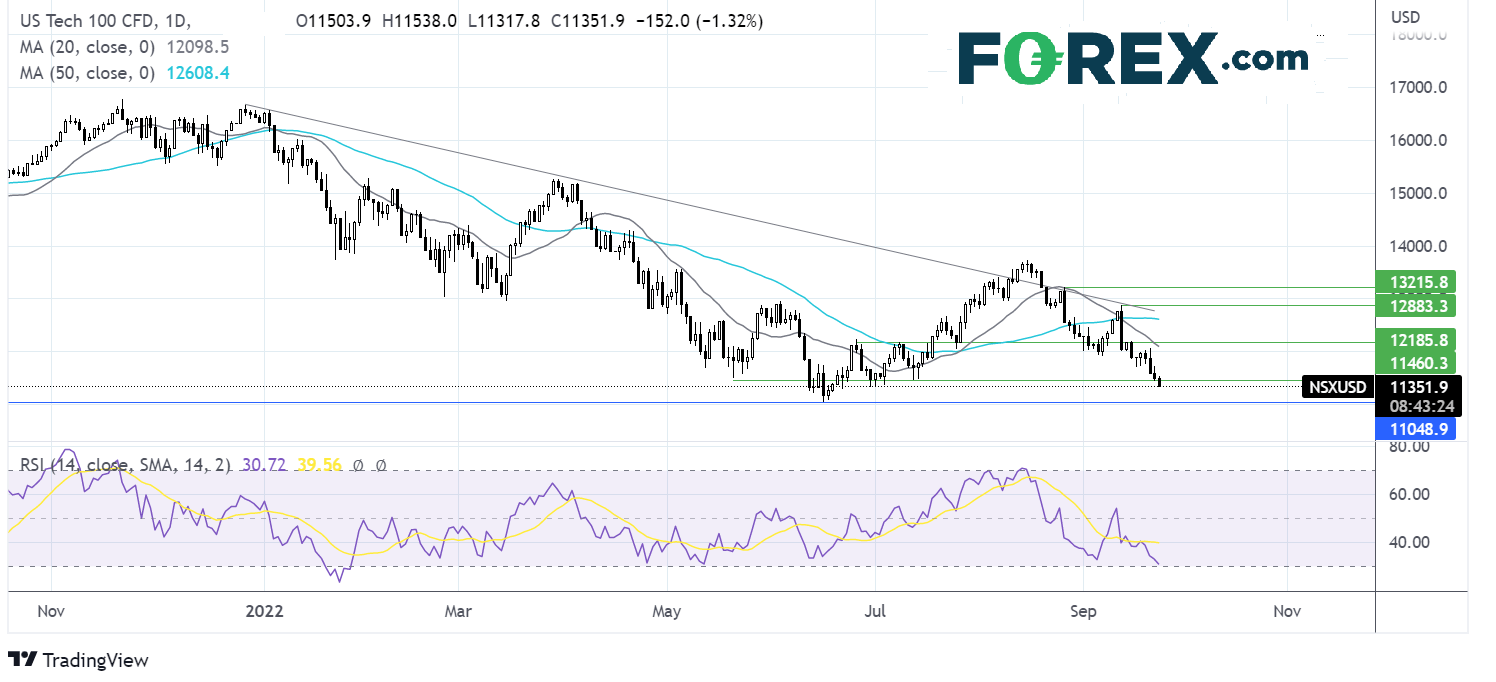
The Nasdaq has broken below support at 11450 and is powering lower. The 20 sma has crossed below the 50 sma. The RSI also supports further downside while it remains out of the oversold territory. Sellers will look to take out the June low at 11036 to bring 1000 psychological level into target. Buyers would need to rise above 12150 to negate the near-term downtrend.
FX markets – USD rises, GBP tanks
The USD is rising, boosted by hawkish Federal Reserve bets and safe haven flows. Fear is spreading through the market and US dollars are proving to be the best hiding place. US dollar index trades at 20-year highs and is set to rise to 112.00
EUR/USD is falling after PMI data painted a bleak picture. The eurozone composite PMI fell more than expected to 48.2 in September, down from 48.9 in August. The data suggests that the eurozone could already be in recession.
GBPUSD plunges after the Chancellor’s mini budget. Far from soothing concerns over the outlook for the UK economy, Liz Truss and Kwasi Kwarteng’s economic plan for the UK has sent the pound plunging. The announcement of the largest tax cuts since 1972 to boost growth and stave off a recession that has already started has triggered a crash in the pound and the bond market.
The sell-off in UK assets reflects the sheer panic as the new government’s stimulus package will not only grow an already sizeable debt burden, potentially to unmanageable levels but will also add to inflationary pressures.
The BoE, which has been reluctant to hike rates aggressively, will need to roll up its sleeves and fight inflation with larger rate hikes. Expectations for a 1% hike in November are already climbing.
It’s difficult to see how the pound can recover from here. Investors are rapidly pulling out of UK assets, and who can blame them? Drawing comparisons historically, the last big tax giveaway in 1972 resulted in rampant inflation, unmanageable debt, and an IMF bailout.
Suddenly pound parity with the USD looks increasingly likely.
GBP/USD -2% at 1.1056
EUR/USD -0.85% at 0.9750
Oil falls 3%
Oil prices are tumbling lower as recession fears grip the market and the USD marches higher. With central banks across the globe hiking rates, fears of a recession are hurting the demand outlook for oil. Quite simply, slower growth means weaker oil demand.
The downside could be capped by heightened tensions as Russian mobilizes more troops to support the ongoing war in Ukraine. Following Putin’s latest threats, the EU is rushing to agree on an oil price cap. The cap could hit Moscow’s revenue which is helping to fund the war.
WTI crude trades -3% at $80.81
Brent trades -2.7% at $87.1
Looking ahead
14:45 US PMI data
18:00 Baker Hughes
US futures
Dow futures -1.22% at 29718
S&P futures -1.2% at 3708
Nasdaq futures -1.3% at 11350
In Europe
FTSE -1.7% at 7027
Dax -2.1% at 12270
Learn more about trading indices
Investors continue digesting the Fed meeting
US stocks are heading for losses on the open, adding to losses in the previous session, as recession fears build and the dollar appears to be the only place to hide.
Stocks on Wall Street are heading for steep weekly losses after the Federal Reserve hiked rates by 75 basis points earlier in the week and pledged to keep fighting inflation aggressively.
The market is still repricing and repositioning for the idea that the Fed will keep pushing rates higher for longer and then keep them there.
Attention is now turning to the PMI business activity data for clues on how the US private sector is holding up as the risk of recession rises and as inflation and interest rates rise. The manufacturing PMI is expected to slip to 51.1, which is still expanding. The services PMI is expected to rise to 45 from 43.7, contracting but at a slower pace.
Corporate news:
Costco is falling pre-market after the big box retailer reported a squeeze on margins as higher freight and labour costs eat into margins.
Where next for the Nasdaq?
The Nasdaq has broken below support at 11450 and is powering lower. The 20 sma has crossed below the 50 sma. The RSI also supports further downside while it remains out of the oversold territory. Sellers will look to take out the June low at 11036 to bring 1000 psychological level into target. Buyers would need to rise above 12150 to negate the near-term downtrend.

FX markets – USD rises, GBP tanks
The USD is rising, boosted by hawkish Federal Reserve bets and safe haven flows. Fear is spreading through the market and US dollars are proving to be the best hiding place. US dollar index trades at 20-year highs and is set to rise to 112.00
EUR/USD is falling after PMI data painted a bleak picture. The eurozone composite PMI fell more than expected to 48.2 in September, down from 48.9 in August. The data suggests that the eurozone could already be in recession.
GBPUSD plunges after the Chancellor’s mini budget. Far from soothing concerns over the outlook for the UK economy, Liz Truss and Kwasi Kwarteng’s economic plan for the UK has sent the pound plunging. The announcement of the largest tax cuts since 1972 to boost growth and stave off a recession that has already started has triggered a crash in the pound and the bond market.
The sell-off in UK assets reflects the sheer panic as the new government’s stimulus package will not only grow an already sizeable debt burden, potentially to unmanageable levels but will also add to inflationary pressures.
The BoE, which has been reluctant to hike rates aggressively, will need to roll up its sleeves and fight inflation with larger rate hikes. Expectations for a 1% hike in November are already climbing.
It’s difficult to see how the pound can recover from here. Investors are rapidly pulling out of UK assets, and who can blame them? Drawing comparisons historically, the last big tax giveaway in 1972 resulted in rampant inflation, unmanageable debt, and an IMF bailout.
Suddenly pound parity with the USD looks increasingly likely.
GBP/USD -2% at 1.1056
EUR/USD -0.85% at 0.9750
Oil falls 3%
Oil prices are tumbling lower as recession fears grip the market and the USD marches higher. With central banks across the globe hiking rates, fears of a recession are hurting the demand outlook for oil. Quite simply, slower growth means weaker oil demand.
The downside could be capped by heightened tensions as Russian mobilizes more troops to support the ongoing war in Ukraine. Following Putin’s latest threats, the EU is rushing to agree on an oil price cap. The cap could hit Moscow’s revenue which is helping to fund the war.
WTI crude trades -3% at $80.81
Brent trades -2.7% at $87.1
Learn more about trading oil here.
Looking ahead
14:45 US PMI data
18:00 Baker Hughes
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.