



US open: Stocks drop as JP Morgan profits fall, jobless claims rise
Hot inflation, aggressive Fed bets, rising jobless claims and JPM misses - all in al there is very little to be optimistic about. Stocks are falling, USD is rising.
Share this:

US futures
Dow futures -1.65% at 30312
S&P futures -1.35% at 3747
Nasdaq futures -1% at 11613
In Europe
FTSE -1.2% at 7070
Dax -1.3% at 12590
Euro Stoxx -1.38% at 3411
JP Morgan misses forecasts
US stocks are heading for a weaker open as investors digest a disappointing start to earnings season and the prospect of a more aggressive Federal Reserve.
Stocks closed modestly lower yesterday after US CPPI rose by more than expected to 9.1%. However, as the dust settles on the higher-than-expected print, worries of rampant inflation have meant that the market has reassessed expectations for rate hikes in both July and September. The market is now pricing in an 85% probability of a 1% rise in July, and a 0.75% hike in September is considered more likely than a 0.5% rise.
The Fed is so concerned about surging prices that pushing the US economy into a recession ASAP is preferable to entrenched inflation, which is quickly becoming a very real risk.
PPI data today unexpectedly rose to 11.3%, up from 10.9% and defying expectations of a fall to 10.8%. Rising PPI suggests that it is still premature to be talking about passing peak inflation.
After the jobs market has shown resilience in the face of mounting recession fears, the rise in jobless is becoming a trend. Initial claims rose 244k, up from 235k. Weakness is creeping into the labour market.
In corporate news:
JP Morgan has kicked off earnings season in a disappointing manner. The banked saw profits fall 28% in Q2 after setting aside $1.1 billion in bad loan reserves. In the same period last year the bank released $3 billion from reserves. The bank has also suspended its share buyback program after missing estimates.
Where next for the Nasdaq?
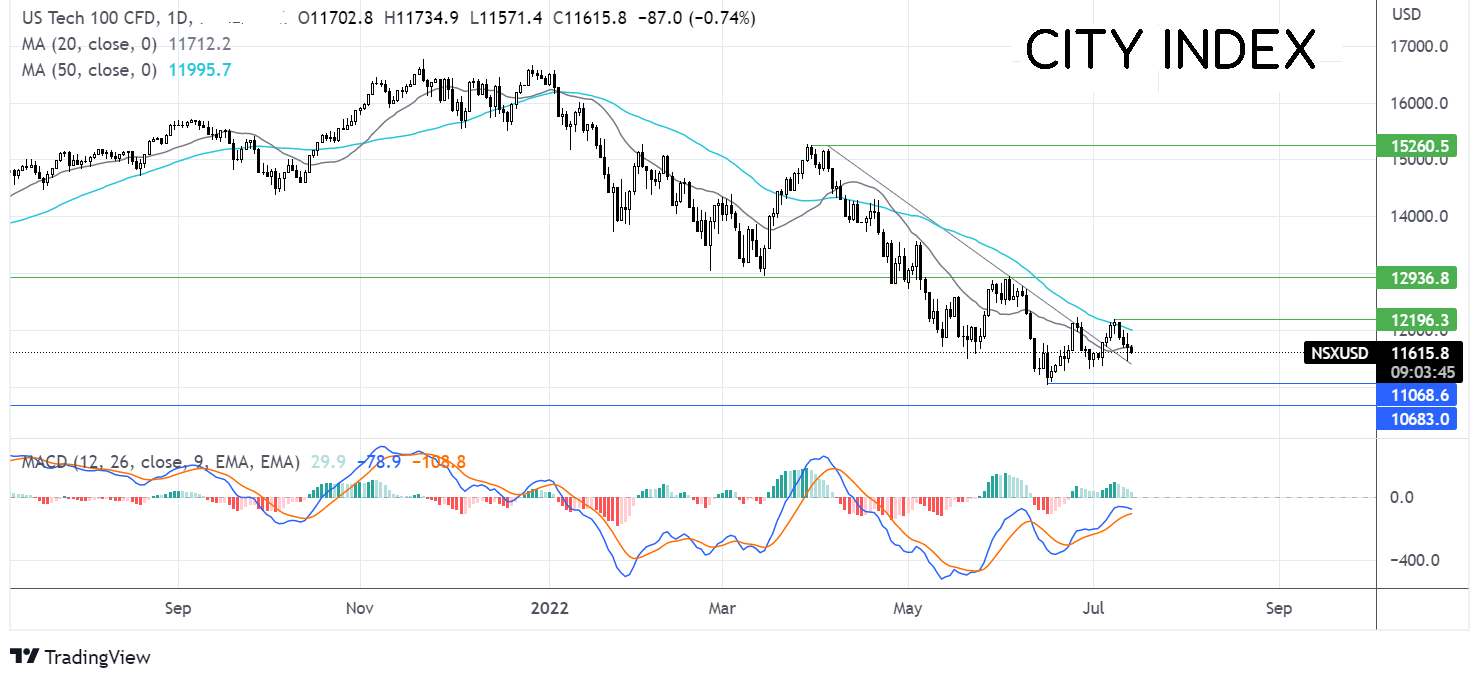
The Nasdaq has rebounded off the 11085 the 2022 low before running into resistance at 12100 the 50 sma. The index is falling lower below the 20 sma, which, combined with the receding bearish bias on the MACD, keeps sellers hopeful of further downside. Sellers will look for a move below horizontal support at 11350, opening the door to 11085, with a move below here creating a lower low. Buyers will look for a move back over the 209 sma at 11740 to expose the 50 sma at 12000 and 12200, the July high.

FX markets – USD rises, EUR back to parity.
USD is soaring higher as expectations for more aggressive Federal Reserve rate hikes grow, lifting the USD versus major peers as central bank divergence ramps up.
EURUSD has fallen back to parity on USD strength, paring gains from earlier in the day. The ECB is expected to raise interest rates by 25 bps next week, well short of the 100 bpds that the Fed could now hike in July.
USD/CAD trades over 1.31 as the market shrugs off the BoC’s surprise 1% rate hikes and as the loonie tracks oil prices lower. The shock move by the BoC highlights how concerned policymakers are over surging inflation becoming entrenched.
USD/CAD +1.3% at 1.3133
EUR/USD -0.5% at 1.0005
Oil tumbles towards $90
Oil prices are falling on a deteriorating demand outlook. After red hot inflation figures mean recession fears have risen considerably, hurting the demand outlook. This, combined with a large build in crude inventories owing to the release of strategic reserves, has pulled oil prices to a level last seen at the start of the Russian invasion into Ukraine at the end of February.
Demand concerns are the big driving force behind the fall. Supply remains an issue; the world is still struggling to produce the amount of oil needed.
WTI crude trades -2.7% at $91.70
Brent trades -2.94% at $95.70
Looking ahead
16:00 Fed Waller speech
US futures
Dow futures -1.65% at 30312
S&P futures -1.35% at 3747
Nasdaq futures -1% at 11613
In Europe
FTSE -1.2% at 7070
Dax -1.3% at 12590
Euro Stoxx -1.38% at 3411
Learn more about trading indices
JP Morgan misses forecasts
US stocks are heading for a weaker open as investors digest a disappointing start to earnings season and the prospect of a more aggressive Federal Reserve.
Stocks closed modestly lower yesterday after US CPPI rose by more than expected to 9.1%. However, as the dust settles on the higher-than-expected print, worries of rampant inflation have meant that the market has reassessed expectations for rate hikes in both July and September. The market is now pricing in an 85% probability of a 1% rise in July, and a 0.75% hike in September is considered more likely than a 0.5% rise.
The Fed is so concerned about surging prices that pushing the US economy into a recession ASAP is preferable to entrenched inflation, which is quickly becoming a very real risk.
PPI data today unexpectedly rose to 11.3%, up from 10.9% and defying expectations of a fall to 10.8%. Rising PPI suggests that it is still premature to be talking about passing peak inflation.
After the jobs market has shown resilience in the face of mounting recession fears, the rise in jobless is becoming a trend. Initial claims rose 244k, up from 235k. Weakness is creeping into the labour market.
In corporate news:
JP Morgan has kicked off earnings season in a disappointing manner. The banked saw profits fall 28% in Q2 after setting aside $1.1 billion in bad loan reserves. In the same period last year the bank released $3 billion from reserves. The bank has also suspended its share buyback program after missing estimates.
Where next for the Nasdaq?
The Nasdaq has rebounded off the 11085 the 2022 low before running into resistance at 12100 the 50 sma. The index is falling lower below the 20 sma, which, combined with the receding bearish bias on the MACD, keeps sellers hopeful of further downside. Sellers will look for a move below horizontal support at 11350, opening the door to 11085, with a move below here creating a lower low. Buyers will look for a move back over the 209 sma at 11740 to expose the 50 sma at 12000 and 12200, the July high.
FX markets – USD rises, EUR back to parity.
USD is soaring higher as expectations for more aggressive Federal Reserve rate hikes grow, lifting the USD versus major peers as central bank divergence ramps up.
EURUSD has fallen back to parity on USD strength, paring gains from earlier in the day. The ECB is expected to raise interest rates by 25 bps next week, well short of the 100 bpds that the Fed could now hike in July.
USD/CAD trades over 1.31 as the market shrugs off the BoC’s surprise 1% rate hikes and as the loonie tracks oil prices lower. The shock move by the BoC highlights how concerned policymakers are over surging inflation becoming entrenched.
USD/CAD +1.3% at 1.3133
EUR/USD -0.5% at 1.0005
Oil tumbles towards $90
Oil prices are falling on a deteriorating demand outlook. After red hot inflation figures mean recession fears have risen considerably, hurting the demand outlook. This, combined with a large build in crude inventories owing to the release of strategic reserves, has pulled oil prices to a level last seen at the start of the Russian invasion into Ukraine at the end of February.
Demand concerns are the big driving force behind the fall. Supply remains an issue; the world is still struggling to produce the amount of oil needed.
WTI crude trades -2.7% at $91.70
Brent trades -2.94% at $95.70
Learn more about trading oil here.
Looking ahead
16:00 Fed Waller speech
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.