



US open: Stocks fall on weaker retail sales, mixed banks earnings
Stocks fall after US retail sales miss and banks kick off earnings season.
Share this:

US futures
Dow futures -0.5% at 28750
S&P futures -1% at 3500
Nasdaq futures -1.7% at 10480
In Europe
FTSE +0.4% at 6726
Dax +0.8% at 12043
Retail sales miss, banks mixed
US stocks are falling as investors digest mixed bank’s earnings and weaker-than-forecast retail sales data.
Retail sales stalled in September at 0%, after rising an upwardly revised 0.4% MoM in August. Expectations had been for sales to rise 0.2%. The stagnation in retail sales suggests that the consumer, which has been remarkedly resilient until now, is starting to be hit by persistently high inflation levels. Seven of 13 categories saw a fall in sales, and petrol station sales also fell owing to cheaper fuel. Consumers are definitely feeling the pint from higher prices and rising interest rates. This is going to get worse before it gets better.
The selloff comes after yesterday’s rally left many traders scratching their head. Such a strong rally after dire inflation data seemed illogical. In light of today’s move yesterday’s rally looks like nothing more than a squeeze ahead of further lows.
Corporate news:
Banks are in focus with Citigroup, JP Morgan, and Wells Fargo rising after earnings but Morgan Stanley falls after a stark fall in investment banking activities.
Citigroup beast forecasts for both the top and bottom line with EPS of $1.63 on revenue of $18.5 billion. Expectations had been for EPS of $1.42 on revenue of $18.3 billion.
Where next for S&P500?
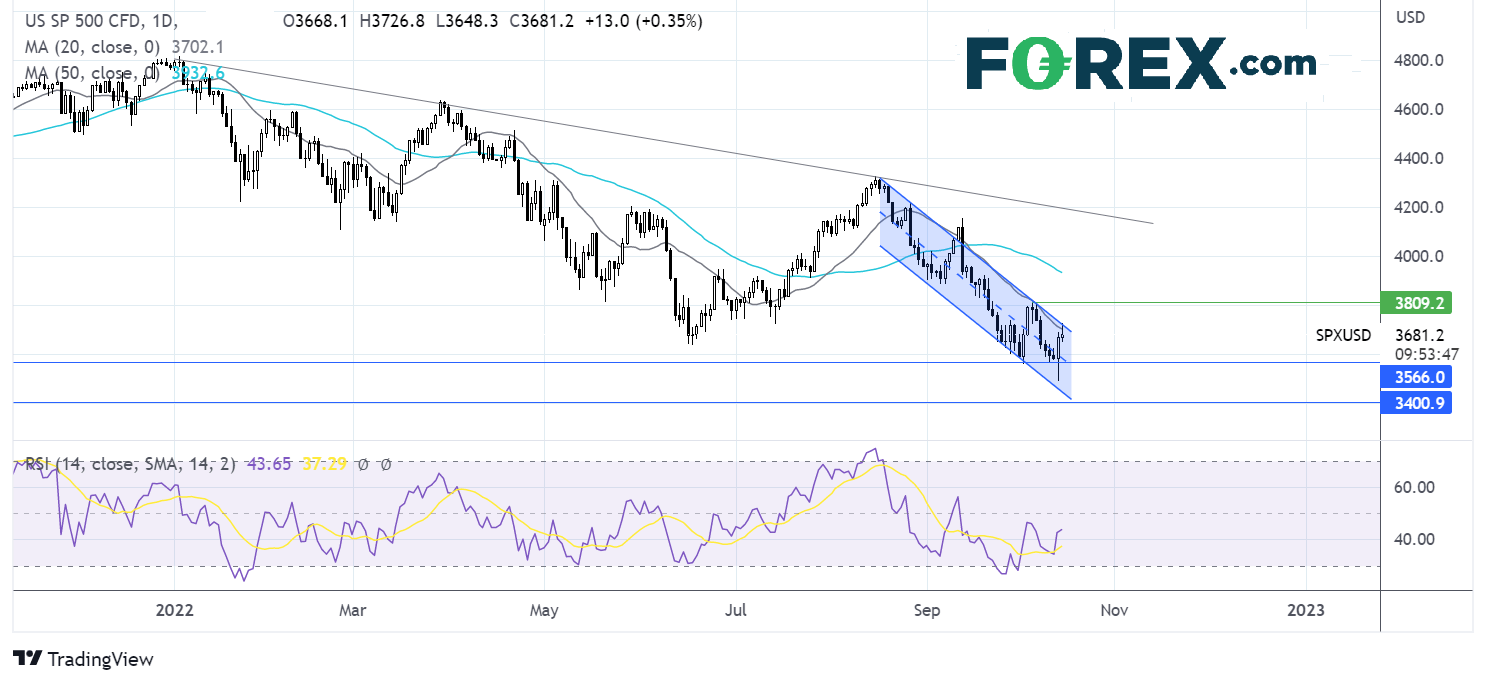
The S&P500 continues to trade in a falling channel, in place since mid-August. The move below 3600 round number and the RSI below 50 keeps seller’s hopeful of further downside. Support can be seen at 3490 the lower band of the falling channel, a break below here opens the door to 3390 the February 2020 high. On the flip side, a move the 20 sma at 3707, which is also the upper band of the falling channel, opens the door to 3800, the October high. A move over here creates a higher high and exposes the 50 sma at 3936.
FX markets – USD rises, GBP drops
The USD is rising following US retail sales and following losses in the previous session. The USD fell versus major peers despite the hotter-than-expected inflation report.
EUR/USD is falling on USD strength and as German recession risks weigh. ECB’s Lagarde said that the central bank is expecting to raise rates over the next several meetings.
GBPUSD is tanking lower as political instability knocks confidence and as doubts emerge over whether the expected U-turn will go far enough. With an announcement due later today, the market is front guessing that corporation tax will be backtracked. Whilst this is a step in the right direction, it may not be sufficient to stem the sell-off in the gilts market, especially without the BoE’s support. The sacking of the Chancellor and the likelihood of a humiliating U-turn for Truss also raises questions about her ability to hold onto power; more political instability is the last thing the pound needs right now.
GBP/USD -1.5% at 1.1210
EUR/USD -0.4% at 0.9660
Oil steadies after three days of losses
Oil prices are falling lower as recession fears continue to rise, but supply cuts limit losses. Hotter-than-forecast inflation and rising COVID cases in China are raising the likelihood of a recession, which is hitting the demand outlook.
The IEA and OPEC both cut its oil demand forecast amid warnings of a potential global recession.
WTI crude trades -0.6% at $88.70
Brent trades -0.6% at $94.50
Looking ahead
N/A
US futures
Dow futures -0.5% at 28750
S&P futures -1% at 3500
Nasdaq futures -1.7% at 10480
In Europe
FTSE +0.4% at 6726
Dax +0.8% at 12043
Learn more about trading indices
Retail sales miss, banks mixed
US stocks are falling as investors digest mixed bank’s earnings and weaker-than-forecast retail sales data.
Retail sales stalled in September at 0%, after rising an upwardly revised 0.4% MoM in August. Expectations had been for sales to rise 0.2%. The stagnation in retail sales suggests that the consumer, which has been remarkedly resilient until now, is starting to be hit by persistently high inflation levels. Seven of 13 categories saw a fall in sales, and petrol station sales also fell owing to cheaper fuel. Consumers are definitely feeling the pint from higher prices and rising interest rates. This is going to get worse before it gets better.
The selloff comes after yesterday’s rally left many traders scratching their head. Such a strong rally after dire inflation data seemed illogical. In light of today’s move yesterday’s rally looks like nothing more than a squeeze ahead of further lows.
Corporate news:
Banks are in focus with Citigroup, JP Morgan, and Wells Fargo rising after earnings but Morgan Stanley falls after a stark fall in investment banking activities.
Citigroup beast forecasts for both the top and bottom line with EPS of $1.63 on revenue of $18.5 billion. Expectations had been for EPS of $1.42 on revenue of $18.3 billion.
Where next for S&P500?
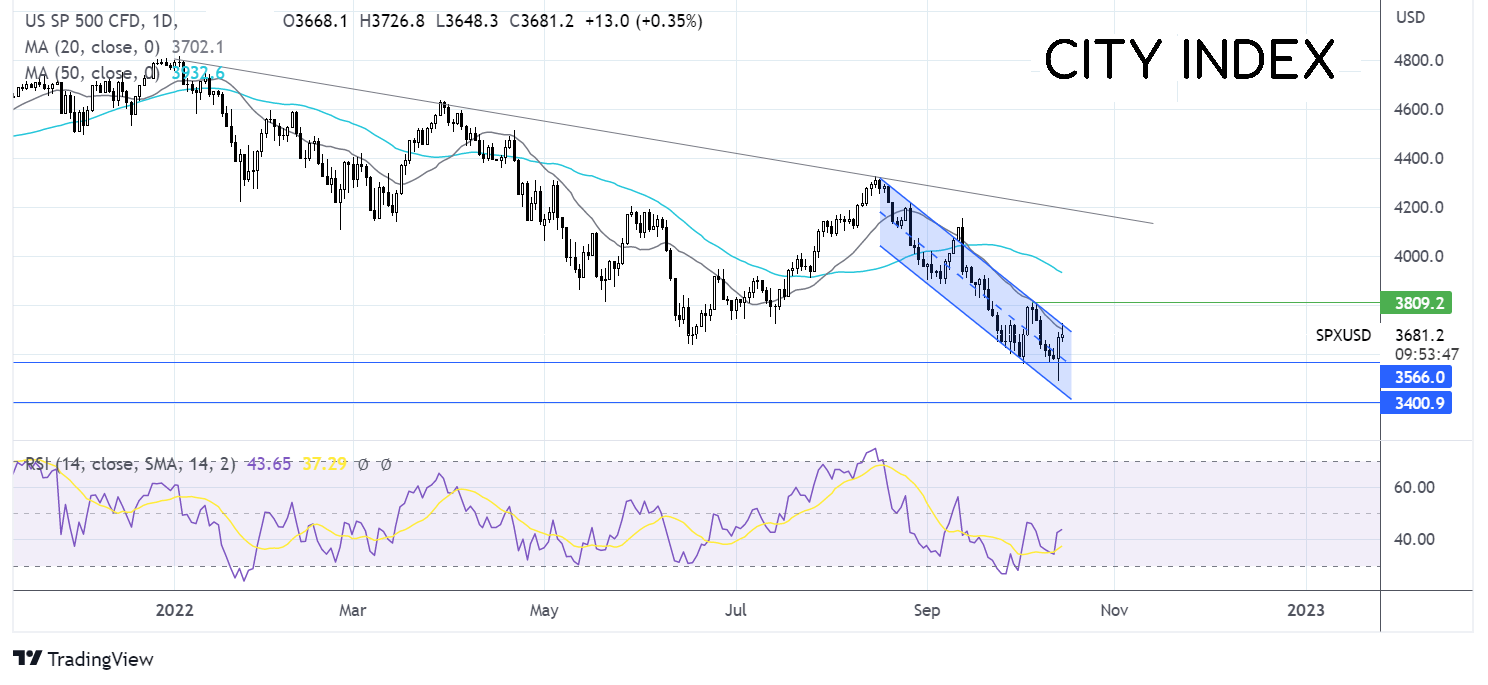
The S&P500 continues to trade in a falling channel, in place since mid-August. The move below 3600 round number and the RSI below 50 keeps seller’s hopeful of further downside. Support can be seen at 3490 the lower band of the falling channel, a break below here opens the door to 3390 the February 2020 high. On the flip side, a move the 20 sma at 3707, which is also the upper band of the falling channel, opens the door to 3800, the October high. A move over here creates a higher high and exposes the 50 sma at 3936.
FX markets – USD rises, GBP drops
The USD is rising following US retail sales and following losses in the previous session. The USD fell versus major peers despite the hotter-than-expected inflation report.
EUR/USD is falling on USD strength and as German recession risks weigh. ECB’s Lagarde said that the central bank is expecting to raise rates over the next several meetings.
GBPUSD is tanking lower as political instability knocks confidence and as doubts emerge over whether the expected U-turn will go far enough. With an announcement due later today, the market is front guessing that corporation tax will be backtracked. Whilst this is a step in the right direction, it may not be sufficient to stem the sell-off in the gilts market, especially without the BoE’s support. The sacking of the Chancellor and the likelihood of a humiliating U-turn for Truss also raises questions about her ability to hold onto power; more political instability is the last thing the pound needs right now.
GBP/USD -1.5% at 1.1210
EUR/USD -0.4% at 0.9660
Oil steadies after three days of losses
Oil prices are falling lower as recession fears continue to rise, but supply cuts limit losses. Hotter-than-forecast inflation and rising COVID cases in China are raising the likelihood of a recession, which is hitting the demand outlook.
The IEA and OPEC both cut its oil demand forecast amid warnings of a potential global recession.
WTI crude trades -0.6% at $88.70
Brent trades -0.6% at $94.50
Learn more about trading oil here.
Looking ahead
N/A
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.