



US open: Stocks reverse after stronger doubt raises doubts over the Fed
Stocks reverse lower after upbeat jobs data and manufacturing data raises doubts over whether the Fed will tone down its aggressively hawkish stance.
Share this:

US futures
Dow futures -0.15% at 32677
S&P futures -0.6% at 3875
Nasdaq futures -0.04% at 11463
In Europe
FTSE +1.28% at 7060
Dax +0.72% at 13274
Job openings & ISM manufacturing beat forecasts
US stocks pared early gains as investors continue to weigh up the prospect of the Federal Reserve starting to tone down its aggressively hawkish stance and slow the pace of rate hikes as the two-day FOMC begins.
Another 25-basis point rate hike from the RBA revived bets that the Fed could follow suit. However, stronger-than-expected US data has raised doubts over whether the Fed will be ready to soften its stance. And let’s not forget that core inflation is still rising and US GDP rebounded more strongly than forecast in Q3.
The housing market is showing signs of cooling and the ISM manufacturing PMI also grew at a slower pace in October at 50.2, down from 50.9 in September, although this was still ahead of the 50 level expected and the level which separates expansion from contraction.
Meanwhile, the JOLTS job vacancies data highlighted just how tight the labour market remains, with the number of vacancies increasing 10 10.7 million, up from an upwardly revised 10.28 million and still well ahead of the 10 million forecast. A tight labour market, could keep upward pressure on wages
Corporate news:
UBER jumps 14% despite missing profit forecasts. The ride-hailing app reported a wider-than-expected loss of $0.61 vs $0.18 forecast. Revenue was ahead of estimates at $89.3 billion. Q4 guidance was encouraging, and Goldman Sachs’s comments boosted the stock further.
Pfizer trades 4% higher after better-than-expected results and guidance. Pfizer reported EPS of $1.78 on revenue of $22.64 billion, beating forecasts of $1.44 on $21.33 billion revenue. The COVID vaccine generated $4.4 billion in revenue, ahead of forecasts.
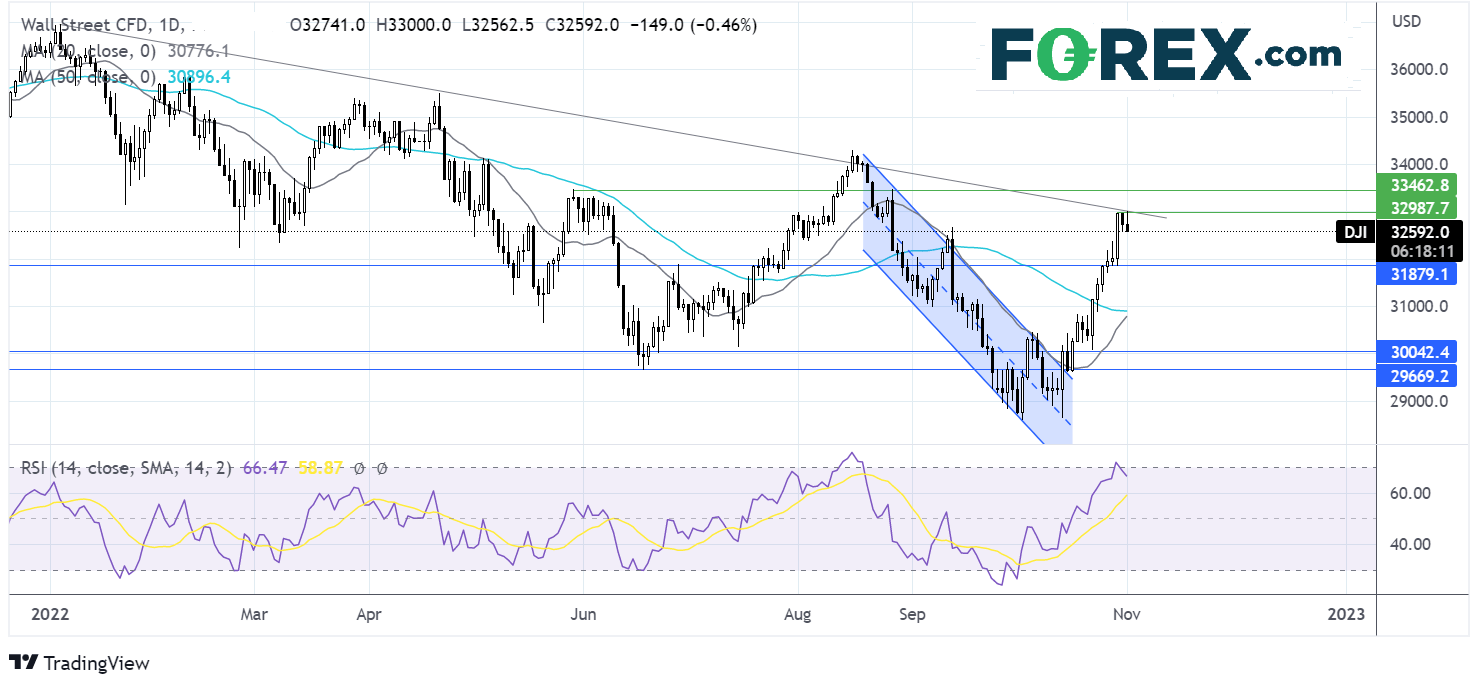
Where next for the Dow Jones?
FX markets – USD falls, GBP rises
The USD is falling as investors continue to weigh up the Fed’s next move. The smaller hike by the RBA of 25 basis points is helping to fuel bets that the Fed could hike at a slower pace after the November meeting.
EURUSD is rising amid a risk on mood in the market. There is no high-impacting eurozone data today. Investors continue to digest record-high inflation, which will pile pressure on the ECB to hike rates aggressively, even as growth slows.
GBPUSD is rising as investors look ahead to the BoE rate announcement tomorrow. The market is broadly expecting a 75 basis point hike, this had climbed to 100 basis points amid the chaos of Truss’ expansionary budget. Now that Rishi Sunak has taken over leading the country, an element of calm has helped the Gilt market and the pound calm. Even so, with inflation at 10%, the market is expecting the BoE to act big, even if past hikes tell us that the BoE is far from comfortable with a jumbo sized hike. Today the BoE will kick start the QT programme.
GBP/USD -0.7% at 1.1520
EUR/USD -0.47% at 0.9920
Oil falls after weak China factory data
Oil prices are rising, paring losses from the previous session. OPEC+ upwardly revising the medium-term demand outlook, and the weaker USD is helping oil prices rise. Meanwhile, more COVID restrictions in China are limiting gains in oil as well as US oil output climbing to 12 million bpd in August.
Looking ahead, API oil stockpiles data will be released and is expected to show
WTI crude trades +1.92% at $85.70
Brent trades +1.83% at $92.56.
Looking ahead
N/A
US futures
Dow futures -0.15% at 32677
S&P futures -0.6% at 3875
Nasdaq futures -0.04% at 11463
In Europe
FTSE +1.28% at 7060
Dax +0.72% at 13274
Learn more about trading indices
Job openings & ISM manufacturing beat forecasts
US stocks pared early gains as investors continue to weigh up the prospect of the Federal Reserve starting to tone down its aggressively hawkish stance and slow the pace of rate hikes as the two-day FOMC begins.
Another 25-basis point rate hike from the RBA revived bets that the Fed could follow suit. However, stronger-than-expected US data has raised doubts over whether the Fed will be ready to soften its stance. And let’s not forget that core inflation is still rising and US GDP rebounded more strongly than forecast in Q3.
The housing market is showing signs of cooling and the ISM manufacturing PMI also grew at a slower pace in October at 50.2, down from 50.9 in September, although this was still ahead of the 50 level expected and the level which separates expansion from contraction.
Meanwhile, the JOLTS job vacancies data highlighted just how tight the labour market remains, with the number of vacancies increasing 10 10.7 million, up from an upwardly revised 10.28 million and still well ahead of the 10 million forecast. A tight labour market, could keep upward pressure on wages
Corporate news:
UBER jumps 14% despite missing profit forecasts. The ride-hailing app reported a wider-than-expected loss of $0.61 vs $0.18 forecast. Revenue was ahead of estimates at $89.3 billion. Q4 guidance was encouraging, and Goldman Sachs’s comments boosted the stock further.
Pfizer trades 4% higher after better-than-expected results and guidance. Pfizer reported EPS of $1.78 on revenue of $22.64 billion, beating forecasts of $1.44 on $21.33 billion revenue. The COVID vaccine generated $4.4 billion in revenue, ahead of forecasts.
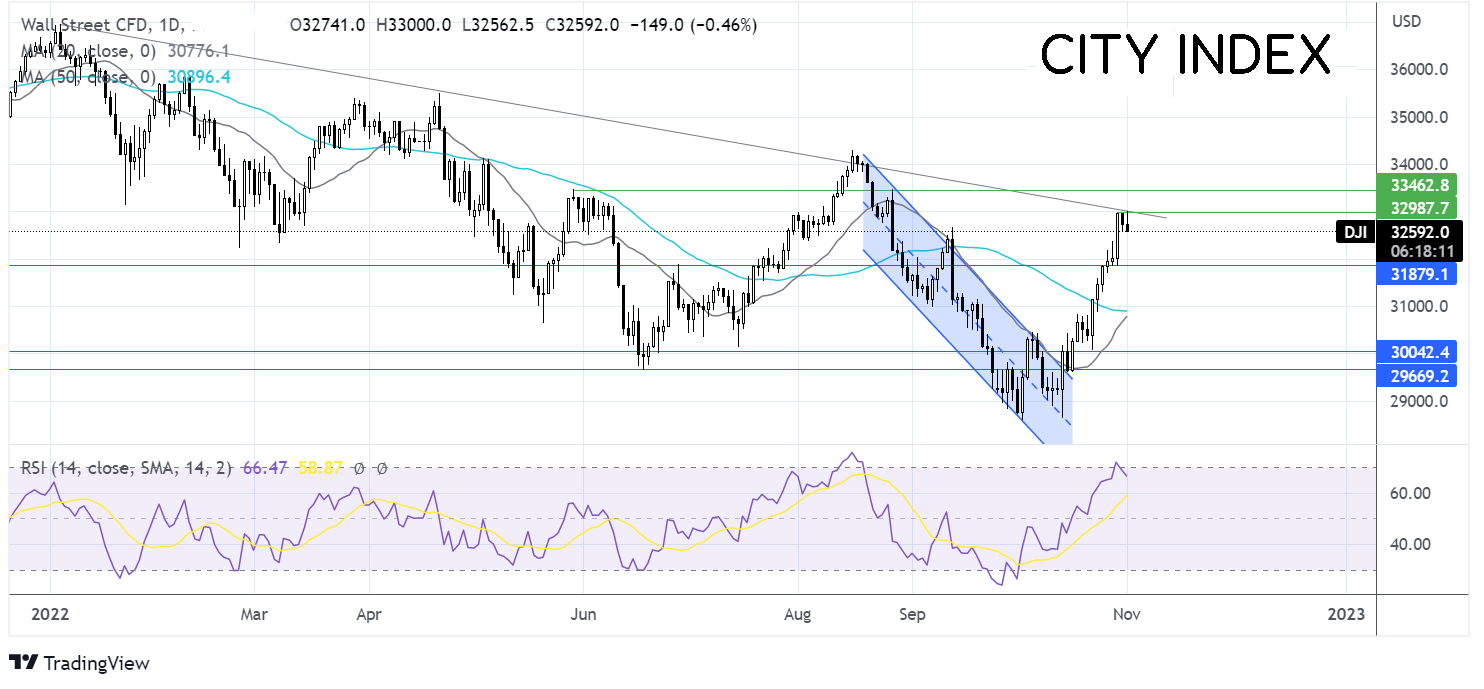
Where next for the Dow Jones?
FX markets – USD falls, GBP rises
The USD is falling as investors continue to weigh up the Fed’s next move. The smaller hike by the RBA of 25 basis points is helping to fuel bets that the Fed could hike at a slower pace after the November meeting.
EURUSD is rising amid a risk on mood in the market. There is no high-impacting eurozone data today. Investors continue to digest record-high inflation, which will pile pressure on the ECB to hike rates aggressively, even as growth slows.
GBPUSD is rising as investors look ahead to the BoE rate announcement tomorrow. The market is broadly expecting a 75 basis point hike, this had climbed to 100 basis points amid the chaos of Truss’ expansionary budget. Now that Rishi Sunak has taken over leading the country, an element of calm has helped the Gilt market and the pound calm. Even so, with inflation at 10%, the market is expecting the BoE to act big, even if past hikes tell us that the BoE is far from comfortable with a jumbo sized hike. Today the BoE will kick start the QT programme.
GBP/USD -0.7% at 1.1520
EUR/USD -0.47% at 0.9920
Oil falls after weak China factory data
Oil prices are rising, paring losses from the previous session. OPEC+ upwardly revising the medium-term demand outlook, and the weaker USD is helping oil prices rise. Meanwhile, more COVID restrictions in China are limiting gains in oil as well as US oil output climbing to 12 million bpd in August.
Looking ahead, API oil stockpiles data will be released and is expected to show
WTI crude trades +1.92% at $85.70
Brent trades +1.83% at $92.56.
Learn more about trading oil here.
Looking ahead
N/A
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.