



US open: Stocks rise as weaker data is seen as good news
Stocks rise after weaker than expected ADP payroll data sees aggressive Fed bets ease, lifting stocks. Oil prices also extend the selloff.
Share this:

US futures
Dow futures +0.32% at 31850
S&P futures +0.5% at 4005
Nasdaq futures +0.83% at 12450
In Europe
FTSE -0.94% at 73283
Dax +0.2% at 12960
Euro Stoxx -1.7% at 3670
Stocks rise as aggressive Fed bets ease
US stocks are pointing higher after weaker than expected ADP payroll figures. The market is sticking with the mantra that weak data is good news and vice versa.
ADP payroll data showed that just 132k, jobs were added in August well below the 288k forecast and roughly in line with July’s 128k. The data suggests that the labour market is starting to cool.
The stock market is working off the basis that weak data could soften the resolve of the Fed the hike rates aggressive. Meanwhile, strong data is bad news for stocks as it paves the way for a more aggressive Federal Reserve.
Still, the mood in the market remains cautious after a strong selloff in the previous session after both US consumer confidence and JOLTS jobs openings beat forecasts, fueling Fed rate hike fears.
The conflicting data shows just how tough it is to draw conclusions about the health of the economy and determine where the Federal Reserve is heading as far as a soft or hard landing is concerned.
Attention is firmly on Friday’s non-farm payroll report for further insight.
Corporate news:
Chewy drops 12% after Q2 sales and full-year guidance disappointed. Customers are reining in spending as inflation rises. EPS was $0.05, ahead of forecasts of a $0.12 loss. Revenue was $2.43 billion, missing estimates of $2.45 billion.
SNAP dropped 8% on reports that two senior management members were moving to Netflix and on reports that the firm will cut 20% of its workforce.
Where next for the NASDAQ?
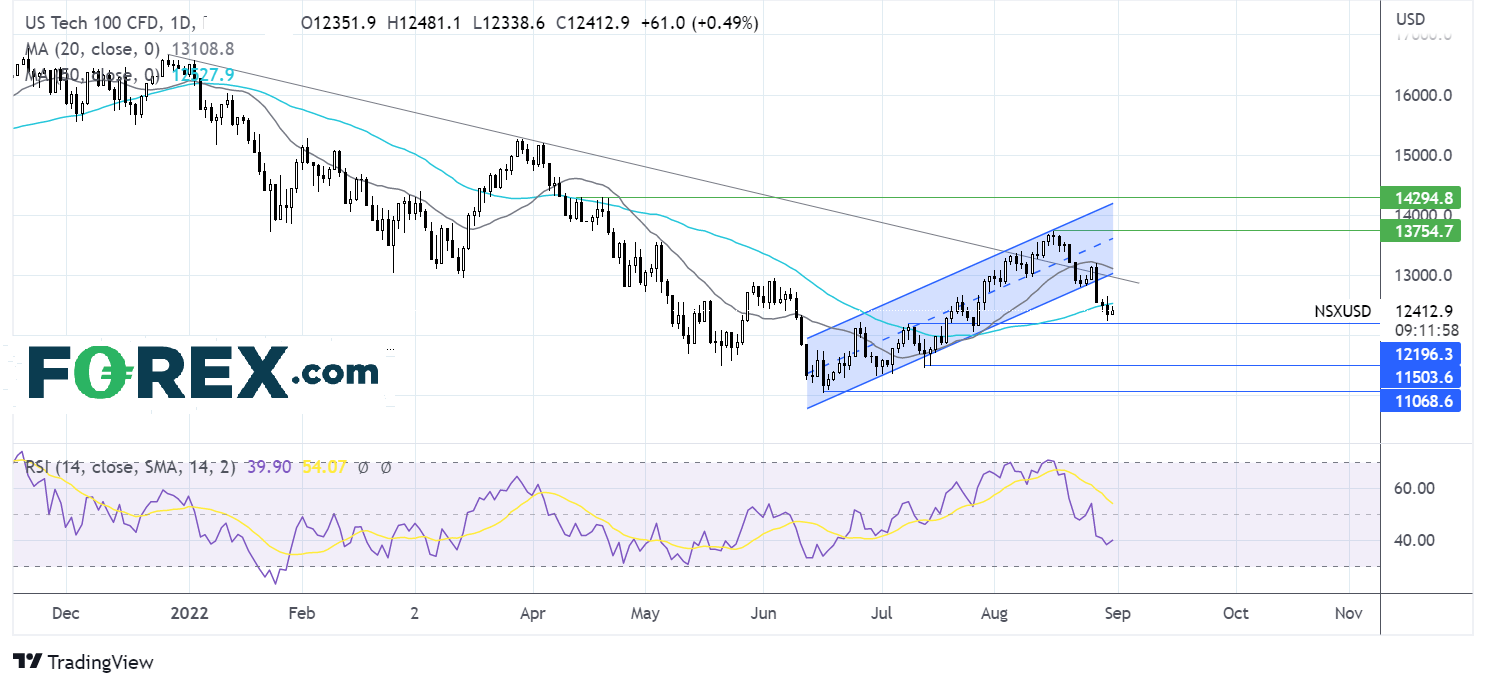
The Nasdaq has fallen below the multi-week rising channel, dropping below the 50 SMA to a low of 12200. The price has found support at this level, although the RSI supports further downside. Sellers look for a fall below 12200 to extend the bearish trend towards 11500, the July 14 low, and 11100, the 2022 low. Buyers will look for a rise over the 50 sma at 12550 to target 1300, the lower band of the rising channel, the psychological level, which could prove a tough nut to crack.
FX markets – USD rises, GBP drops
The USD is heading higher against its major peers. Stronger than forecast consumer confidence and JOLTS job openings pave the way for more large rate hikes from the Fed.
EUR/USD is falling after eurozone inflation rose to a record high of 9.1% YoY, up from 8.9%. The data piles pressure on the ECB to raise interest rates by a larger 75 basis points. However, as recession fears build, the ECB could be inclined to stick with a 50-basis point hike. Gas flows from Russia along the Nord Stream 1 pipeline turn off today for 3-days.
GBP/USD is falling amid rising concerns over the deepening energy crisis, lifting recession fears. GBP/USD is set for its worst month since 2016 as inflation gathers pace, the UK economy slows, and investors rush to put their money elsewhere. GBP/USD trades down 4.4% this month.
Oil falls a further 3%
Oil prices are heading lower for a second straight day. Oil has lost around 8% over the past 36 hours and is heading for a third consecutive month of losses, marking the longest losing run in over two years.
As central banks raise interest rates, the prospect of slower growth is hurting the demand outlook. At the same time, economic weakness in China, due to its strict COVID strategy, is also hurting the demand outlook.
On the supply side, reports that the US and Iran have agreed on the nuclear deal revival hit oil prices yesterday, although these reports remain unconfirmed. Should a deal be agreed, Iranian oil sanctions could be lifted, resulting in around 1.3 million barrels a day returning to the market.
Saudi Arabia has floated the idea of cutting oil output. The next OPEC+ meeting is on September 5th.
EIA stockpile data is due later today.
WTI crude trades -2.9% at $88.96
Brent trades -3% at $95.15
Looking ahead
N/A
US futures
Dow futures +0.32% at 31850
S&P futures +0.5% at 4005
Nasdaq futures +0.83% at 12450
In Europe
FTSE -0.94% at 73283
Dax +0.2% at 12960
Euro Stoxx -1.7% at 3670
Learn more about trading indices
Stocks rise as aggressive Fed bets ease
US stocks are pointing higher after weaker than expected ADP payroll figures. The market is sticking with the mantra that weak data is good news and vice versa.
ADP payroll data showed that just 132k, jobs were added in August well below the 288k forecast and roughly in line with July’s 128k. The data suggests that the labour market is starting to cool.
The stock market is working off the basis that weak data could soften the resolve of the Fed the hike rates aggressive. Meanwhile, strong data is bad news for stocks as it paves the way for a more aggressive Federal Reserve.
Still, the mood in the market remains cautious after a strong selloff in the previous session after both US consumer confidence and JOLTS jobs openings beat forecasts, fueling Fed rate hike fears.
The conflicting data shows just how tough it is to draw conclusions about the health of the economy and determine where the Federal Reserve is heading as far as a soft or hard landing is concerned.
Attention is firmly on Friday’s non-farm payroll report for further insight.
Corporate news:
Chewy drops 12% after Q2 sales and full-year guidance disappointed. Customers are reining in spending as inflation rises. EPS was $0.05, ahead of forecasts of a $0.12 loss. Revenue was $2.43 billion, missing estimates of $2.45 billion.
SNAP dropped 8% on reports that two senior management members were moving to Netflix and on reports that the firm will cut 20% of its workforce.
Where next for the NASDAQ?
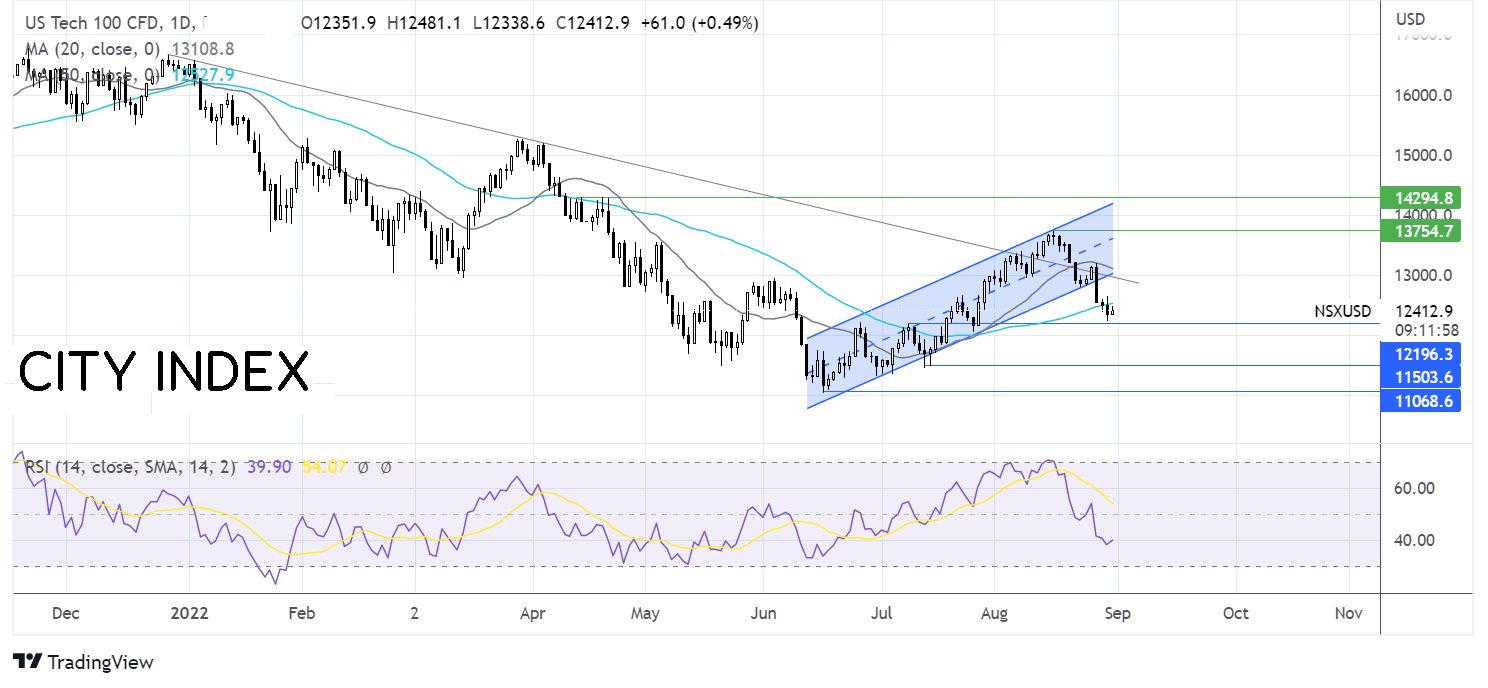
The Nasdaq has fallen below the multi-week rising channel, dropping below the 50 SMA to a low of 12200. The price has found support at this level, although the RSI supports further downside. Sellers look for a fall below 12200 to extend the bearish trend towards 11500, the July 14 low, and 11100, the 2022 low. Buyers will look for a rise over the 50 sma at 12550 to target 1300, the lower band of the rising channel, the psychological level, which could prove a tough nut to crack.
FX markets – USD rises, GBP drops
The USD is heading higher against its major peers. Stronger than forecast consumer confidence and JOLTS job openings pave the way for more large rate hikes from the Fed.
EUR/USD is falling after eurozone inflation rose to a record high of 9.1% YoY, up from 8.9%. The data piles pressure on the ECB to raise interest rates by a larger 75 basis points. However, as recession fears build, the ECB could be inclined to stick with a 50-basis point hike. Gas flows from Russia along the Nord Stream 1 pipeline turn off today for 3-days.
GBP/USD is falling amid rising concerns over the deepening energy crisis, lifting recession fears. GBP/USD is set for its worst month since 2016 as inflation gathers pace, the UK economy slows, and investors rush to put their money elsewhere. GBP/USD trades down 4.4% this month.
Oil falls a further 3%
Oil prices are heading lower for a second straight day. Oil has lost around 8% over the past 36 hours and is heading for a third consecutive month of losses, marking the longest losing run in over two years.
As central banks raise interest rates, the prospect of slower growth is hurting the demand outlook. At the same time, economic weakness in China, due to its strict COVID strategy, is also hurting the demand outlook.
On the supply side, reports that the US and Iran have agreed on the nuclear deal revival hit oil prices yesterday, although these reports remain unconfirmed. Should a deal be agreed, Iranian oil sanctions could be lifted, resulting in around 1.3 million barrels a day returning to the market.
Saudi Arabia has floated the idea of cutting oil output. The next OPEC+ meeting is on September 5th.
EIA stockpile data is due later today.
WTI crude trades -2.9% at $88.96
Brent trades -3% at $95.15
Learn more about trading oil here.
Looking ahead
15:00 US consumer sentiment
15:00 JOLTS job openings
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.