



US open: Stocks rise at the start of a busy week
US stocks push higher, extending gains from last week, as earnings stay in focus.
Share this:

US futures
Dow futures +0.72% at 31313
S&P futures +0.76% at 3777
Nasdaq futures +0.35% at 11310
In Europe
FTSE +0.7% at 7018
Dax +2.3% at 12982
Positive mood continues
US stocks are rising, extending gains from last week after a positive tone from major corporate earnings. The three major indices climbed 5% across the week.
Earnings have largely been positive, particularly in the banking sector. However, this week is likely to be the big test as around a third of S&P500 companies are due to report this week. Big tech will be in focus with the likes of Microsoft, Alphabet, Apple and Amazon due to report.
GDP Q3 data is also due to be released this week and is expected to show a rebound after two straight quarters of contraction.
Today attention will be on PMI data, which is expected to show that the composite PMI slipped further into contraction in October, falling to 49.1, down from 49.5 in September. The level 50 separates expansion from contraction.
Corporate news:
Tesla falls pre-market after the EVV maker cut starter prices of its Model 3 and Model Y cars by up to 9% in China amid signs of softening demand.
Oil stocks, which are also due to report this week, trade lower as oil prices fall.
Where next for the Nasdaq?
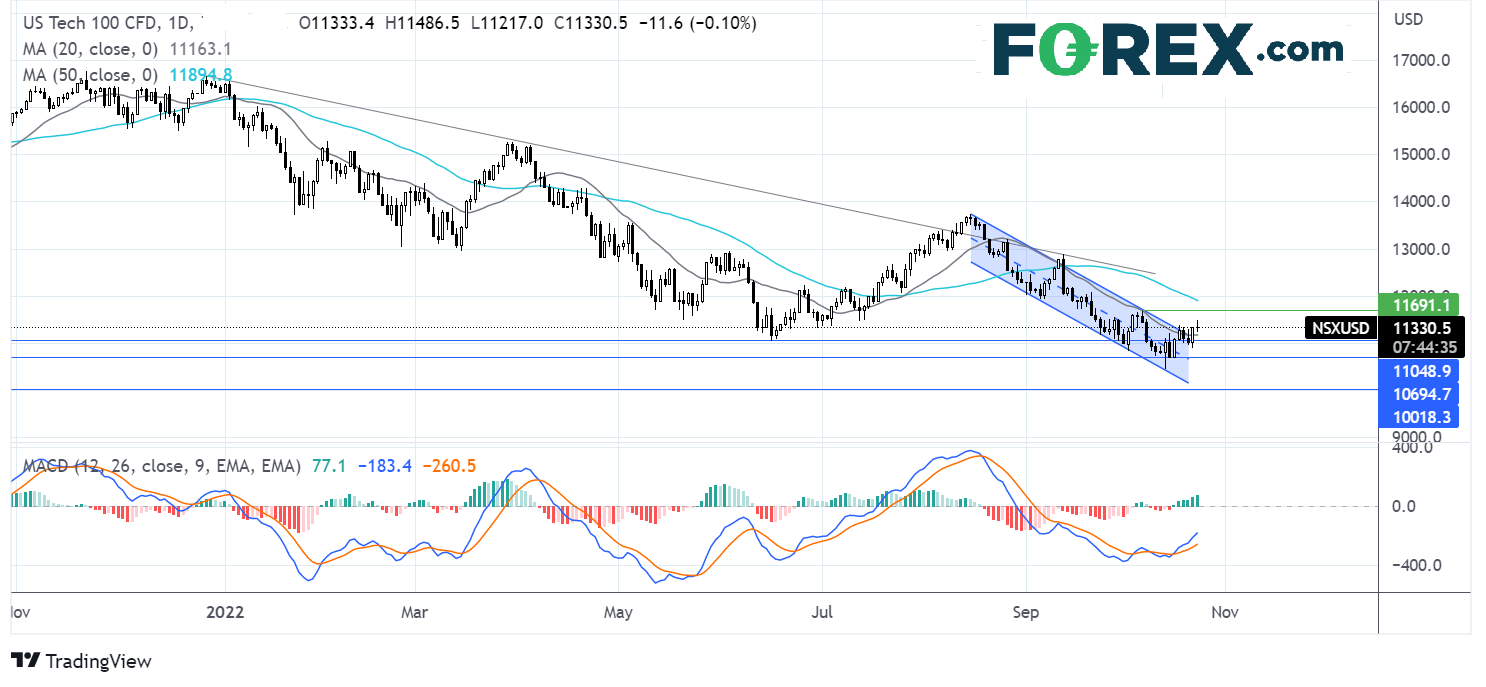
The Nasdaq pushed over the 20 sms and out of the falling channel and holds above support at 11,000 which combined with the bullish MACD keeps buyers hopeful of further upside. Bulls will now look for a break above 11700, the October high, ahead of the 50 sma at 11960. On the flip side, sellers will look for a fall below 11150 the 20 sma , which would take the price back into the falling channel, before bringing 10430 the 2022 low into focus.
FX markets – USD rises, GBP falls
The USD is rising after falling across last week. The US dollar index dropped 1.1% last week. However, today the greenback is doing well, clawing back those losses ahead of PMI data.
EUR/USD is falling after disappointing PMI s from the eurozone. The composite PMI fell by more than expected to 47.1 from 47.5 in October. This is down from 48.1 in September. The data indicates that the economy has fallen further into recessionary territory.
GBPUSD has pared earlier gains and is now trading mildly lower versus the USD as all eyes are on the leadership race. Rishi Sunak looks set to win, which had sent the pound higher earlier in the session given that he is considered the fiscally more prudent candidate and perhaps better experienced to handle the UK’s finances. Still, PMI data highlights the dire economic situation that the next PM will inherit.
GBP/USD -0.1% at 1.1285
EUR/USD -0.4% at 0.9820
Oil falls as China demand falters
Oil prices are falling amid concerns over demand levels from China. The world’s largest oil importer reported underwhelming demand in September as strict COVID policies and fuel export curbs kept demand depressed.
China’s crude oil imports of 9.79 million barrels a day were up from August, but still 2% levels seen this time last year.
Doubts remain over China’s economic recovery. While Q3 GDP data was stronger than forecast concerns over the strict zrio-COVID policy and the ongoing property crisis are undermining pro-growth measures.
WTI crude trades -1.4% at $83.90
Brent trades -1.03% at $90.70
Looking ahead
14:45 US composite PMI
US futures
Dow futures +0.72% at 31313
S&P futures +0.76% at 3777
Nasdaq futures +0.35% at 11310
In Europe
FTSE +0.7% at 7018
Dax +2.3% at 12982
Learn more about trading indices
Positive mood continues
US stocks are rising, extending gains from last week after a positive tone from major corporate earnings. The three major indices climbed 5% across the week.
Earnings have largely been positive, particularly in the banking sector. However, this week is likely to be the big test as around a third of S&P500 companies are due to report this week. Big tech will be in focus with the likes of Microsoft, Alphabet, Apple and Amazon due to report.
GDP Q3 data is also due to be released this week and is expected to show a rebound after two straight quarters of contraction.
Today attention will be on PMI data, which is expected to show that the composite PMI slipped further into contraction in October, falling to 49.1, down from 49.5 in September. The level 50 separates expansion from contraction.
Corporate news:
Tesla falls pre-market after the EVV maker cut starter prices of its Model 3 and Model Y cars by up to 9% in China amid signs of softening demand.
Oil stocks, which are also due to report this week, trade lower as oil prices fall.
Where next for the Nasdaq?
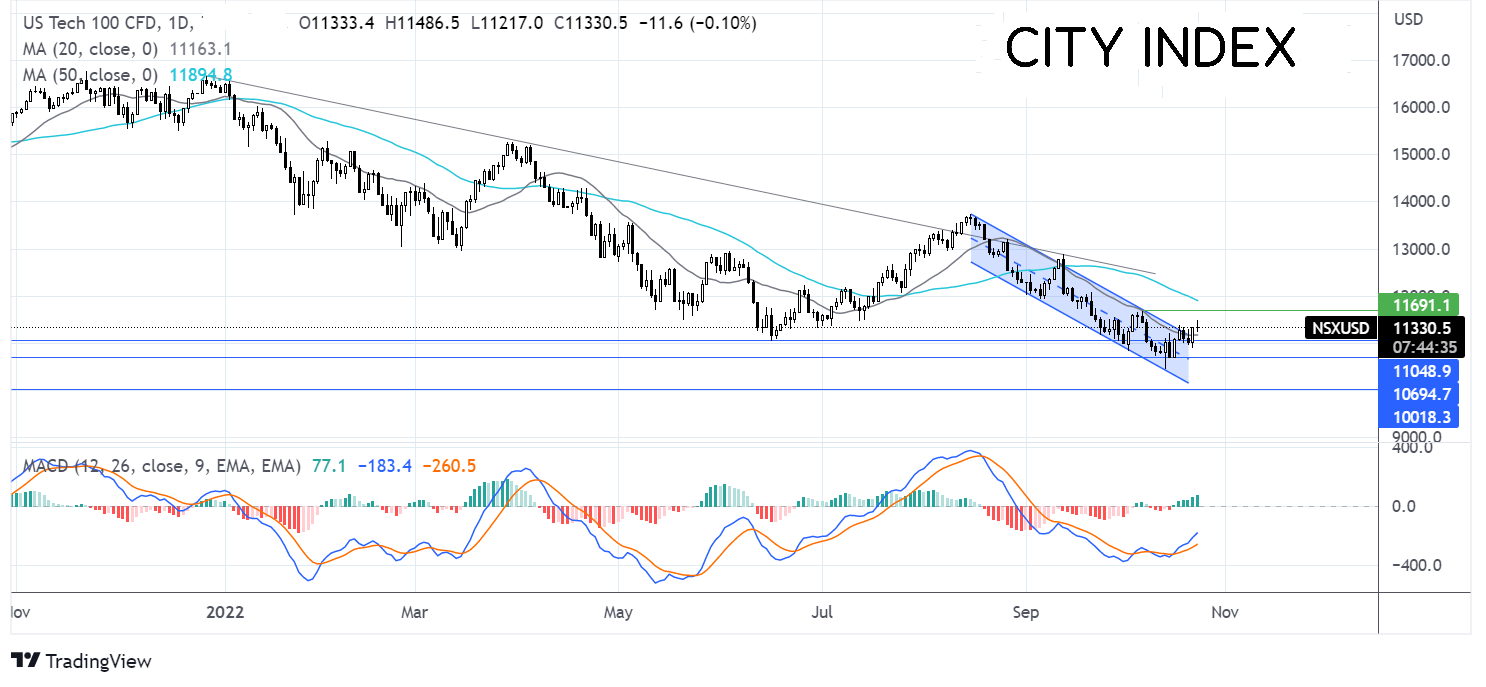
The Nasdaq pushed over the 20 sms and out of the falling channel and holds above support at 11,000 which combined with the bullish MACD keeps buyers hopeful of further upside. Bulls will now look for a break above 11700, the October high, ahead of the 50 sma at 11960. On the flip side, sellers will look for a fall below 11150 the 20 sma , which would take the price back into the falling channel, before bringing 10430 the 2022 low into focus.
FX markets – USD rises, GBP falls
The USD is rising after falling across last week. The US dollar index dropped 1.1% last week. However, today the greenback is doing well, clawing back those losses ahead of PMI data.
EUR/USD is falling after disappointing PMI s from the eurozone. The composite PMI fell by more than expected to 47.1 from 47.5 in October. This is down from 48.1 in September. The data indicates that the economy has fallen further into recessionary territory.
GBPUSD has pared earlier gains and is now trading mildly lower versus the USD as all eyes are on the leadership race. Rishi Sunak looks set to win, which had sent the pound higher earlier in the session given that he is considered the fiscally more prudent candidate and perhaps better experienced to handle the UK’s finances. Still, PMI data highlights the dire economic situation that the next PM will inherit.
GBP/USD -0.1% at 1.1285
EUR/USD -0.4% at 0.9820
Oil falls as China demand falters
Oil prices are falling amid concerns over demand levels from China. The world’s largest oil importer reported underwhelming demand in September as strict COVID policies and fuel export curbs kept demand depressed.
China’s crude oil imports of 9.79 million barrels a day were up from August, but still 2% levels seen this time last year.
Doubts remain over China’s economic recovery. While Q3 GDP data was stronger than forecast concerns over the strict zrio-COVID policy and the ongoing property crisis are undermining pro-growth measures.
WTI crude trades -1.4% at $83.90
Brent trades -1.03% at $90.70
Learn more about trading oil here.
Looking ahead
14:45 US composite PMI
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.