



US open: Stocks rise but inflation, growth fears remain
US stocks rise at the end of a volatile week, US consumer confidence in focus.
Share this:

US futures
Dow futures +1 % at 32060
S&P futures +1.4% at 3986
Nasdaq futures +2% at 12186
In Europe
FTSE +1.7% at 7364
Dax +1.5% at 13957
Euro Stoxx +1.8% at 3676
US stocks are rising from 18-month lows hit in the previous session. With no fresh catalyst, this is unlikely to be a reversal in risk sentiment but more a short-covering heading into the weekend at the end of a very volatile week.
Fears of rising inflation, tighter monetary policy, and slowing economic growth have plagued the markets this week after US inflation slowed by less than expected, fuelling expectation for a long road to reining in inflation. Once again, Fed Chair Powell pushed back on the prospect of a 75 basis point rate hike.
US consumer confidence is expected to show that morale dropped in May to 64, down from 65.2 in April. However, so far, deteriorating consumer sentiment hasn’t translated into a change in consumer habits. US retail sales are due next week, and the expectation is for sales to tick higher, even as inflation sits around a 40-year high.
In corporate news:
Twitter trades over 10% lower after Elon Musk said that the $44 billion deal was on hold. It’s impossible to get inside Elon Musk’s head but could the sharp drop in the Tesla share price and, more broadly, the stock market sell-off be part of the reason?
Where next for the Dow Jones?
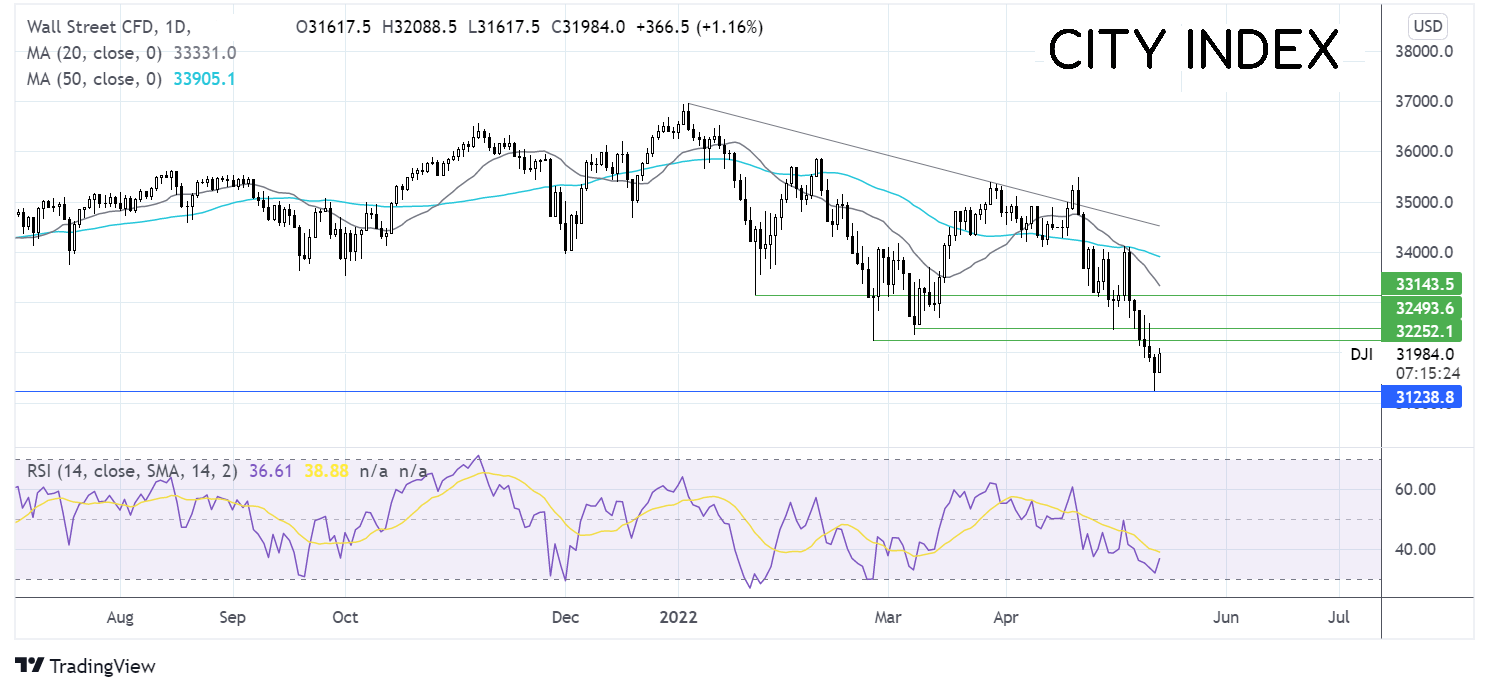
The selloff in the Dow appears to have found a floor for now at 31250 yesterday’s low, although the price would need to rise above 32250-32500 resistance to create any hope of pushing higher. The long wick on yesterday’s candle suggests that there was little acceptance for the price at the lower levels. However, sellers could focus on 20 sma crossing below the 50 sma in a bearish signal and the bearish RSI. Sellers need a break below 31630 today’s low and yesterday’s low of 312450 to create a lower low.

FX markets USD steadies at 20 years high
USD is holding steady after rising to fresh 20-year highs in the previous session. The USD is being driven higher on a perfect cocktail of hawkish Fed bets and safe-haven flows amid the fear of what an aggressive Fed could mean for economic growth.
USD/JPY – The yen was the top-performing currency yesterday; however, dovish comments from the BoJ overnight, despite signs of higher inflation over the medium term, have dragged the currency lower today, lifting USDJPY from its two week low.
EUR/USD is holding steady below 1.04 as bears pause for breath following yesterday’s heavy selloff. Eurozone industrial production fell by less than expected in March at -1.8% MoM, down from 0.7% in February but better than the 2% forecast.
GBP/USD -0.13% at 1.2190
EUR/USD +0.01% at 1.04370
Oil rises but is set for weekly declines.
Oil is rebounding higher on Friday but is set for a weekly loss, the first in three weeks, as anxieties over the demand outlook overshadow supply-side worries.
Fears over inflation, tighter monetary policy, and its impact on global growth, plus ongoing lockdowns in China, knocked prices lower across the week. The fact that the EU is also struggling to get the ban on Russian oil approved has undoubtedly played a role in lowering oil prices. Obstacles remain to the deal, and time will tell whether they can be overcome.
COVID cases and the ongoing lockdown in China remains a key factor for the oil demand outlook. However, the one step forward and two steps back nature of treating Omicron with zero-tolerance means that there is still no natural end in sight.
WTI crude trades +1.7% at $106.78
Brent trades +1.3% at $108.74
Looking ahead
15:00 Michigan consumer confidence
18:00 Baker Hughes oil rig count
US futures
Dow futures +1 % at 32060
S&P futures +1.4% at 3986
Nasdaq futures +2% at 12186
In Europe
FTSE +1.7% at 7364
Dax +1.5% at 13957
Euro Stoxx +1.8% at 3676
Learn more about trading indices
US stocks are rising from 18-month lows hit in the previous session. With no fresh catalyst, this is unlikely to be a reversal in risk sentiment but more a short-covering heading into the weekend at the end of a very volatile week.
Fears of rising inflation, tighter monetary policy, and slowing economic growth have plagued the markets this week after US inflation slowed by less than expected, fuelling expectation for a long road to reining in inflation. Once again, Fed Chair Powell pushed back on the prospect of a 75 basis point rate hike.
US consumer confidence is expected to show that morale dropped in May to 64, down from 65.2 in April. However, so far, deteriorating consumer sentiment hasn’t translated into a change in consumer habits. US retail sales are due next week, and the expectation is for sales to tick higher, even as inflation sits around a 40-year high.
In corporate news:
Twitter trades over 10% lower after Elon Musk said that the $44 billion deal was on hold. It’s impossible to get inside Elon Musk’s head but could the sharp drop in the Tesla share price and, more broadly, the stock market sell-off be part of the reason?
More news on the stocks to watch
Where next for the Dow Jones?
The selloff in the Dow appears to have found a floor for now at 31250 yesterday’s low, although the price would need to rise above 32250-32500 resistance to create any hope of pushing higher. The long wick on yesterday’s candle suggests that there was little acceptance for the price at the lower levels. However, sellers could focus on 20 sma crossing below the 50 sma in a bearish signal and the bearish RSI. Sellers need a break below 31630 today’s low and yesterday’s low of 312450 to create a lower low.
FX markets USD steadies at 20 years high
USD is holding steady after rising to fresh 20-year highs in the previous session. The USD is being driven higher on a perfect cocktail of hawkish Fed bets and safe-haven flows amid the fear of what an aggressive Fed could mean for economic growth.
USD/JPY – The yen was the top-performing currency yesterday; however, dovish comments from the BoJ overnight, despite signs of higher inflation over the medium term, have dragged the currency lower today, lifting USDJPY from its two week low.
EUR/USD is holding steady below 1.04 as bears pause for breath following yesterday’s heavy selloff. Eurozone industrial production fell by less than expected in March at -1.8% MoM, down from 0.7% in February but better than the 2% forecast.
GBP/USD -0.13% at 1.2190
EUR/USD +0.01% at 1.04370
Oil rises but is set for weekly declines.
Oil is rebounding higher on Friday but is set for a weekly loss, the first in three weeks, as anxieties over the demand outlook overshadow supply-side worries.
Fears over inflation, tighter monetary policy, and its impact on global growth, plus ongoing lockdowns in China, knocked prices lower across the week. The fact that the EU is also struggling to get the ban on Russian oil approved has undoubtedly played a role in lowering oil prices. Obstacles remain to the deal, and time will tell whether they can be overcome.
COVID cases and the ongoing lockdown in China remains a key factor for the oil demand outlook. However, the one step forward and two steps back nature of treating Omicron with zero-tolerance means that there is still no natural end in sight.
WTI crude trades +1.7% at $106.78
Brent trades +1.3% at $108.74
Learn more about trading oil here.
Looking ahead
15:00 Michigan consumer confidence
18:00 Baker Hughes oil rig count
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.