



US open: Stocks rise cautiously ahead of the Fed
Futures are edging higher, shrugging off Putin's call for mobilisation and looking ahead to the Fed's rate announcement.
Share this:

US futures
Dow futures +0.36% at 30819
S&P futures +0.37% at 3863
Nasdaq futures +0.11% at 11868
In Europe
FTSE +0.75% at 7234
Dax -0.06% at 12665
Euro Stoxx -0.8% at 3462
Central banks are the only game in town
US stocks are heading carefully higher after booking losses in the previous session and as investors prepare themselves for another large rate hike.
The US central bank will conclude its 2-day monetary policy meeting later today and is expected to raise rates by 75 basis points, its third straight 75 bps points hike. Some are preparing for a 100 basis point hike, but this is not the base case scenario.
The Fed’s growth and inflation projections will also be in focus and could help the market assess how hawkish the Fed is likely to be going forward. With this in mind, it is unlikely to be the rate hike itself that is market moving. Instead, it will be the outlook for further hikes and how hawkish the Fed is expected to be at the future meetings. A more aggressive Fed means the central bank will have more problems engineering a soft landing.
The broader market recovered from weakness early in the European session following a speech by Russian President Putin, who said he was mobilizing troops to defend the annexed part of Ukraine.
Corporate news:
General Mills rises 2% pre-market after raising complete year sales and profits forecasts, amid expectations of resilient demand for cereals, snack bars, and pet food even as prices rise.
Beyond Meat falls 1.4% pre-market after the immediate suspension of its COO following reports of his arrest following an altercation where he bit a man’s nose.
Where next for the S&p500?
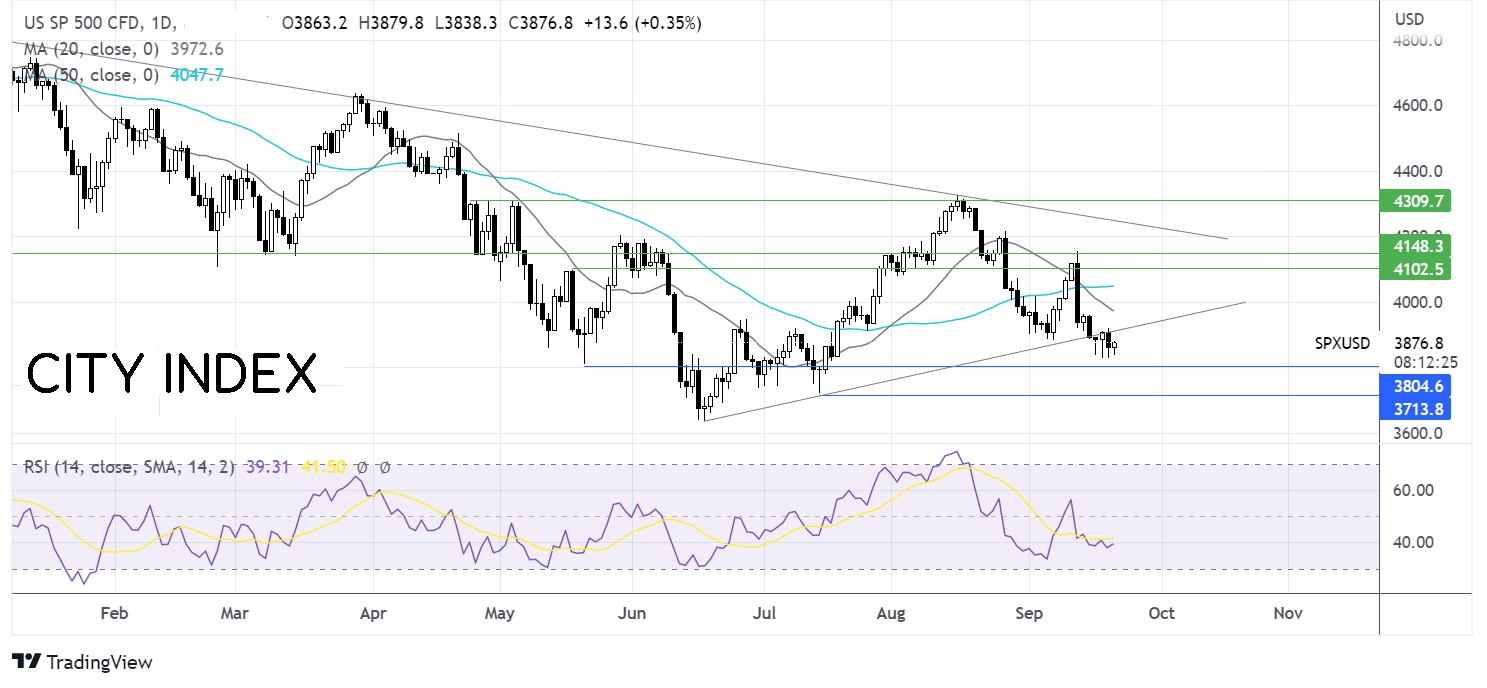
The S&P500 fell below the multi-month rising trend line support and has been unable to rise back above the trendline resistance. The RSI supports further downside. Sellers will need to break below 3827, the weekly low, to extend the bearish trend towards 3810, the May low, and 3720, the July 14 low. Buyers could be encouraged by the long lower wicks suggesting that demand is weak at these lower levels. Buyers will look for a rise over 3940, the weekly high to expose the 20 sma at 3966 and the 50 sma at 4047.

FX markets – USD rises, EUR falls.
The USD rises firmly for a second straight day and trades around a 20-year high. The USD is benefiting from a combination of hawkish Fed bets and safe haven flows in a win-win trade. Part of the allure of the USD is also because there is no real other alternative.
EUR/USD is falling, underperforming its major peers as investors sell out of the euro after Putin’s announcement. The news, combined with hawkish Federal Reserve bets, leaves few reasons for investors to want to buy into euros.
GBP/USD is also trading under pressure after data showed that the UK government borrowed almost double to forecast amount in August. The UK public sector’s net borrowing jumped to £11.8 billion. Borrowing is likely to increase further to fund PM Liz Truss’s energy support package and additional tax cuts, which will be announced on Friday.
GBP/USD -0.32% at 1.1340
EUR/USD -0.63% at 0.99
Oil jumps as Russia fears rise.
Oil prices have jumped higher on news that Putin is mobilizing more troops. The escalation of the war in Ukraine raises fears of a tighter oil and gas supply.
This move by Putin raises the risk of a more prolonged war in Russia. Any hopes of a sooner end to the conflict have been put firmly to bed. This means that supply worries will be here for the longer term.
Separately, there appears to be little hope of a breakthrough to revive the Iran nuclear deal at this week’s UN General Assembly. This effectively reduces the prospect of Iranian barrels returning to the market soon.
WTI crude trades +2.6% at $86.01
Brent trades +2.5% at $91.81
Looking ahead
15:30 EIA crude oil stockpiles
19:00 Fed rate decision
19:30 Fed Press Conference
US futures
Dow futures +0.36% at 30819
S&P futures +0.37% at 3863
Nasdaq futures +0.11% at 11868
In Europe
FTSE +0.75% at 7234
Dax -0.06% at 12665
Euro Stoxx -0.8% at 3462
Learn more about trading indices
Central banks are the only game in town
US stocks are heading carefully higher after booking losses in the previous session and as investors prepare themselves for another large rate hike.
The US central bank will conclude its 2-day monetary policy meeting later today and is expected to raise rates by 75 basis points, its third straight 75 bps points hike. Some are preparing for a 100 basis point hike, but this is not the base case scenario.
The Fed’s growth and inflation projections will also be in focus and could help the market assess how hawkish the Fed is likely to be going forward. With this in mind, it is unlikely to be the rate hike itself that is market moving. Instead, it will be the outlook for further hikes and how hawkish the Fed is expected to be at the future meetings. A more aggressive Fed means the central bank will have more problems engineering a soft landing.
The broader market recovered from weakness early in the European session following a speech by Russian President Putin, who said he was mobilizing troops to defend the annexed part of Ukraine.
Corporate news:
General Mills rises 2% pre-market after raising complete year sales and profits forecasts, amid expectations of resilient demand for cereals, snack bars, and pet food even as prices rise.
Beyond Meat falls 1.4% pre-market after the immediate suspension of its COO following reports of his arrest following an altercation where he bit a man’s nose.
Where next for the S&p500?
The S&P500 fell below the multi-month rising trend line support and has been unable to rise back above the trendline resistance. The RSI supports further downside. Sellers will need to break below 3827, the weekly low, to extend the bearish trend towards 3810, the May low, and 3720, the July 14 low. Buyers could be encouraged by the long lower wicks suggesting that demand is weak at these lower levels. Buyers will look for a rise over 3940, the weekly high to expose the 20 sma at 3966 and the 50 sma at 4047.
FX markets – USD rises,EUR falls
The USD rises firmly for a second straight day and trades around a 20-year high. The USD is benefiting from a combination of hawkish Fed bets and safe haven flows in a win-win trade. Part of the allure of the USD is also because there is no real other alternative.
EUR/USD is falling, underperforming its major peers as investors sell out of the euro after Putin’s announcement. The news, combined with hawkish Federal Reserve bets, leaves few reasons for investors to want to buy into euros.
GBP/USD is also trading under pressure after data showed that the UK government borrowed almost double to forecast amount in August. The UK public sector’s net borrowing jumped to £11.8 billion. Borrowing is likely to increase further to fund PM Liz Truss’s energy support package and additional tax cuts, which will be announced on Friday.
GBP/USD -0.32% at 1.1340
EUR/USD -0.63% at 0.99
Oil jumps as Russia fears rise.
Oil prices have jumped higher on news that Putin is mobilizing more troops. The escalation of the war in Ukraine raises fears of a tighter oil and gas supply.
This move by Putin raises the risk of a more prolonged war in Russia. Any hopes of a sooner end to the conflict have been put firmly to bed. This means that supply worries will be here for the longer term.
Separately, there appears to be little hope of a breakthrough to revive the Iran nuclear deal at this week’s UN General Assembly. This effectively reduces the prospect of Iranian barrels returning to the market soon.
WTI crude trades +2.6% at $86.01
Brent trades +2.5% at $91.81
Learn more about trading oil here.
Looking ahead
15:30 EIA crude oil stockpiles
19:00 Fed rate decision
19:30 Fed Press Conference
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.