



US open: Stocks rise on China hope
Stocks are set to open modestly higher as the market mood improves. Beijing pledging to increase vaccinations is a first step to removing zero-Covid restrictions.
Share this:

US futures
Dow futures +0.07% at 33790
S&P futures +0.03% at 3963
Nasdaq futures +0.13% at 11608
In Europe
FTSE +0.5% at 7529
Dax -0.2% at 14390
Beijing pledges more vaccines
US stocks are set for a stronger start amid rising speculation that the unrest in China from Covid restrictions would force authorities to move faster to loosen curbs. Beijing didn’t announce any major changes to the current measures by did say that it would speed up the pace of vaccinations among senior citizens. This could be considered a crucial step toward ending strict lockdown rules.
The change in mood comes after widespread unrest in China yesterday in response to strict unsustainable Covid restrictions. China is at a critical juncture for its policy.
In addition to China, stocks are benefitting from optimism that the Federal Reserve could slow the pace of rate hikes as from the December meeting. Federal Reserve speakers yesterday sent mixed messages. NY Fed President John Williams suggested that there is still work to be done to tame inflation, but there could be a cut next year. James Bullard and Vice Lael Brainard also flagged the amount of work still to be done. The hawkish chatter could be a prelude to Federal Reserve Chair Jerome Powell’s speech tomorrow.
Adding to the upbeat mood, initial data from Adobe Analytics showed a record-breaking Cyber Monday as US spending tops $11.6 billion. This was an 8.5% rise over 2021 when interest rates were still low. This may well be the last hooray for retailers, as strong spending suggests that investors were keen to snap up a deal amid high inflation and rising interest rates.
Looking ahead, attention will turn to US consumer confidence data which is expected to show that morale slowed slightly to 100, from 102.5.
Corporate news:
Apple is rebounding on China optimism after losses yesterday amid the unrest at the Foxconn plant.
UPS jumps 1.4% pre-market after Deutsche Bank upgrades its stance to buy from hold, saying that macro concerns are now priced into the stock.
Where next for the Nasdaq?
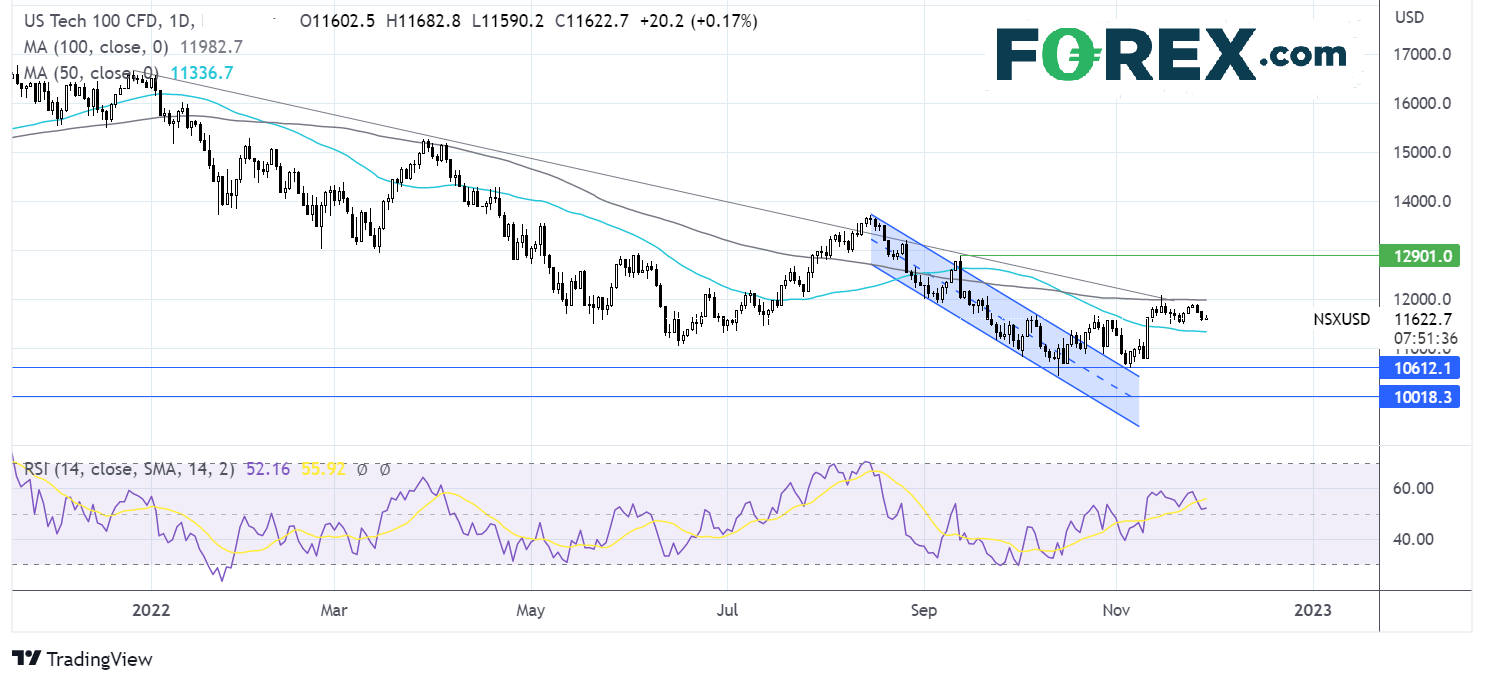
The Nasdaq is consolidating, caught between the 100 sma, which is capping gains, and the 50 sma, limiting losses. The RSI is approaching neutral. A breakout trade could be considered. Buyers will look for a rise over the 100 sma at 12030 to bring 12900, the September high, into focus. Sellers could look for a move below 11380, the 50 sma, to open the door to 10600, the November low.
FX markets – USD falls, EUR rises
The USD is falling as the market mood improves and investors digest Fed officials' latest commentary. Attention is now turning toward Jerome Powell’s speech tomorrow.
EURUSD is rising after stronger-than-expected economic sentiment data and after German inflation cooled to 11.3%, down from the record high of 11.6% in October. The data comes after ECB President Lagarde warned that inflation in the region could still push higher. Her comments fueled bets of more interest rate hikes.
GBP/USD is holding over 1.20 but trades off its daily high after disappointing data. UK mortgage approvals fell sharply to 58.9k, the lowest level since June 2020, as interest rates rise. BoE’s Andrew Bailey is due to speak later.
GBP/USD +0.3% at 1.12
EUR/USD +0.05% at 1.0330
Oil rebounds
Volatility in oil prices continues on Tuesday. After touching a new year-to-date low yesterday, oil prices have rounded, trading some 3% higher on optimism that China could soon ease its zero-Covid measures.
The prospect of a return to normality in China, the world’s largest oil importer, is good news for the demand outlook and has fueled the first decent rebound in oil prices in over two weeks.
Also supporting the oil price is speculation that OPEC+ could cut production further to support the price of oil. The oil cartel cut production in October, and the price now trades below where it was at that meeting.
WTI crude trades +2.03% at $78.80
Brent trades at +2.3% at $85.12
Looking ahead
15:00 US consumer confidence
21:30 API crude oil stockpiles
US futures
Dow futures +0.07% at 33790
S&P futures +0.03% at 3963
Nasdaq futures +0.13% at 11608
In Europe
FTSE +0.5% at 7529
Dax -0.2% at 14390
Learn more about trading indices
Beijing pledges more vaccines
US stocks are set for a stronger start amid rising speculation that the unrest in China from Covid restrictions would force authorities to move faster to loosen curbs. Beijing didn’t announce any major changes to the current measures by did say that it would speed up the pace of vaccinations among senior citizens. This could be considered a crucial step toward ending strict lockdown rules.
The change in mood comes after widespread unrest in China yesterday in response to strict unsustainable Covid restrictions. China is at a critical juncture for its policy.
In addition to China, stocks are benefitting from optimism that the Federal Reserve could slow the pace of rate hikes as from the December meeting. Federal Reserve speakers yesterday sent mixed messages. NY Fed President John Williams suggested that there is still work to be done to tame inflation, but there could be a cut next year. James Bullard and Vice Lael Brainard also flagged the amount of work still to be done. The hawkish chatter could be a prelude to Federal Reserve Chair Jerome Powell’s speech tomorrow.
Adding to the upbeat mood, initial data from Adobe Analytics showed a record-breaking Cyber Monday as US spending tops $11.6 billion. This was an 8.5% rise over 2021 when interest rates were still low. This may well be the last hooray for retailers, as strong spending suggests that investors were keen to snap up a deal amid high inflation and rising interest rates.
Looking ahead, attention will turn to US consumer confidence data which is expected to show that morale slowed slightly to 100, from 102.5.
Corporate news:
Apple is rebounding on China optimism after losses yesterday amid the unrest at the Foxconn plant.
UPS jumps 1.4% pre-market after Deutsche Bank upgrades its stance to buy from hold, saying that macro concerns are now priced into the stock.
Where next for the Nasdaq?
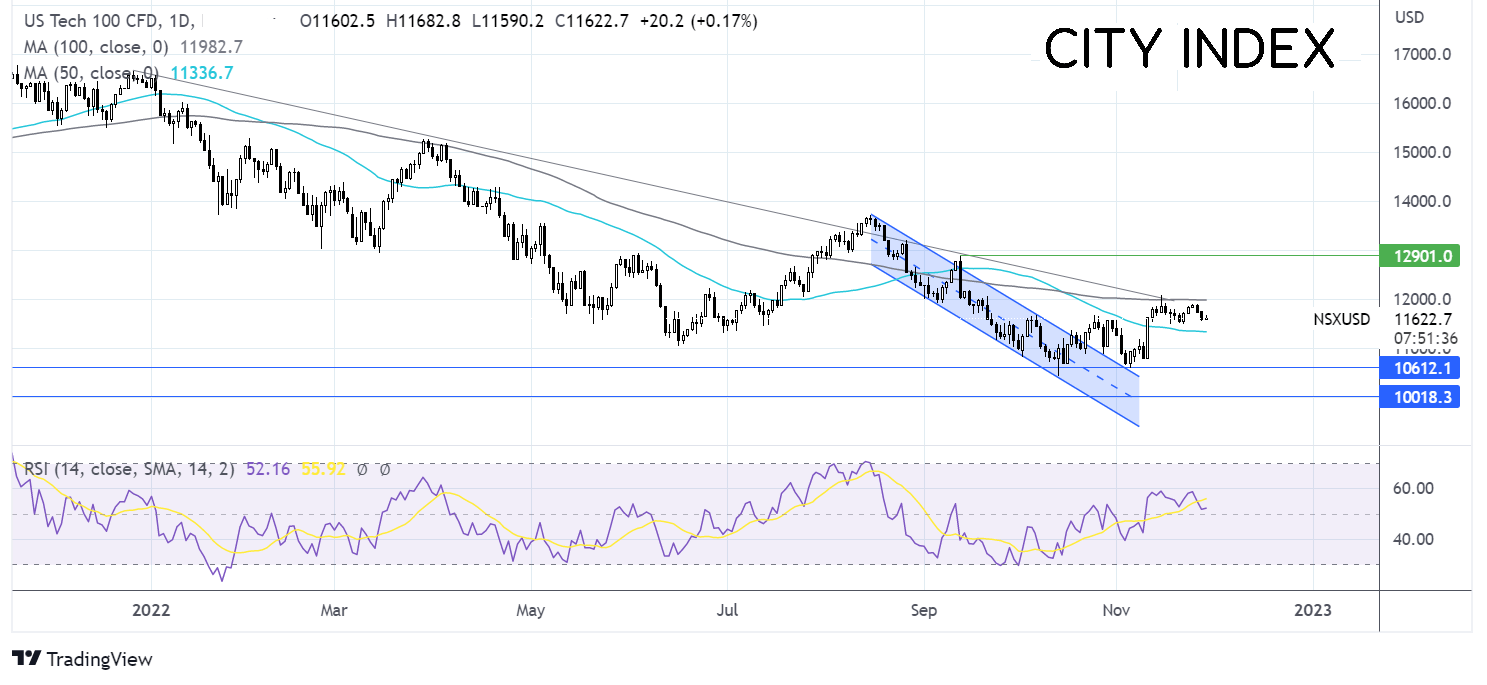
The Nasdaq is consolidating, caught between the 100 sma, which is capping gains, and the 50 sma, limiting losses. The RSI is approaching neutral. A breakout trade could be considered. Buyers will look for a rise over the 100 sma at 12030 to bring 12900, the September high, into focus. Sellers could look for a move below 11380, the 50 sma, to open the door to 10600, the November low.
FX markets – USD falls, EUR rises
The USD is falling as the market mood improves and investors digest Fed officials' latest commentary. Attention is now turning toward Jerome Powell’s speech tomorrow.
EURUSD is rising after stronger-than-expected economic sentiment data and after German inflation cooled to 11.3%, down from the record high of 11.6% in October. The data comes after ECB President Lagarde warned that inflation in the region could still push higher. Her comments fueled bets of more interest rate hikes.
GBP/USD is holding over 1.20 but trades off its daily high after disappointing data. UK mortgage approvals fell sharply to 58.9k, the lowest level since June 2020, as interest rates rise. BoE’s Andrew Bailey is due to speak later.
GBP/USD +0.3% at 1.12
EUR/USD +0.05% at 1.0330
Oil rebounds
Volatility in oil prices continues on Tuesday. After touching a new year-to-date low yesterday, oil prices have rounded, trading some 3% higher on optimism that China could soon ease its zero-Covid measures.
The prospect of a return to normality in China, the world’s largest oil importer, is good news for the demand outlook and has fueled the first decent rebound in oil prices in over two weeks.
Also supporting the oil price is speculation that OPEC+ could cut production further to support the price of oil. The oil cartel cut production in October, and the price now trades below where it was at that meeting.
WTI crude trades +2.03% at $78.80
Brent trades at +2.3% at $85.12
Learn more about trading oil here.
Looking ahead
15:00 US consumer confidence
21:30 API crude oil stockpiles
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.