



US open: Stocks rise, Russia cuts gas supplies, tech shows divergence
US stocks are heading higher after weakness yesterday and despite Russia cutting gas supplies to Poland and Bulgaria.
Share this:

US futures
Dow futures +0.7 % at 33450
S&P futures +0.42% at 4196
Nasdaq futures +0.2% at 13040
In Europe
FTSE +0.6% at 7437
Dax +0.02% at 14020
Euro Stoxx +0.24% at 3730
Learn more about trading indices
Investors brush off Russian developments, for now
US stocks are set for a mildly stronger start after a selloff in stocks yesterday and as investors digest news of Russia cutting off gas supplies to Poland and Bulgaria and the latest from earnings season.
The fact that stocks are rising despite Russia cutting off the gas supply to parts of Europe is somewhat surprising. The move by Putin to weaponise energy escalates tensions between the EU and Russia to new levels.
This could be considered a warning shot to Germany, which is particularly dependent on Russian oil. The move has mainly been reflected in the euro, with stocks on both sides of the Atlantic moving higher.
Still, after the Nasdaq plunged 3.2% yesterday, bargain hunters are out lifting the index.
Looking ahead, the US economic calendar is relatively quiet. US pending home sales are expected to decline again in March, having fallen on surging prices for the past four months.
In corporate news:
Tech stock’s earnings show an increased divergence between those that could continue to outperform and those that are set to see some weakness after the pandemic. While Microsoft reported ahead of expectations thanks to the booming Cloud business, Alphabet’s numbers were less impressive missing forecasts. Alphabet suffered a big miss owing to more competition and as consumers came off YouTube as the economic re-opened.
Alphabet’s results don’t bode well for Facebook parent Meta, which is due to report after the close.
More news on the stocks to watch
Where next for the Dow Jones?
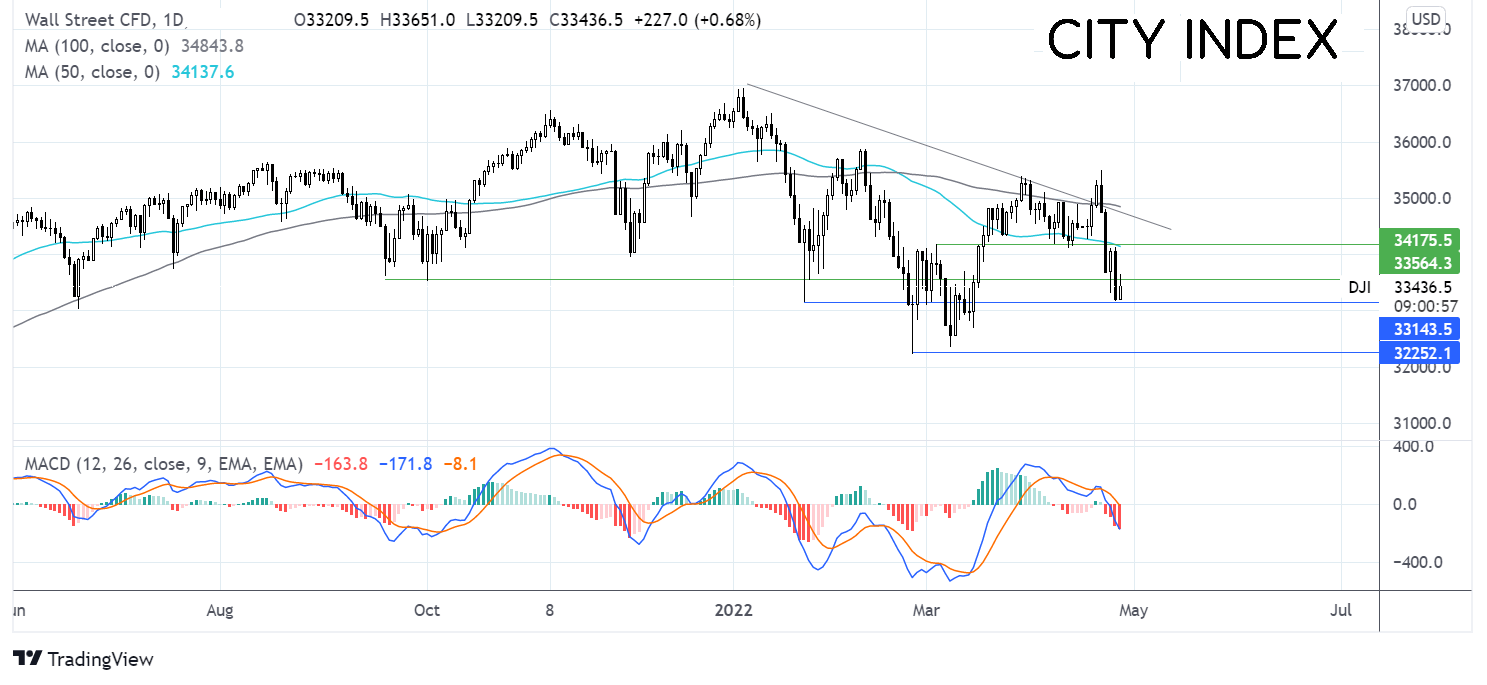
The Dow Jones ran into resistance at 35500, rebounding lower, breaking below the 50 & 100 sma. The price found support yesterday at around the 33150 mark and is attempting a bounce. Failure to capitalise on the move over 33580, along with the bearish MACD, keeps sellers optimistic about further downside. Sellers would need to break below 33150 to open the door to 32250, the 2022 low. Any recovery would need to break above 33500 to expose the 50 sma at 34200, with a move above this level creating a higher high and opening the door to the 100 sma at 34890.
FX markets USD rises, and EUR falls to a five-year low.
USD is extending gains, trading at a two-year high, driven by a combination of safe-haven flows amid the Russian war and China’s COVID and hawkish Fed expectations.
GBP/USD hovers around its 21 months after falling sharply yesterday on the darkening economic outlook and higher government spending. BoE rate hike bets have been reined in with 144 basis points hike expected across the year, down from 160 basis points.
EUR/USD trades below 1.06 at a 5-year low on rising Russian tensions and central bank divergence. Concerns over energy security and inflation fears add to the negative picture surrounding the euro. German consumer confidence dropped to a historic low of -26.3 heading into May, down from -15.5 in April.
GBP/USD -0.01% at 1.2576
EUR/USD -0.5% at 1.0586
Oil steadies as demand concerns remain
Oil is trading steadily on Wednesday after rallying 3.5% yesterday following Russia cutting gas supplies to Bulgaria and Poland. The move by Gazprom over payments not being made in rubles marks a significant escalation of Russia’s energy row with the West.
Crude oil prices have remained relatively calm given the severity of what is going on. However, supply fears were reflected elsewhere within the energy complex, with gas prices jumping 20%.
Keeping the lid on gains, demand fears remain as China’s COVID situation appears to be deteriorating, and fears of more lockdowns linger amid mass testing in Beijing.
USD strength is also capping gains as a stronger dollar makes oil more expensive for buyers with other currencies.
Looking ahead, attention will be on US oil inventory data after API data revealed that crude stockpiles unexpectedly rose by 4.78M barrels.
WTI crude trades -0.4% at $101.74
Brent trades +0.6% at $105.02
Learn more about trading oil here.
Looking ahead
15:00 US pending home sales
15:30 EIA crude oil
17:00 ECB President Lagarde’s speech
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
US futures
Dow futures +0.7 % at 33450
S&P futures +0.42% at 4196
Nasdaq futures +0.2% at 13040
In Europe
FTSE +0.6% at 7437
Dax +0.02% at 14020
Euro Stoxx +0.24% at 3730
Investors brush off Russian developments, for now
US stocks are set for a mildly stronger start after a selloff in stocks yesterday and as investors digest news of Russia cutting off gas supplies to Poland and Bulgaria and the latest from earnings season.
The fact that stocks are rising despite Russia cutting off the gas supply to parts of Europe is somewhat surprising. The move by Putin to weaponise energy escalates tensions between the EU and Russia to new levels.
This could be considered a warning shot to Germany, which is particularly dependent on Russian oil. The move has mainly been reflected in the euro, with stocks on both sides of the Atlantic moving higher.
Still, after the Nasdaq plunged 3.2% yesterday, bargain hunters are out lifting the index.
Looking ahead, the US economic calendar is relatively quiet. US pending home sales are expected to decline again in March, having fallen on surging prices for the past four months.
In corporate news:
Tech stock’s earnings show an increased divergence between those that could continue to outperform and those that are set to see some weakness after the pandemic. While Microsoft reported ahead of expectations thanks to the booming Cloud business, Alphabet’s numbers were less impressive missing forecasts. Alphabet suffered a big miss owing to more competition and as consumers came off YouTube as the economic re-opened.
Alphabet’s results don’t bode well for Facebook parent Meta, which is due to report after the close.
Where next for the Dow Jones?
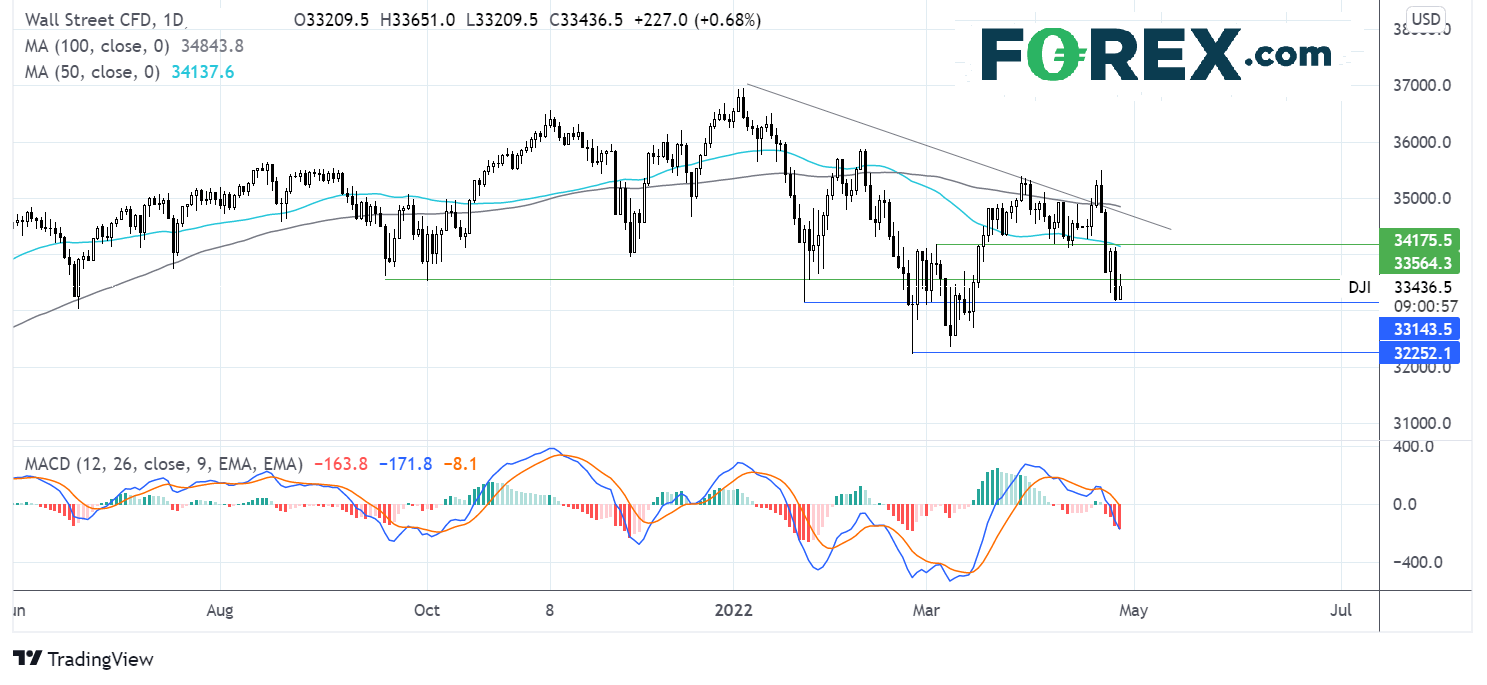
The Dow Jones ran into resistance at 35500, rebounding lower, breaking below the 50 & 100 sma. The price found support yesterday at around the 33150 mark and is attempting a bounce. Failure to capitalise on the move over 33580, along with the bearish MACD, keeps sellers optimistic about further downside. Sellers would need to break below 33150 to open the door to 32250, the 2022 low. Any recovery would need to break above 33500 to expose the 50 sma at 34200, with a move above this level creating a higher high and opening the door to the 100 sma at 34890.
FX markets USD rises, and EUR falls to a five-year low.
USD is extending gains, trading at a two-year high, driven by a combination of safe-haven flows amid the Russian war and China’s COVID and hawkish Fed expectations.
GBP/USD hovers around its 21 months after falling sharply yesterday on the darkening economic outlook and higher government spending. BoE rate hike bets have been reined in with 144 basis points hike expected across the year, down from 160 basis points.
EUR/USD trades below 1.06 at a 5-year low on rising Russian tensions and central bank divergence. Concerns over energy security and inflation fears add to the negative picture surrounding the euro. German consumer confidence dropped to a historic low of -26.3 heading into May, down from -15.5 in April.
GBP/USD -0.01% at 1.2576
EUR/USD -0.5% at 1.0586
Oil steadies as demand concerns remain
Oil is trading steadily on Wednesday after rallying 3.5% yesterday following Russia cutting gas supplies to Bulgaria and Poland. The move by Gazprom over payments not being made in rubles marks a significant escalation of Russia’s energy row with the West.
Crude oil prices have remained relatively calm given the severity of what is going on. However, supply fears were reflected elsewhere within the energy complex, with gas prices jumping 20%.
Keeping the lid on gains, demand fears remain as China’s COVID situation appears to be deteriorating, and fears of more lockdowns linger amid mass testing in Beijing.
USD strength is also capping gains as a stronger dollar makes oil more expensive for buyers with other currencies.
Looking ahead, attention will be on US oil inventory data after API data revealed that crude stockpiles unexpectedly rose by 4.78M barrels.
WTI crude trades -0.4% at $101.74
Brent trades +0.6% at $105.02
Looking ahead
15:00 US pending home sales
15:30 EIA crude oil
17:00 ECB President Lagarde’s speech
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.