



US open: Stocks slide ahead of big tech earnings
US stocks are heading lower after 2 days of strong gains. Earnings ramp up and all eyes turn to big tech ahead of the Microsoft & Alphabets's earnings after the close.
Share this:

US futures
Dow futures -0.62% at 31313
S&P futures -0.26% at 3777
Nasdaq futures -0.23% at 11400
In Europe
FTSE -1% at 6950
Dax -1.2% at 12782
US consumer confidence data due
After two days of solid gains, US stocks are heading lower on Tuesday as investors digest the latest batch of earnings and as they look ahead to big tech earnings which kick off after the close today.
Stocks rose yesterday after a fourth straight monthly decline in business activity, which fueled hopes that the Fed’s aggressive hikes to cool the economy was taking effect. This, in turn raised hopes that the Fed could soon start to ease back on the pace of rate hikes.
Looking ahead, US consumer confidence data is due later and is expected to show that morale fell again in October to 106.5, down from 108 in September.
All eyes will then turn to the start of big tech earnings, with Microsoft and Alphabet set to be under the spotlight. Big tech is often looking at for clues surrounding the broader economy, such as the health of the consumer.
If SNAP was the canary in the coal mine, investors may be worried about the impact that inflation is having on advertising revenue growth. Advertising spending is usually one of the first areas to see cuts when recession fears rise.
Meanwhile, Microsoft is expected to post the slowest revenue growth in over five years.
Corporate news:
UPS is rising 3.5% pre-market after reporting a rise in Q3 adjusted profit. Higher delivery prices helped to offset weakening e-commerce demand.
General Motors rallied 4.7% pre-market after the automaker reported a stronger-than-expected quarterly profit and reiterated its full-year outlook.
Where next for the S&P500?
The S&P has extended its recovery from the 2022 low, out of the multi-week falling channel and above the 20 sma, but has stalled around the 3800 level. The RSI above 50 keeps buyers hopeful of further upside. A rise over 3800 exposes the 50 sma at 3860, before brining 3900 round number into play. Should sellers successfully defend 3800, the price could fall to 369 the 20 sma, before re-entering the falling channel.

FX markets – USD rises, GBP rises
The USD is rising after three days of declines amid softening expectations for Fed rate hikes. Following the report in the WSJ, plus comments from San Francisco Fed President Mary Daly, which fuelled bets of a dovish pivot, investors sold out of the greenback. Today yields on the 10-year treasury are edging lower again but remain over 4%.
EUR/USD is falling after German IFO business sentiment remained gloomy in October, dipping to 84.3, down from 84.4. The IFO President said that the German economy facing a difficult winter. The data painted a similar picture to that of the PMI yesterday.
GBPUSD is rising as Rishi Sunak becomes next Prime Minister. The former Chancellor has a mammoth task ahead of him as he tackles the mounting economic crisis facing the UK and his warring political party. In his first speech he said that economic stability and confidence is at the heart of his agenda. So far the markets have stabilised, trusting in the fiscally prudent leaders. Gilt yields have fallen.
GBP/USD +0.4% at 1.1320
EUR/USD -0.14% at 0.9860
Oil falls ahead of inventory data
Oil prices are falling for a second straight day as fears over slowing economic growth hurt the demand outlook. Disappointing PMI data across the board raised concerns of a recession.
With supply and demand fundamentals holding steady for now, economic sentiment is the driving force. Much of the deteriorating economic outlook has likely been priced in so prices could find a floor around these levels.
Looking ahead, oil inventory data is due later and is expected to rise by 200,000 barrels in the week to 21st October. High levels of inventory could drag the price lower.
WTI crude trades +1.4% at $83.90
Brent trades +1.03% at $90.70
Looking ahead
21:30 API oil stockpile data
US futures
Dow futures -0.62% at 31313
S&P futures -0.26% at 3777
Nasdaq futures -0.23% at 11400
In Europe
FTSE -1% at 6950
Dax -1.2% at 12782
Learn more about trading indices
US consumer confidence data due
After two days of solid gains, US stocks are heading lower on Tuesday as investors digest the latest batch of earnings and as they look ahead to big tech earnings which kick off after the close today.
Stocks rose yesterday after a fourth straight monthly decline in business activity, which fueled hopes that the Fed’s aggressive hikes to cool the economy was taking effect. This, in turn raised hopes that the Fed could soon start to ease back on the pace of rate hikes.
Looking ahead, US consumer confidence data is due later and is expected to show that morale fell again in October to 106.5, down from 108 in September.
All eyes will then turn to the start of big tech earnings, with Microsoft and Alphabet set to be under the spotlight. Big tech is often looking at for clues surrounding the broader economy, such as the health of the consumer.
If SNAP was the canary in the coal mine, investors may be worried about the impact that inflation is having on advertising revenue growth. Advertising spending is usually one of the first areas to see cuts when recession fears rise.
Meanwhile, Microsoft is expected to post the slowest revenue growth in over five years.
Corporate news:
UPS is rising 3.5% pre-market after reporting a rise in Q3 adjusted profit. Higher delivery prices helped to offset weakening e-commerce demand.
General Motors rallied 4.7% pre-market after the automaker reported a stronger-than-expected quarterly profit and reiterated its full-year outlook.
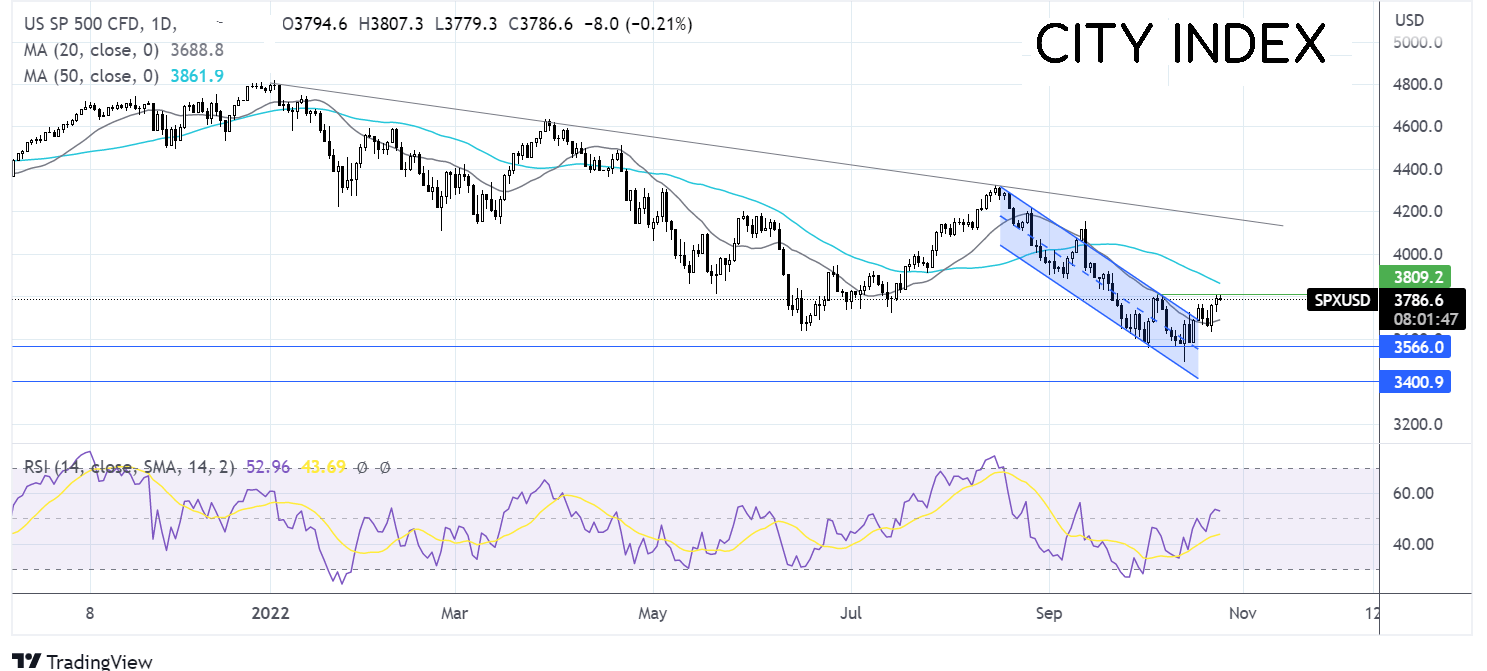
Where next for the S&P500?
The S&P has extended its recovery from the 2022 low, out of the multi-week falling channel and above the 20 sma, but has stalled around the 3800 level. The RSI above 50 keeps buyers hopeful of further upside. A rise over 3800 exposes the 50 sma at 3860, before brining 3900 round number into play. Should sellers successfully defend 3800, the price could fall to 369 the 20 sma, before re-entering the falling channel.
FX markets – USD rises, GBP rises
The USD is rising after three days of declines amid softening expectations for Fed rate hikes. Following the report in the WSJ, plus comments from San Francisco Fed President Mary Daly, which fuelled bets of a dovish pivot, investors sold out of the greenback. Today yields on the 10-year treasury are edging lower again but remain over 4%.
EUR/USD is falling after German IFO business sentiment remained gloomy in October, dipping to 84.3, down from 84.4. The IFO President said that the German economy facing a difficult winter. The data painted a similar picture to that of the PMI yesterday.
GBPUSD is rising as Rishi Sunak becomes next Prime Minister. The former Chancellor has a mammoth task ahead of him as he tackles the mounting economic crisis facing the UK and his warring political party. In his first speech he said that economic stability and confidence is at the heart of his agenda. So far the markets have stabilised, trusting in the fiscally prudent leaders. Gilt yields have fallen.
GBP/USD +0.4% at 1.1320
EUR/USD -0.14% at 0.9860
Oil falls ahead of inventory data
Oil prices are falling for a second straight day as fears over slowing economic growth hurt the demand outlook. Disappointing PMI data across the board raised concerns of a recession.
With supply and demand fundamentals holding steady for now, economic sentiment is the driving force. Much of the deteriorating economic outlook has likely been priced in so prices could find a floor around these levels.
Looking ahead, oil inventory data is due later and is expected to rise by 200,000 barrels in the week to 21st October. High levels of inventory could drag the price lower.
WTI crude trades +1.4% at $83.90
Brent trades +1.03% at $90.70
Learn more about trading oil here.
Looking ahead
21:30 API oil stockpile data
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.