



Will the bond market meltdown be the undoing of the S&P500 - Part II?
U.S yields punched to fresh cycle highs overnight on robust economic data and hawkish commentary from Fed Governor Brainard.
Share this:

U.S yields punched to fresh cycle highs overnight on robust economic data and hawkish commentary from Fed Governor Brainard.
Brainard said that balance sheet reduction would begin "at a rapid pace as soon as our May meeting" and expects the balance sheet to shrink "considerably more rapidly than in the previous recovery."
Brainard's speech comes before the release of March FOMC Minutes tomorrow morning and carries extra weight as she is renowned as one of the more 'dovish' members on the board.
10-year Treasury yields increased 15bp to 2.55%, their largest one day rise since March 2020, after being as low as 1.66% just one month ago.
In this article here two weeks ago, we noted St. Louis President Bullard's comparison of the current cycle to the 1994 tightening cycle when the Fed raised rates from 3.25% to 6% over 12 months. At the time, the inflation rate was at ~2.50% vs 7.9% currently.
During that period, the stock market fell 10% and then traded sideways for the remainder of the year as the speed of the tightening cycle and rise in yields caused indigestion issues for the stock market. More recently, a rapid rise in yields caused equity market mayhem in January 2018 and again in October 2018.
As I see it, the problem is that the selloff in the bond market (yields rising) is accelerating, meaning that an already troubling backdrop is deteriorating for the S&P500.
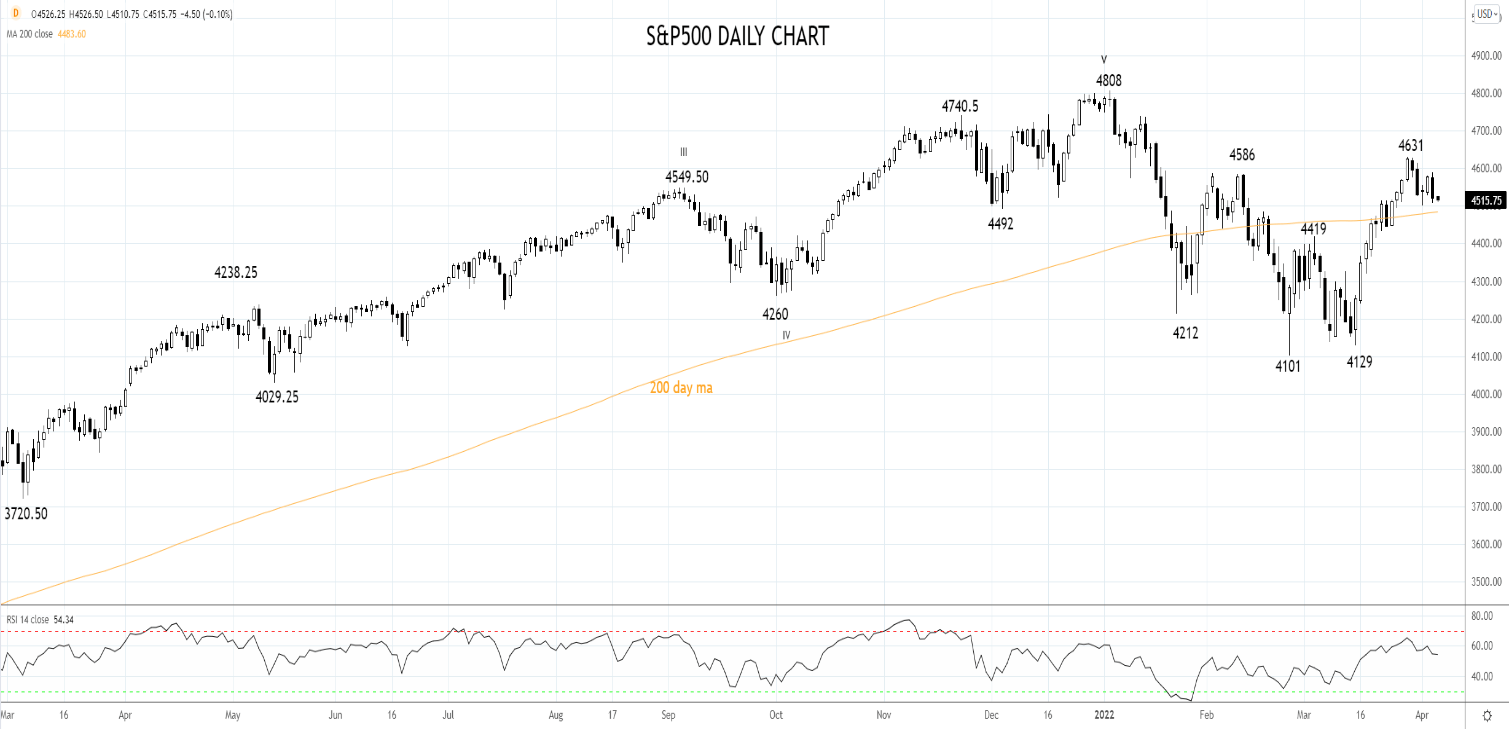
Not wanting to pre-empt a possible turn lower, we move to a short term tactical bearish bias in the S&P500 on a sustained close below the 200-day moving average currently at 4480/75.
The bearish call would increase in a conviction on a daily close below support at 4420/00, and the downside target in this instance would be a retest of support at 4130/4100.
Source Tradingview. The figures stated are as of April 6th 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
This content will only appear on Forex websites!
U.S yields punched to fresh cycle highs overnight on robust economic data and hawkish commentary from Fed Governor Brainard.
Brainard said that balance sheet reduction would begin "at a rapid pace as soon as our May meeting" and expects the balance sheet to shrink "considerably more rapidly than in the previous recovery."
Brainard's speech comes before the release of March FOMC Minutes tomorrow morning and carries extra weight as she is renowned as one of the more 'dovish' members on the board.
10-year Treasury yields increased 15bp to 2.55%, their largest one day rise since March 2020, after being as low as 1.66% just one month ago.
In this article here two weeks ago, we noted St. Louis President Bullard's comparison of the current cycle to the 1994 tightening cycle when the Fed raised rates from 3.25% to 6% over 12 months. At the time, the inflation rate was at ~2.50% vs 7.9% currently.
During that period, the stock market fell 10% and then traded sideways for the remainder of the year as the speed of the tightening cycle and rise in yields caused indigestion issues for the stock market. More recently, a rapid rise in yields caused equity market mayhem in January 2018 and again in October 2018.
As I see it, the problem is that the selloff in the bond market (yields rising) is accelerating, meaning that an already troubling backdrop is deteriorating for the S&P500.
Not wanting to pre-empt a possible turn lower, we move to a short term tactical bearish bias in the S&P500 on a sustained close below the 200-day moving average currently at 4480/75.
The bearish call would increase in a conviction on a daily close below support at 4420/00, and the downside target in this instance would be a retest of support at 4130/4100.
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.