




April 2020 Fed Meeting Instant Analysis
Near-zero interest rates and asset purchases are here to stay for the foreseeable future, based on the Fed's most recent statement...
Share this:
With traders keyed in on arguably the biggest week for earnings reports ever, not to mention daily 20%-30% moves in oil, today’s Federal Reserve meeting may have snuck up on some readers. Of course, the central bank has hardly had the luxury of waiting for its scheduled meetings to introduce new measures to limit the impact of the unprecedented economic disruption from the spread of COVID-19 over the past few weeks anyway!
In any event, the Fed remains the world’s most important central bank, and arguably the most important policymaking body when it comes to financial markets, so traders still tuned in for the latest economic assessment from Jerome Powell and Company.
As it turns out, the central bank mostly “stuck to the script” in its decision, leaving the Fed funds rate unchanged in the 0.00-0.25% range and the interest on excess reserves (IOER) at 0.10%. At the same time, the Fed also vowed to continue buying Treasuries, agency debt, and commercial mortgage-backed securities, as well as conducting large-scale repos, as much as needed. Finally, in a nod to the ongoing COVID-19 pandemic, the statement noted, “The ongoing public health crisis will weigh heavily on economic activity, employment, and inflation in the near term, and poses considerable risks to the economic outlook over the medium term...”
Finally, and perhaps most importantly, “the Committee expects to maintain this target range until it is confident that the economy has weathered recent events and is on track to achieve its maximum employment and price stability goals.” In other words, near-zero interest rates and asset purchases are here to stay for the foreseeable future.
Market Reaction
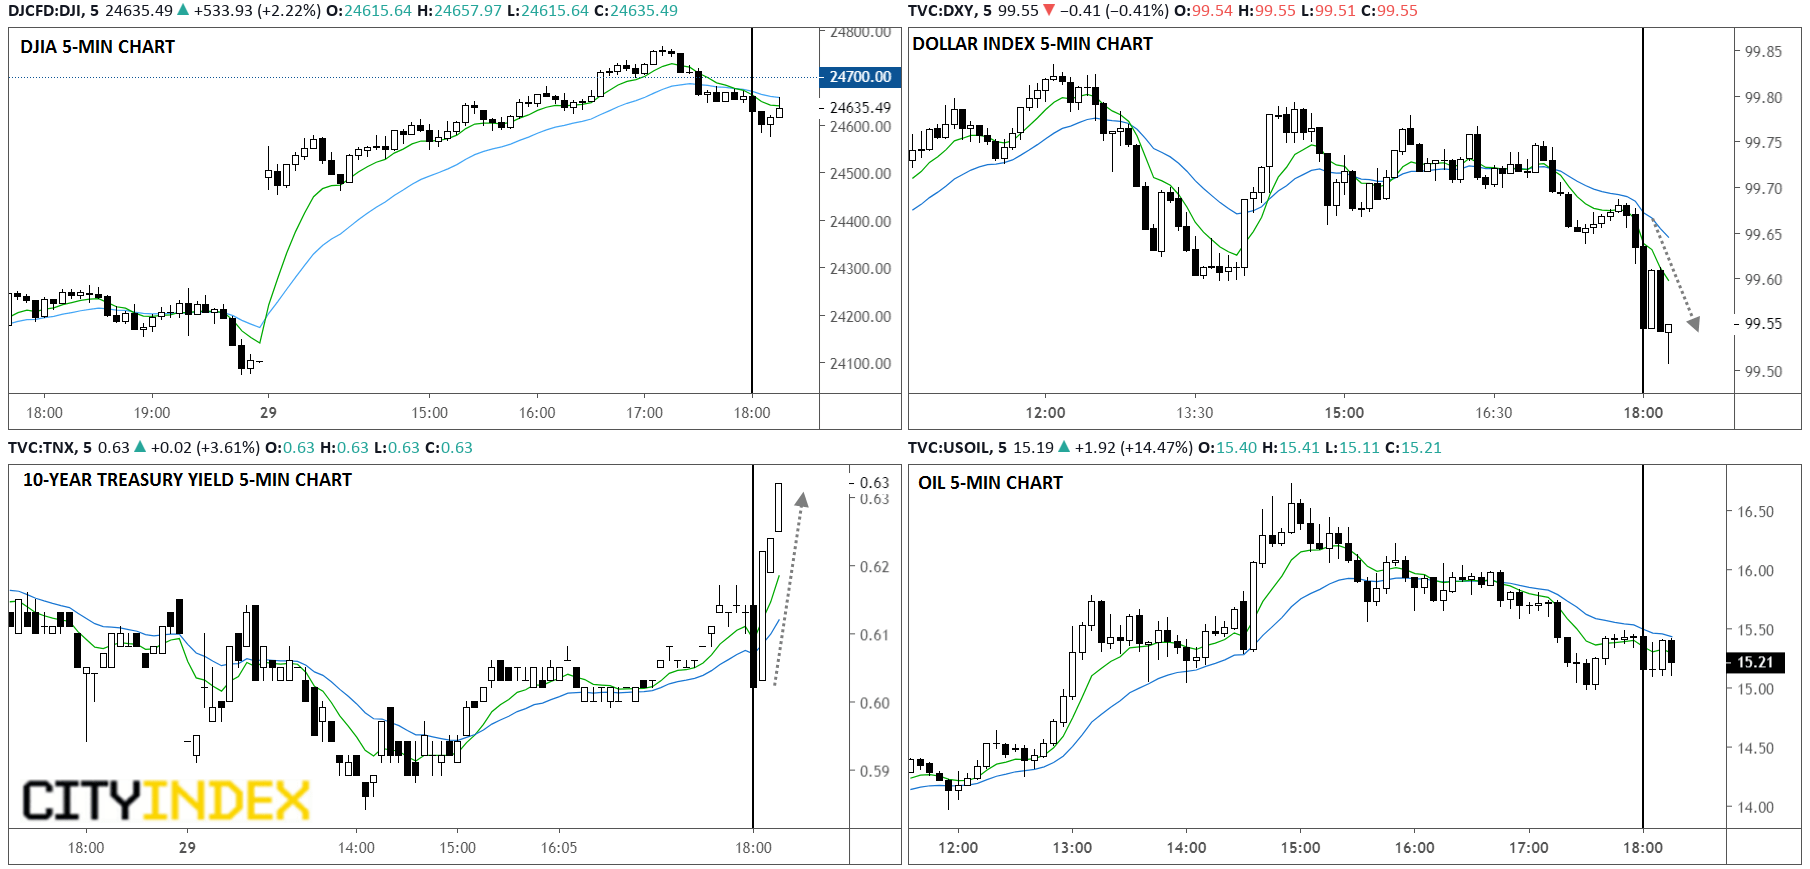
Financial markets took the Fed’s statement mostly in stride, with only small adjustments in major assets: US stock indices ticked lower (though remain well higher on the day), 10-year treasury yields ticked up 2bps to 0.63%, oil and gold both edged lower, and the US dollar dropped about 20 pips against most of its major rivals:
Source: TradingView, GAIN Capital
Now traders will tune in for Fed Chairman Powell’s press conference for any hints on future policy tweaks and more details on the central bank’s outlook for the economy.
With traders keyed in on arguably the biggest week for earnings reports ever, not to mention daily 20%-30% moves in oil, today’s Federal Reserve meeting may have snuck up on some readers. Of course, the central bank has hardly had the luxury of waiting for its scheduled meetings to introduce new measures to limit the impact of the unprecedented economic disruption from the spread of COVID-19 over the past few weeks anyway!
In any event, the Fed remains the world’s most important central bank, and arguably the most important policymaking body when it comes to financial markets, so traders still tuned in for the latest economic assessment from Jerome Powell and Company.
As it turns out, the central bank mostly “stuck to the script” in its decision, leaving the Fed funds rate unchanged in the 0.00-0.25% range and the interest on excess reserves (IOER) at 0.10%. At the same time, the Fed also vowed to continue buying Treasuries, agency debt, and commercial mortgage-backed securities, as well as conducting large-scale repos, as much as needed. Finally, in a nod to the ongoing COVID-19 pandemic, the statement noted, “The ongoing public health crisis will weigh heavily on economic activity, employment, and inflation in the near term, and poses considerable risks to the economic outlook over the medium term...”
Finally, and perhaps most importantly, “the Committee expects to maintain this target range until it is confident that the economy has weathered recent events and is on track to achieve its maximum employment and price stability goals.” In other words, near-zero interest rates and asset purchases are here to stay for the foreseeable future.
Market Reaction
Financial markets took the Fed’s statement mostly in stride, with only small adjustments in major assets: US stock indices ticked lower (though remain well higher on the day), 10-year treasury yields ticked up 2bps to 0.63%, oil and gold both edged lower, and the US dollar dropped about 20 pips against most of its major rivals:
Source: TradingView, GAIN Capital
Now traders will tune in for Fed Chairman Powell’s press conference for any hints on future policy tweaks and more details on the central bank’s outlook for the economy.
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


USD/CAD and USD/MXN Q4 2026 Outlook: Will the U.S. Dollar Dominate North America Again?
The final stretch of 2026 is approaching, and North America's major currencies have begun to show a shift in the strength dynamics seen earlier in the year. New expectations of a more aggressive monetary policy stance, particularly in the United States, could be significantly reshaping the outlook for the region. At the same time, this backdrop, combined with potential trade tensions across North America, may become one of the most important drivers of currency performance in the months ahead.


Gold Analysis: Rising Yields and Dollar Strength Weigh on XAU/USD
The trading week continues, and for now gold remains under notable pressure in the short term. This can be seen in the performance of XAU/USD over the last three trading sessions, where the metal has declined by more than 2.00%, bringing a bearish bias back into focus after it had lost momentum in recent weeks.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.