



Asia Morning Oct 19
U.S. Retail Sales jump 1.9% on month in September, but a fiscal stimulus package before the election seems impossible...
Share this:
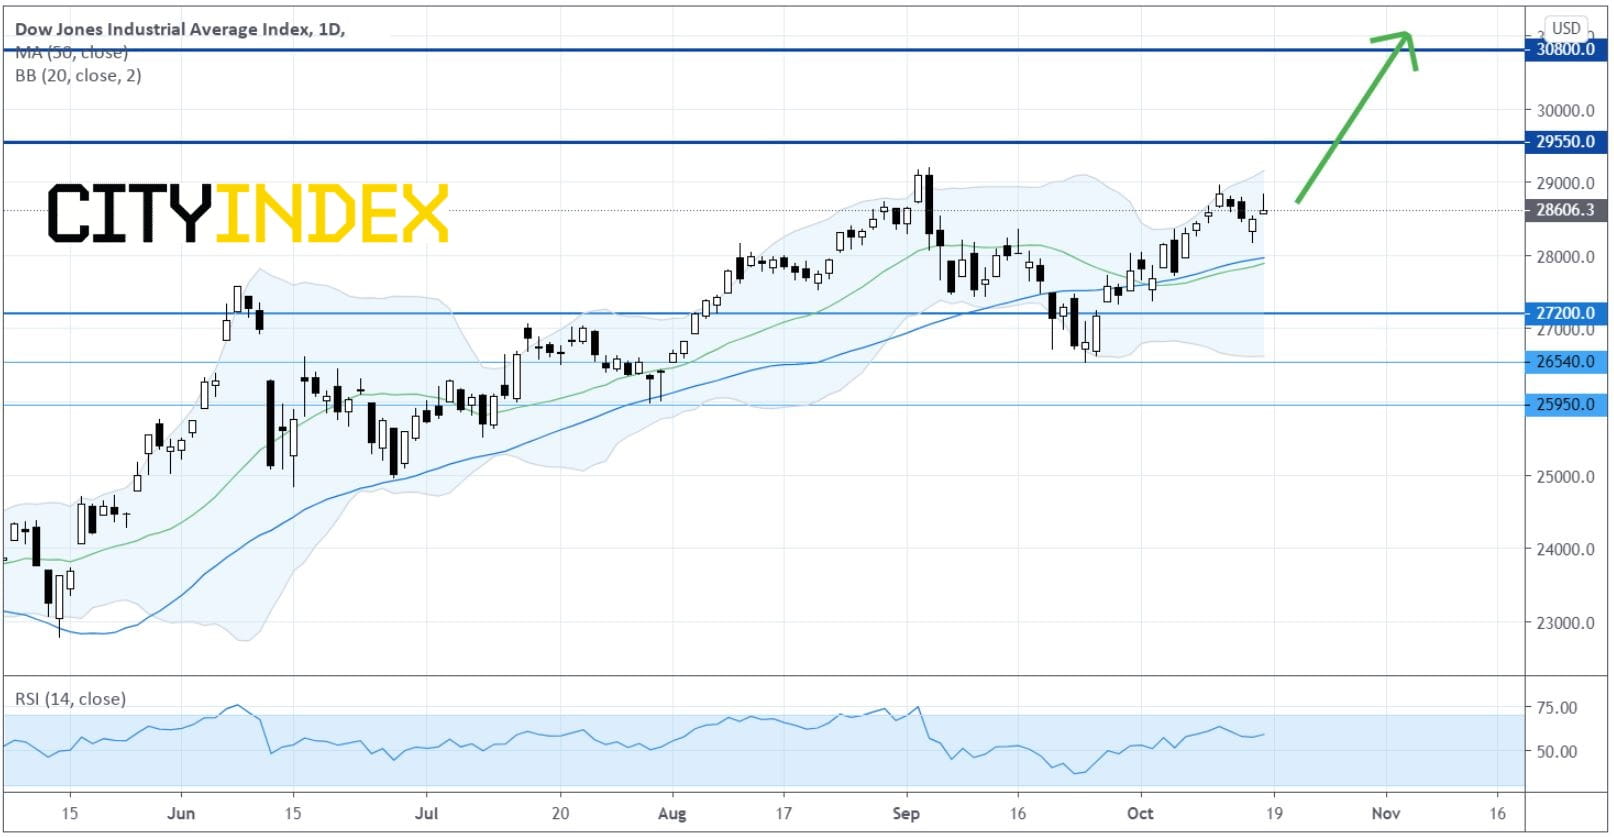
On Friday, U.S. stocks closed mixed. The Dow Jones Industrial Average rebounded 112 points (-0.39%) to 28606, the S&P 500 was flat at 3483, while the Nasdaq 100 sank a further 46 points (-0.39%) to 11852.
Dow Jones Industrial Average (Daily Chart) : Still Bullish
Sources: GAIN Capital, TradingView
U.S. official data showed that Retail Sales jumped 1.9% on month in September (vs. +0.8% expected, +0.6% in August). However, White House Economic advisor Larry Kudlow pointed out that it is almost impossible to execute a fiscal stimulus package before the November election.
Automobiles & Components (+1.21%), Capital Goods (+1.09%) and Utilities (+1.08%) sectors gained the most, while Energy (-2.3%), Retailing (-1.24%) and Technology Hardware & Equipment (-1.09%) sectors were under pressure.
Drug-maker Pfizer (PFE +3.83%) announced plans to apply for U.S. Emergency Authorization Use of its experimental COVID-19 vaccine by the late November the soonest.
Airplane-producer Boeing (BA +1.89%) has been approved to resume flying its 737 Max aircraft in European skies.
The University of Michigan's Consumer Sentiment Index (preliminary reading) increased to 81.2 in October (80.5 expected). Meanwhile, Industrial Production unexpectedly fell 0.6% on month in September (+0.5% expected).
European stocks returned to positive territory. The Stoxx Europe 600 Index rebounded 1.26%, Germany's DAX 30 rose 1.62%, France's CAC 40 jumped 2.03%, and the U.K.'s FTSE 100 was up 1.49%.
U.S. Treasury prices were little changed, as the benchmark 10-year Treasury yield ticked up to 0.740% from 0.734% Thursday.
Spot gold declined $9 (-0.49%) to $1,899 an ounce.
U.S. WTI crude futures (November) fell $0.21 (-0.51%) to $40.75 a barrel. Latest data from Oilfield services firm Baker Hughes showed that the number of active oil rigs in the U.S. climbed by 12 to 205, posting a four-week increase.
On the forex front, the U.S. dollar softened modestly against other major currencies. The ICE Dollar Index declined 0.19% to 93.68.
EUR/USD added 0.07% to 1.1716. Eurozone official data showed that Consumer Prices (final reading) dropped 0.3% on year in September (as expected).
GBP/USD edged up 4 pips to 1.2915. The pound hovered around gains and losses after U.K. Prime Minister Boris Johnson pointed out that his country was heading toward a No-Deal Brexit.
USD/JPY eased to 105.40 from 105.44.
USD/CAD slipped 0.21% to 1.3190 halting a three-day rally.
Meanwhile, AUD/USD sank a further 0.20% to 0.7079.
Dow Jones Industrial Average (Daily Chart) : Still Bullish
Sources: GAIN Capital, TradingView
U.S. official data showed that Retail Sales jumped 1.9% on month in September (vs. +0.8% expected, +0.6% in August). However, White House Economic advisor Larry Kudlow pointed out that it is almost impossible to execute a fiscal stimulus package before the November election.
Automobiles & Components (+1.21%), Capital Goods (+1.09%) and Utilities (+1.08%) sectors gained the most, while Energy (-2.3%), Retailing (-1.24%) and Technology Hardware & Equipment (-1.09%) sectors were under pressure.
Drug-maker Pfizer (PFE +3.83%) announced plans to apply for U.S. Emergency Authorization Use of its experimental COVID-19 vaccine by the late November the soonest.
Airplane-producer Boeing (BA +1.89%) has been approved to resume flying its 737 Max aircraft in European skies.
The University of Michigan's Consumer Sentiment Index (preliminary reading) increased to 81.2 in October (80.5 expected). Meanwhile, Industrial Production unexpectedly fell 0.6% on month in September (+0.5% expected).
European stocks returned to positive territory. The Stoxx Europe 600 Index rebounded 1.26%, Germany's DAX 30 rose 1.62%, France's CAC 40 jumped 2.03%, and the U.K.'s FTSE 100 was up 1.49%.
U.S. Treasury prices were little changed, as the benchmark 10-year Treasury yield ticked up to 0.740% from 0.734% Thursday.
Spot gold declined $9 (-0.49%) to $1,899 an ounce.
U.S. WTI crude futures (November) fell $0.21 (-0.51%) to $40.75 a barrel. Latest data from Oilfield services firm Baker Hughes showed that the number of active oil rigs in the U.S. climbed by 12 to 205, posting a four-week increase.
On the forex front, the U.S. dollar softened modestly against other major currencies. The ICE Dollar Index declined 0.19% to 93.68.
EUR/USD added 0.07% to 1.1716. Eurozone official data showed that Consumer Prices (final reading) dropped 0.3% on year in September (as expected).
GBP/USD edged up 4 pips to 1.2915. The pound hovered around gains and losses after U.K. Prime Minister Boris Johnson pointed out that his country was heading toward a No-Deal Brexit.
USD/JPY eased to 105.40 from 105.44.
USD/CAD slipped 0.21% to 1.3190 halting a three-day rally.
Meanwhile, AUD/USD sank a further 0.20% to 0.7079.
On Friday, U.S. stocks closed mixed. The Dow Jones Industrial Average rebounded 112 points (-0.39%) to 28606, the S&P 500 was flat at 3483, while the Nasdaq 100 sank a further 46 points (-0.39%) to 11852.
Dow Jones Industrial Average (Daily Chart) : Still Bullish

Sources: GAIN Capital, TradingView
U.S. official data showed that Retail Sales jumped 1.9% on month in September (vs. +0.8% expected, +0.6% in August). However, White House Economic advisor Larry Kudlow pointed out that it is almost impossible to execute a fiscal stimulus package before the November election.
Automobiles & Components (+1.21%), Capital Goods (+1.09%) and Utilities (+1.08%) sectors gained the most, while Energy (-2.3%), Retailing (-1.24%) and Technology Hardware & Equipment (-1.09%) sectors were under pressure.
Drug-maker Pfizer (PFE +3.83%) announced plans to apply for U.S. Emergency Authorization Use of its experimental COVID-19 vaccine by the late November the soonest.
Airplane-producer Boeing (BA +1.89%) has been approved to resume flying its 737 Max aircraft in European skies.
The University of Michigan's Consumer Sentiment Index (preliminary reading) increased to 81.2 in October (80.5 expected). Meanwhile, Industrial Production unexpectedly fell 0.6% on month in September (+0.5% expected).
European stocks returned to positive territory. The Stoxx Europe 600 Index rebounded 1.26%, Germany's DAX 30 rose 1.62%, France's CAC 40 jumped 2.03%, and the U.K.'s FTSE 100 was up 1.49%.
U.S. Treasury prices were little changed, as the benchmark 10-year Treasury yield ticked up to 0.740% from 0.734% Thursday.
Spot gold declined $9 (-0.49%) to $1,899 an ounce.
U.S. WTI crude futures (November) fell $0.21 (-0.51%) to $40.75 a barrel. Latest data from Oilfield services firm Baker Hughes showed that the number of active oil rigs in the U.S. climbed by 12 to 205, posting a four-week increase.
On the forex front, the U.S. dollar softened modestly against other major currencies. The ICE Dollar Index declined 0.19% to 93.68.
EUR/USD added 0.07% to 1.1716. Eurozone official data showed that Consumer Prices (final reading) dropped 0.3% on year in September (as expected).
GBP/USD edged up 4 pips to 1.2915. The pound hovered around gains and losses after U.K. Prime Minister Boris Johnson pointed out that his country was heading toward a No-Deal Brexit.
USD/JPY eased to 105.40 from 105.44.
USD/CAD slipped 0.21% to 1.3190 halting a three-day rally.
Meanwhile, AUD/USD sank a further 0.20% to 0.7079.
Dow Jones Industrial Average (Daily Chart) : Still Bullish
Sources: GAIN Capital, TradingView
U.S. official data showed that Retail Sales jumped 1.9% on month in September (vs. +0.8% expected, +0.6% in August). However, White House Economic advisor Larry Kudlow pointed out that it is almost impossible to execute a fiscal stimulus package before the November election.
Automobiles & Components (+1.21%), Capital Goods (+1.09%) and Utilities (+1.08%) sectors gained the most, while Energy (-2.3%), Retailing (-1.24%) and Technology Hardware & Equipment (-1.09%) sectors were under pressure.
Drug-maker Pfizer (PFE +3.83%) announced plans to apply for U.S. Emergency Authorization Use of its experimental COVID-19 vaccine by the late November the soonest.
Airplane-producer Boeing (BA +1.89%) has been approved to resume flying its 737 Max aircraft in European skies.
The University of Michigan's Consumer Sentiment Index (preliminary reading) increased to 81.2 in October (80.5 expected). Meanwhile, Industrial Production unexpectedly fell 0.6% on month in September (+0.5% expected).
European stocks returned to positive territory. The Stoxx Europe 600 Index rebounded 1.26%, Germany's DAX 30 rose 1.62%, France's CAC 40 jumped 2.03%, and the U.K.'s FTSE 100 was up 1.49%.
U.S. Treasury prices were little changed, as the benchmark 10-year Treasury yield ticked up to 0.740% from 0.734% Thursday.
Spot gold declined $9 (-0.49%) to $1,899 an ounce.
U.S. WTI crude futures (November) fell $0.21 (-0.51%) to $40.75 a barrel. Latest data from Oilfield services firm Baker Hughes showed that the number of active oil rigs in the U.S. climbed by 12 to 205, posting a four-week increase.
On the forex front, the U.S. dollar softened modestly against other major currencies. The ICE Dollar Index declined 0.19% to 93.68.
EUR/USD added 0.07% to 1.1716. Eurozone official data showed that Consumer Prices (final reading) dropped 0.3% on year in September (as expected).
GBP/USD edged up 4 pips to 1.2915. The pound hovered around gains and losses after U.K. Prime Minister Boris Johnson pointed out that his country was heading toward a No-Deal Brexit.
USD/JPY eased to 105.40 from 105.44.
USD/CAD slipped 0.21% to 1.3190 halting a three-day rally.
Meanwhile, AUD/USD sank a further 0.20% to 0.7079.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.