



Asia Morning US Stocks End in Red Trump Actions on China Awaited
On Thursday, U.S. stocks erased gains to close in the red after President Donald Trump announced plans to hold a Friday press conference on China...
Share this:

On Thursday, U.S. stocks erased gains to close in the red after President Donald Trump announced plans to hold a Friday press conference on China. Beijing has just passed a controversial national security law which is widely expected to erode Hong Kong's autonomy.
Sentiment was also hurt by Trump's saying that he would sign an executive order putting more scrutiny on social media companies.
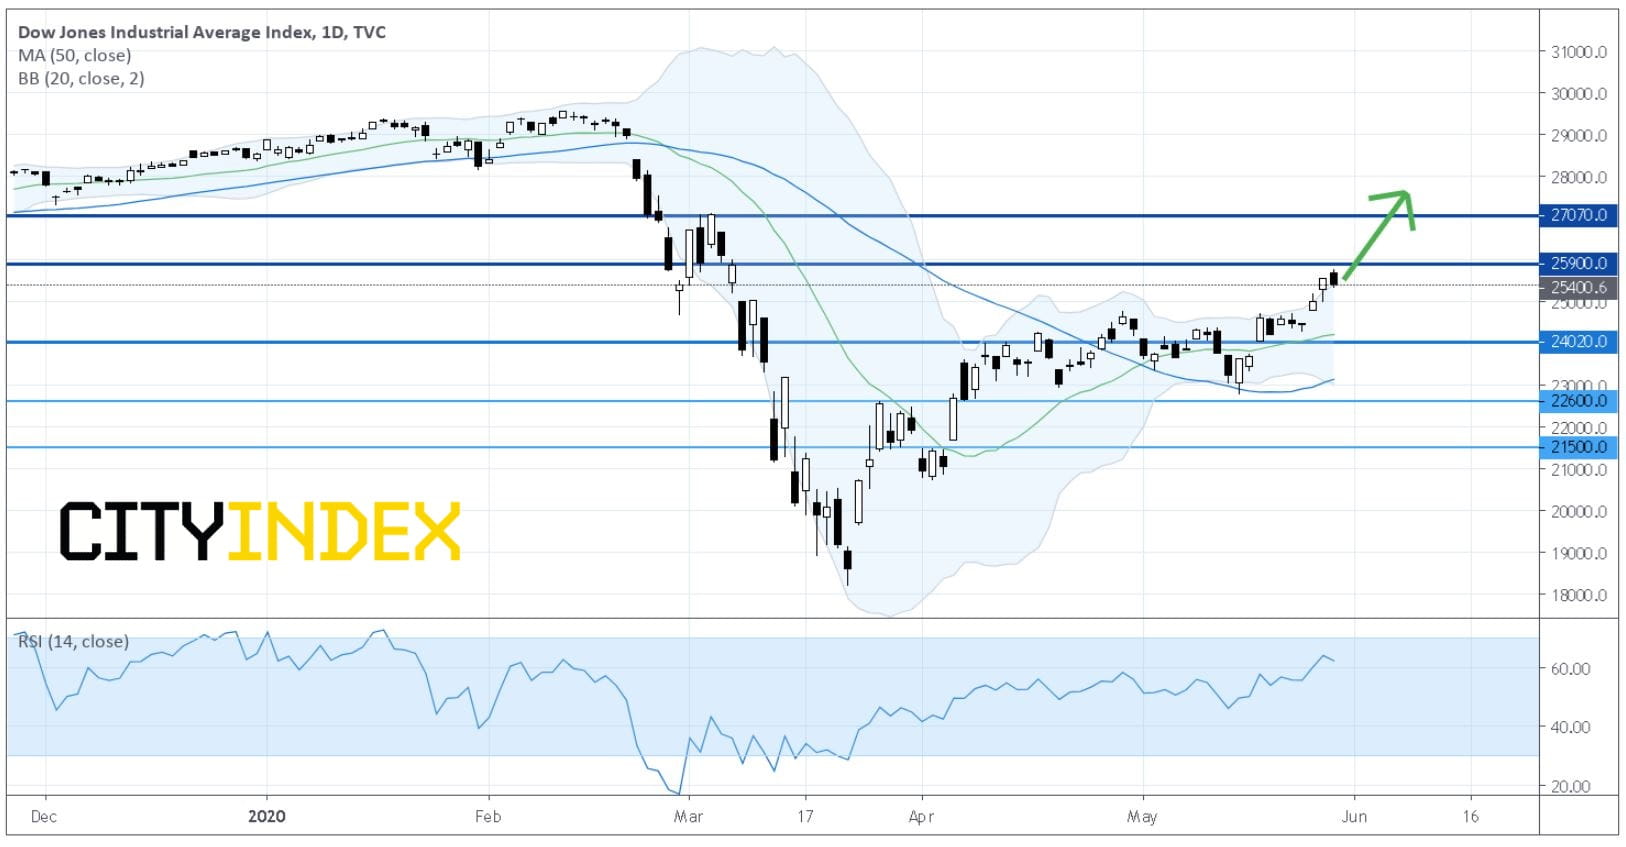
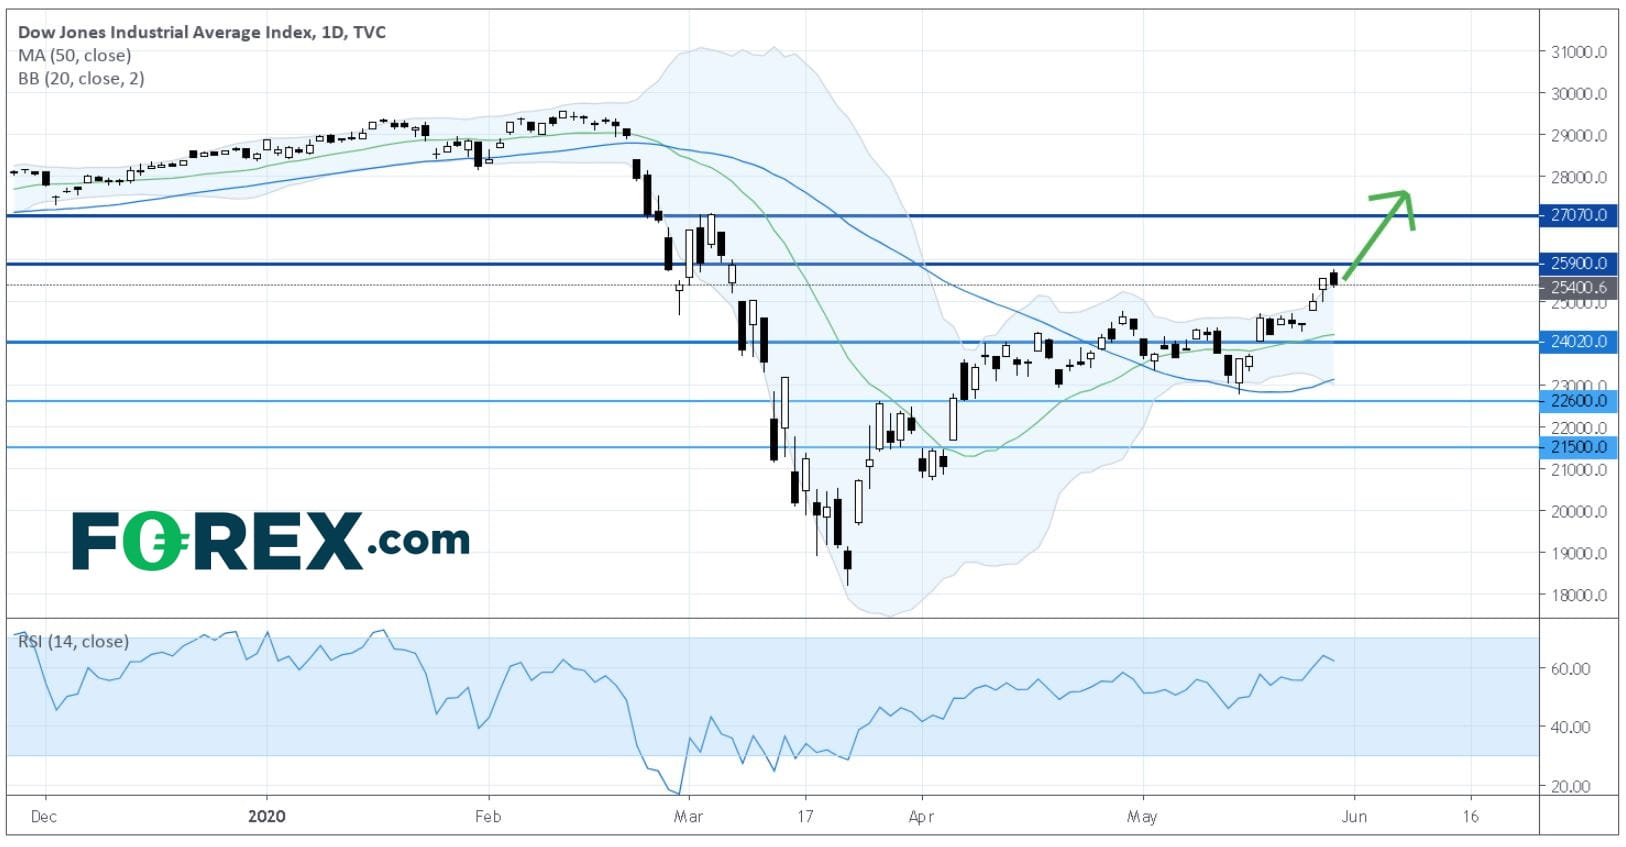
The Dow Jones Industrial Average slipped 147 points (-0.6%) to 25400, the S&P 500 dropped 6 points (-0.2%) to 3029 and the Nasdaq 100 was down 25 points (-0.3%) to 9416.
Source: GAIN Capital, TradingView
Automobiles & Components (-3.86%), Consumer Durables & Apparel (-3.13%) and Banks (-3.08%) sectors lost the most.
HP Inc (HPQ -12.32%), Kohls (KSS -9.74%), Hanesbrands (HBI -9.65%) and TripAdvisor (TRIP -9.46%) were top losers, while Dollar Tree (DLTR +11.55%), Alexion Pharmaceuticals (ALXN +7.80%) and Regeneron Pharmaceuticals (REGN +6.29%) were top gainers.
On the technical side, about 43.2% (38.0% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 89.5% (83.0% in the prior session) were above their 20-day moving average.
U.S. official data showed that first-quarter GDP (second reading) contracted at an annualized rate of 5.0% on quarter (-4.8% expected).
Initial Jobless Claims declined to 2.123 million for the week ended May 23 (2.100 million expected). Continuing Claims unexpectedly decreased to 21.052 million for the week ended May 16 (25.680 million expected) from the prior week's 24.912 million, showing that Americans are returning to work.
Durable Goods Orders (preliminary reading) dropped 17.2% on month in April, the biggest decline on record.
Later today, Wholesale Inventories (-0.7% on month in April expected), Personal Income (-6.0% on month expected), Personal Spending (-12.8% on month expected), Market News International's Chicago Purchasing Managers Index (40.0 in May expected) and the University of Michigan's Consumer Sentiment Index (74.0 in May expected) will be reported.
European stocks continues their advance, with the Stoxx Europe 600 Index rising 1.6%. Germany's DAX increased 1.1%, the U.K.'s FTSE 100 climbed 1.2% and France's CAC jumped 1.8%.
U.S. Treasury prices softened, as the benchmark 10-year Treasury yield stepped higher to 0.703%.
Spot gold price rebounded $8 (+0.5%) to $1,717 an ounce halting a three-day decline.
Oil prices rebounded despite a build of 7.9 million barrels in U.S. crude-oil stockpiles last week as reported by the Energy Information Administration. U.S. WTI crude oil futures (July) gained 2.7% to $33.71 a barrel.
On the forex front, the ICE U.S. Dollar Index dropped 0.4% on day to 98.47, the lowest level since March 30.
EUR/USD advanced 0.6% to 1.1076, posting a three-day rally. Official data showed that the eurozone's Economic Confidence Index bounced to 67.5 in May (70.6 expected) from 64.9 in April. Later today, the bloc's CPI data for May will be released (+0.1% on year expected).
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.