




Asian Open: DXY Coiling at Its Highs
Whilst USD/JPY rose to a 7-year high, DXY has been left for dust as it coils at its highs. Yet that suggests it could be approaching a period of volatility.
Share this:

Asian Futures:
- Australia's ASX 200 futures are down -27 points (-0.37%), the cash market is currently estimated to open at 7,272.80
- Japan's Nikkei 225 futures are down -30 points (-0.11%), the cash market is currently estimated to open at 28,468.20
- Hong Kong's Hang Seng futures are down -234 points (-0.93%), the cash market is currently estimated to open at 25,091.09
UK and Europe:
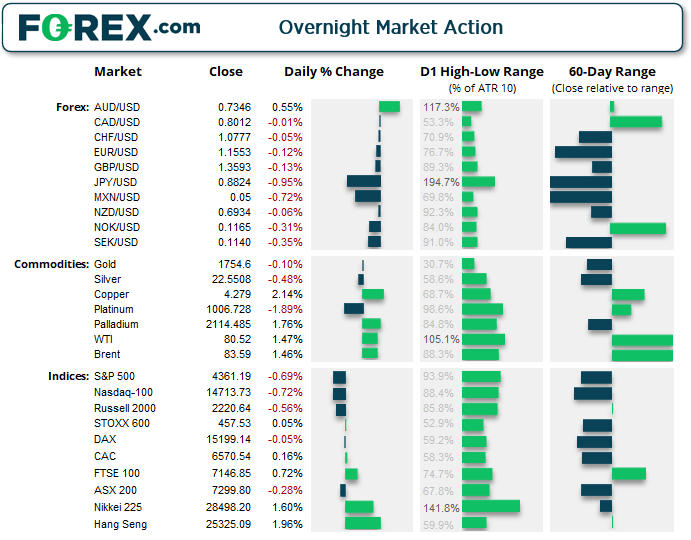
- UK's FTSE 100 index rose 51.3 points (0.72%) to close at 7,146.85
- Europe'sEuro STOXX 50 index fell -0.77 points (-0.02%) to close at 4,072.52
- Germany's DAX index fell -6.99 points (-0.05%) to close at 15,199.14
- France's CAC 40 index rose 10.55 points (0.16%) to close at 6,570.54
Monday US Close:
- The Dow Jones Industrial fell -250.19 points (-0.72%) to close at 34,496.06
- The S&P 500 index fell -30.15 points (-0.69%) to close at 4,361.19
- The Nasdaq 100 index fell -107.019 points (-0.72%) to close at 14,713.73
Indices:
Wall Street traded lower with higher energy prices continuing to fuel inflationary concerns just as earnings season kicks off. The S&P 500 fell -0.7% to a 4-day low, closing Thursday’s upside gap and the 50-day eMA has continued to cap as resistance on the closing chart. The energy sector (XLE) initially hit a 21-month high yet closed the day lower after oil’s rally lost some steam. Rising yields continued to weigh on technology stocks with the Nasdaq 100 falling -0.72% and communications services sector being the worst performer on the S&P. Traders also offloaded bonds to send yields higher to see US10Y rose to a 4-month high of 1.636.
The ASX 200 is yet to break above 7333.2 resistance, but its potential to do so remains on our radar. Yesterday’s trade printed a hammer candle with a lower wick, so a break above resistance confirms it as a bullish reversal candle whilst a break of its low confirms it as an inverted (bearish) hammer.
Futures markets point to a weak open in Asia.
ASX 200 Market Internals:


ASX 200: 7299.8 (-0.28%), 11 October 2021
- Energy (1.32%) was the strongest sector and Information Technology (-2.72%) was the weakest
- 4 out of the 11 sectors closed higher
- 7 out of the 11 sectors closed lower
- 4 out of the 11 sectors outperformed the index
- 66 (33.00%) stocks advanced, 123 (61.50%) stocks declined
- 63% of stocks closed above their 200-day average
- 40% of stocks closed above their 50-day average
- 45% of stocks closed above their 20-day average
Outperformers:
- + 6.19%-Whitehaven Coal Ltd(WHC.AX)
- + 5.26%-Fortescue Metals Group Ltd(FMG.AX)
- + 3.48%-Champion Iron Ltd (CIA.AX)
Underperformers:
- -22.9% -Star Entertainment Group Ltd(SGR.AX)
- -5.6% -Platinum Asset Management Ltd(PTM.AX)
- -5.38% -Skycity Entertainment Group Ltd(SKC.AX)
Forex:
The Japanese yen was by far the weakest major currency with all pairs far exceeding their 10-day ATR’s (average true ranges).
The US dollar continued to receive safe-haven flows alongside the yen, although yield differentials gave USD/JPY the upper hand as the pair closed above 113 for the first time in nearly 3-years. Traders appear confident the Fed will announce tapering next month despite the NFP miss, so central bank divergence is being reflected in price action.
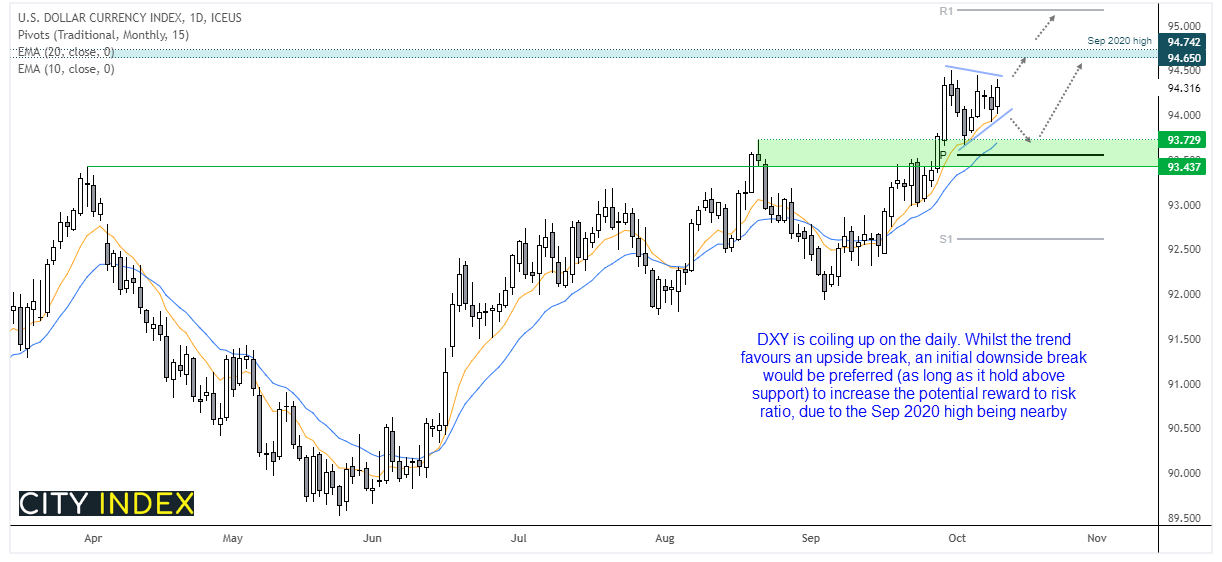

The US dollar index (DXY) continues to coil up within a potential continuation pattern on the daily chart. Whist the trend favours an upside break, from a reward to risk perspective we would prefer to see it break to the downside first and find support around the 93.43 – 93.73 zone. Should prices break higher, take note of the September 2020 high as it makes a likely resistance level, ahead of the 95 handle and monthly R2 pivot.
EUR/AUD broke beneath 1.5780 support in line with our bias, with the daily low stopping just pips above the 1.5664 – 1.5690 support zone. Whilst this leaves the potential for another period of consolidation, our bias remains bearish beneath the 1.5858 high although we would not expect prices to trade above 1.5780 is this is part of a strong move lower. AUD/USD rose to a 19-day high after its (rather messy) breakout from an inverted head and shoulders pattern. If successful, the pattern projects a target around 0.7448. AUD/NZD closed to a 10-week high and stopped just short of our 1.0600 target.
The Bank of Korea announce their monetary policy decision at 12:00 AEST. The consensus is for them to hold rates at 0.75% today but raise it to 1.00% at their November meeting.
Commodities:
Oil prices continued higher overnight but there are warning signs of overextension for the bull camp. WTI hit a 7-year high of 82.18 yet retraced back to 80.50 by the end of the session, leaving a bearish hammer on the daily charts. So perhaps the bullish move is now running on fumes.
Palladium reached our initial target of 2185 but, like oil prices left a bearish pinbar on the daily.
Up Next (Times in AEDT)
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.