



AUD remains rangebound ahead of tomorrow’s inflation report
Australian inflation data is released tomorrow, and if it comes in hotter than expected – like it did on New Zealand – if adds another fly in the ointment for the RBA
Share this:

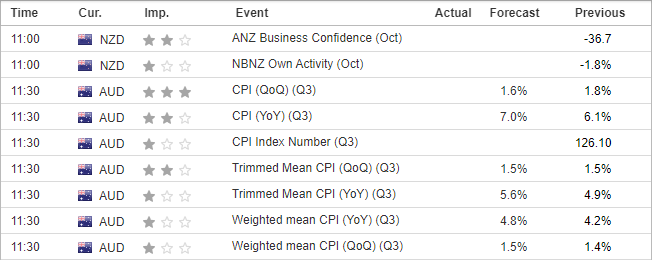
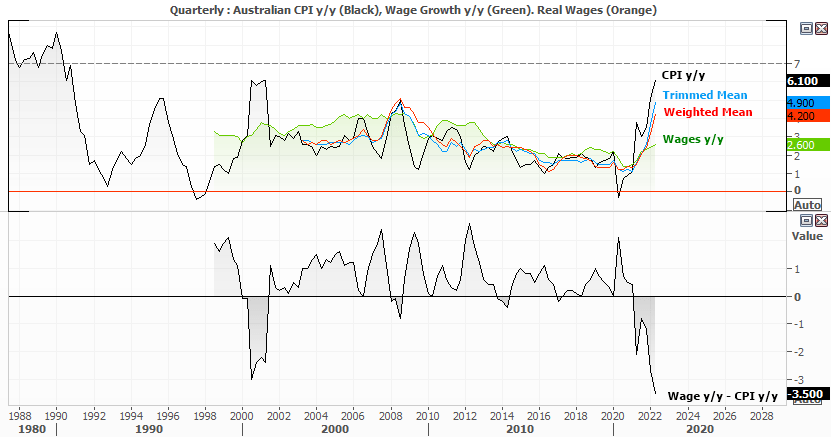
Inflation rose 6.1% y/y in Q2 and is expected to rise to 7% - which would be its highest level since 1990 and more than twice the RBA’s 2-3% target band. The quarterly read is expected to soften to 1.6%, down from 1.8% - which seems feasible given the newly released monthly CPI read softened slightly to 6.8% m/m from 7% m/m.
However, the RBA pay more attention to the Trimmed Mean and Weighted CPI prints, which are also widely above the RBA’s target. Trimmed mean is expected to rise to a record high of 5.6% yet remain at 1.5% q/q for a second consecutive quarter, whilst the Weighted CPI is expected to rise to 4.8% - its highest level since 2008 – and the quarterly read to rise to 1.5% (1.4% previously).
It is no secret that the RBA were late to respond to inflationary forces seen across the globe – based on the premise that ‘it was different in Australia’. Alas, inflation is here and it is indeed rising. And the RBA expect it to rise further, and estimate 2022 inflation to land at 7.75% before pulling back to around 3% over 2024.
Yet the RBA surprised markets with a mere 25bp hike at their last meeting, and interest rates are just 2.6% which is well below current rates of inflation. Yet during a testimony to the House of Representatives, RBA Governor Lowe pointed out that inflation expectations remain anchored – and it makes more sense to base policy decision on expectations of future inflation over current levels of inflation. For reference, the 5-year breakeven rate is around 2.4% and as the RBS said in their October statement, “Medium-term inflation expectations remain well anchored, and it is important that this remains the case”.
In a nutshell, whilst inflation expectations continue to behave then the RBA are in no rush to hike rates aggressively. Cash rate futures currently imply a 68% chance of a 25bp hike, and have fully priced in a 3% cash rate by their December meeting (although two meetings of 25bp would take rates to 3.1%).
So from a policy perspective, tomorrow’s inflation report is unlikely to change the course of the RBA’s direction. Although if prices come in hotter than expected (like we saw with New Zealand last week) it could send the Aussie higher as it places pressure on the RBA to hike more aggressively. Not that they want to, or likely will anyway - especially as wage growth remains relatively tame compared to inflation.
AUD/USD 1-hour chart:


The Aussie has been confined to a range over the past two weeks. This has made it frustrating for breakout trader, but a delight for range traders. It does not come as a huge surprise that prices have held above the 2020 (close) low, due to the significance of the level. And the longer it holds as support, the higher the odds favour a break higher (in theory). But until we see a decent break of its current range, bears will likely be tempted to fade into rallies into resistance and bulls seek to buy dips around support.
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.