



Base Metals Bounce on Supply Issues
Natalie Scott-Gray discusses the importance of Peru’s reopening of key mining corridor after a period of significant political volatility: the countries mines are responsible for 12% of global copper output, or 2.8 million tons in 2023; in addition, Peru produces significant lead, zinc, tin, and silver.
Share this:
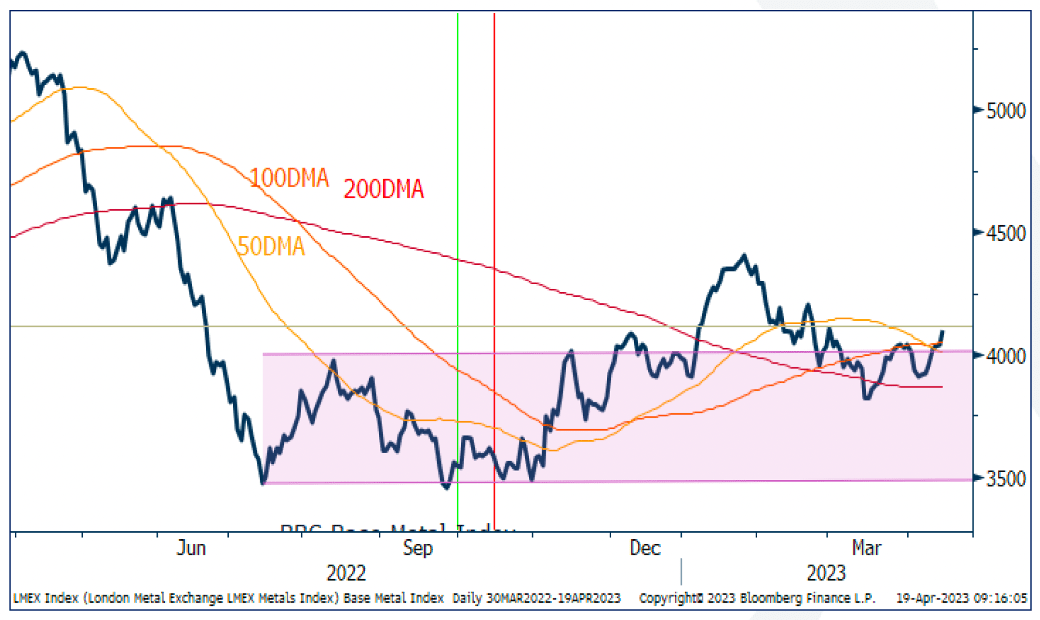
Base metal prices are rallying on South-East Asian demand and China’s economic rebound, coupled with sporadic supply shocks, most notably in Copper and Tin. We expect this price action to continue, exemplified by the performance of the London Metal Exchange (LME) Index, which looks to be on verge of a technical breakout.
Chinese growth is a key driver for metals demand. China’s first quarter gross domestic product grew 2.2% from the previous quarter and 4.5% year-on-year in the first quarter of this year, beating analyst expectations of 4% growth. Our economist expect Chinese GDP growth to reach an annualized rate of growth in 8% in Q2.
London Metal Exchange (LME) Price Index
Source: Bloomberg, StoneX.
Copper and Tin face supply side problems
Copper supply has suffered from Chile’s well publicized production disruptions. Chile is the top copper producer in the world with 29 percent of global copper production. The country’s annual copper output has fallen continuously over the last four years, with 2022 production at its lowest level since 2011, down by 0.9% on a year-to-date annualized basis.
Now copper production costs face political risks. A draft bill to reduce the working week to 40 hours from 45 hours, with the need for overtime payments, was approved in April 2023. Given the need for mines to work continuously, in which workers operate on 12-hour shifts, companies will be forced to pay workers at a higher rate (for the extra hours), raising production costs. Furthermore, Chilean Mining Minister Mario Marcel failed to cap the total tax burden for copper producing companies at 50%, with a final vote being delayed to May.
Tin supply is threatened by Myanmar’s Central Economic Planning Commission ordering a total tin exploration, mining, processing and operations halt, “in order to protect the remining tin resources.” While the country may not follow through with this hardline decision, the country is responsible for 40,500 tonnes of tin ore production, or around 13% of global mine output, returning for growth output in 2022 for the first time since 2017.
The London Metal Exchange’s Tin price jumped 9.2% on this news, to $27,160 per tonne, its highest level since February 2023, but has since fallen back to $27,082. This will hit China, which reportedly imported 62% of its total tin concentrate from Myanmar in 2022. On Monday the tin price hit the Shanghai Futures Exchange 10.5% daily limit on price movements.
Based on analysis by Natalie Scott-Gray, Senior Metals Analyst.
Contact: [email protected]
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.