



Can natural gas break to a new high, or is it just hot air?
Natural gas has seen another strong rally, although lower oil prices yesterday saw it falter just beneath a key level of resistance, leaving clues of near-term exhaustion.
Share this:

During a joint press conference with the European Commission President two weeks ago, Joe Biden announced a plan to “reduce Europe’s dependence on Russian energy”. This is all well and good, but it remains debatable as to whether they replenish the gap left if they cease to use Russian oil by a large enough margin to not see prices skyrocket.
Russia currently supplies roughly 40% of Europe’s gas. And Russia threatened to turn off the gas tap if the West continues to sanction Russia due to the invasion of Ukraine. Clearly, this puts Europe in a tight spot and literally in short supply of an adequate energy supply if they simply ban Russia’s imports (or Russia stops exporting).
Replacing Russian energy is not so easy
The joint venture with the US and EU aims to reduce any such shortfall by setting a goal to deliver 15 billion cubic meters (BCM) of LNG (liquified natural gas) to the EU this year. This goal would then move up to 55 bcm by 2030. Russia currently supplies around 155 bcm per year, their current goal (if achieved) accounts for just 9.6% of what Russia currently supplies. That’s a big shortfall.
Furthermore, LNG experts have warned that weather is a key factor to where LNG ends up. If Asia experiences another cooler winter then the 15 bcm goal appears unrealistic, let alone the 50 bcm target further out. Still, the IEA (International Energy Agency) estimate they can source around 20 bcm of LNG (liquified natural gas) across global markets which might bump it up to 35 bcm. Yet even then it only accounts for around one fifth of the Russian supply, and this shortfall is a key reason as to why prices have continued to rally.
However, it’s not all about gas as oil plays a big part. And yesterday the IEA announced that 31 of its member nations are set to release 120 million barrels of oil from emergency reserves to counter tightening supply, 60 of which will come from the US. This saw oil prices fall around -5% yesterday and weigh broadly on the energy sector. In turn, natural gas futures have stalled at a critical level.
Natural gas falters at key resistance
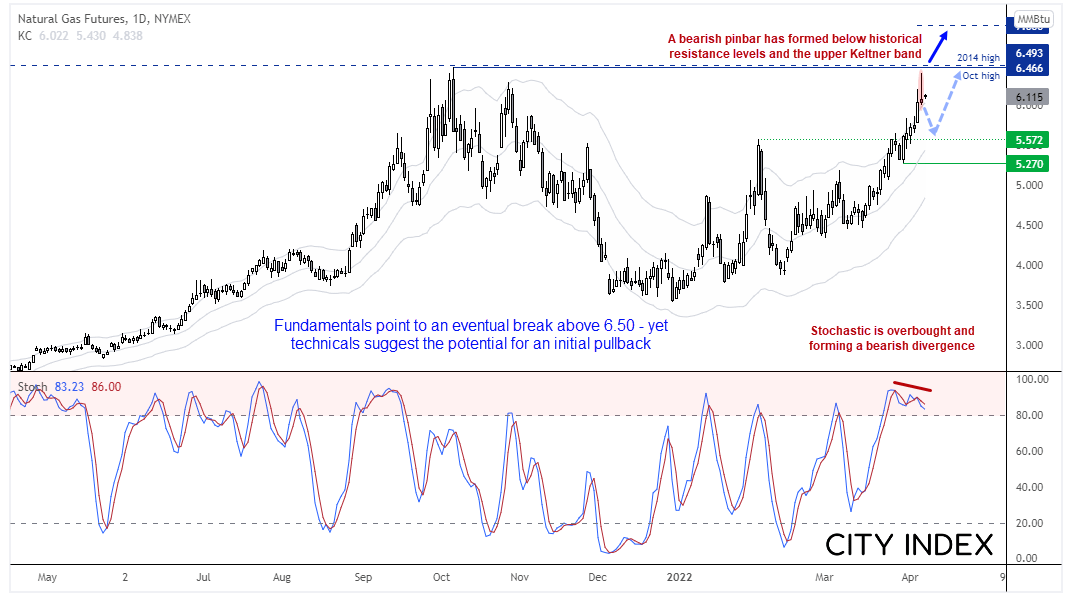
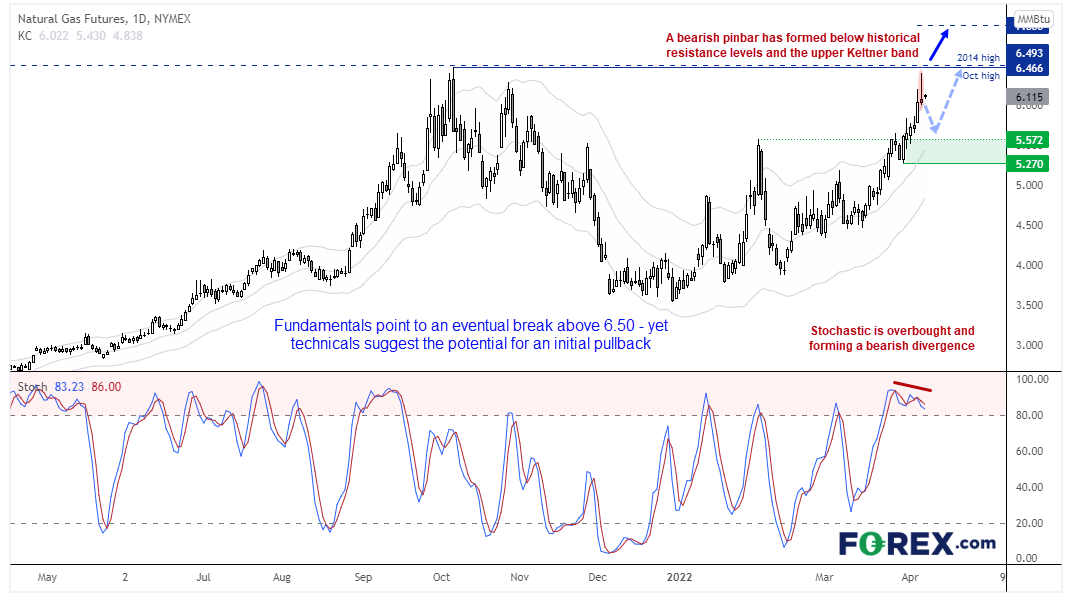
We can see on the daily chart that natural gas prices have regained bullish momentum since the middle of March. Yet news of the IEA flooding the market with oil helped natural gas reverse form its 6-month high and close the day with a bearish pinbar. The candle also faltered as its upper Keltner channel, whilst the stochastic oscillator is both oversold and producing a bearish divergence with prices. But more importantly, the rally has stalled just beneath the October high (6.466) and February 2014 high (6.493) which makes it an important pivotal level over the near-term.
Ultimately there are several clues that the upside move is exhausted over the near-term, just beneath a key resistance level. As things stand the fundamentals favour an eventual break above 6.50 over the coming week/s against the backdrop of no clear plan for Europe to replenish any Russian energy shortage. But we know that oil and natural gas can correlate on a daily basis, so weaker oil prices could help natural gas correct before its next leg higher. A break beneath yesterday’s low confirms the bearish pinbar and paves the way for a retracement. But we would then seek evidence of a swing low around or above support levels to anticipate the end of any such correction (however minor it may be).
A threat to its uptrend would likely require a solid plan to fully replace Russian oil. But until that happens, an eventual break above 6.50 appears likely.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.