



Covid19 Drug Hopes and Rebounding Oil Supports Stocks ECB In Focus
The FTSE is pointing to a strong start on the open as sentiment remains upbeat on signs of progress in treating coronavirus and as oil continues its advance.
Share this:

The FTSE is pointing to a strong start on the open as sentiment remains upbeat on signs of progress in treating coronvirus and as oil continues its advance.
Optimism continues to drive the markets this time driven by encouraging results from a covid-19 treatment trial. Comments by Anthony Fauci, that Gilead’s antiviral remdesivir will become the standard care for coronavirus infections after early results from a trial showed hat it aided a speedy recovery. Any encouraging news on covid-19 drugs or vaccines will boost sentiment. The market is fully aware that any cure or prevention will see economies bounce back to pre-coronavirus form rapidly. Even without a cure, the market is happy to settle for control of the spread of coronavirus. With regards to the spread, we are definitely in a better place than a month ago, although it is still far to early to sing any victory song.
Oil extends gains
Oil prices continue to rise on Thursday, building g on big gains from the previous session amid optimism that the crude glut isn’t as bad as first thought and amid signs that fuel demand is slowing stating to pick up as states and countries ease out of lock down. Crude for June delivery jumped 22% in the previous session and is trading an additional 13% higher in early trade on Thursday, having hit a high of $17.73 per barrel.

Oil prices continue to rise on Thursday, building g on big gains from the previous session amid optimism that the crude glut isn’t as bad as first thought and amid signs that fuel demand is slowing stating to pick up as states and countries ease out of lock down. Crude for June delivery jumped 22% in the previous session and is trading an additional 13% higher in early trade on Thursday, having hit a high of $17.73 per barrel.
Whilst we still expect volatility in the oil market, there is a sense that the worst is over and that there is at least a floor in place. With countries gradually reopening, demand will continue to grind higher. The biggest risk for the price of oil would be a second wave of infections forcing countries back into lock down. Germany faces the prospect of having to restore stricter lockdown measures as its number and rate of coronavirus infections grew again. Whilst this risk remains very real we can expect to see process oscillate around these levels. Any moves to increase storage in he US, or further output cuts by OPEC could see the floor that is forming raised.
EZ GDP & ECB under the spotlight
Today is a busy day on the economic calendar with a slew of data from the eurozone due, including German retail sales, Eurozone inflation and German unemployment numbers. However, the most closely watched with be Eurozone GDP figures and the ECB monetary policy announcement.
EUR/USD is holding steady ahead of Eurozone Q1 GDP, which is forecast to reveal a -3.3% contraction, following 1% growth in Q4 2019. The data will reflect the beginning of lock down which started in Italy in the second week of March. Recently data has had a tendency to surprise to the downside so a weaker reading could well be on the cards.
Following the failure of EU leaders to agree to an economic recovery plan for the bloc, the ball is firmly back in the ECB’s court. The ECB are expected to expand the PEPP QE programme, most likely with “fallen angels” and possibly going as far as the Fed to include junk bonds. Expectations are rising high. Failure to act could drag on the Euro dragging it back towards $1.08
The FTSE is pointing to a strong start on the open as sentiment remains upbeat on signs of progress in treating coronvirus and as oil continues its advance.
Optimism continues to drive the markets this time driven by encouraging results from a covid-19 treatment trial. Comments by Anthony Fauci, that Gilead’s antiviral remdesivir will become the standard care for coronavirus infections after early results from a trial showed hat it aided a speedy recovery. Any encouraging news on covid-19 drugs or vaccines will boost sentiment. The market is fully aware that any cure or prevention will see economies bounce back to pre-coronavirus form rapidly. Even without a cure, the market is happy to settle for control of the spread of coronavirus. With regards to the spread, we are definitely in a better place than a month ago, although it is still far to early to sing any victory song.
Oil extends gains
Oil prices continue to rise on Thursday, building g on big gains from the previous session amid optimism that the crude glut isn’t as bad as first thought and amid signs that fuel demand is slowing stating to pick up as states and countries ease out of lock down. Crude for June delivery jumped 22% in the previous session and is trading an additional 13% higher in early trade on Thursday, having hit a high of $17.73 per barrel.
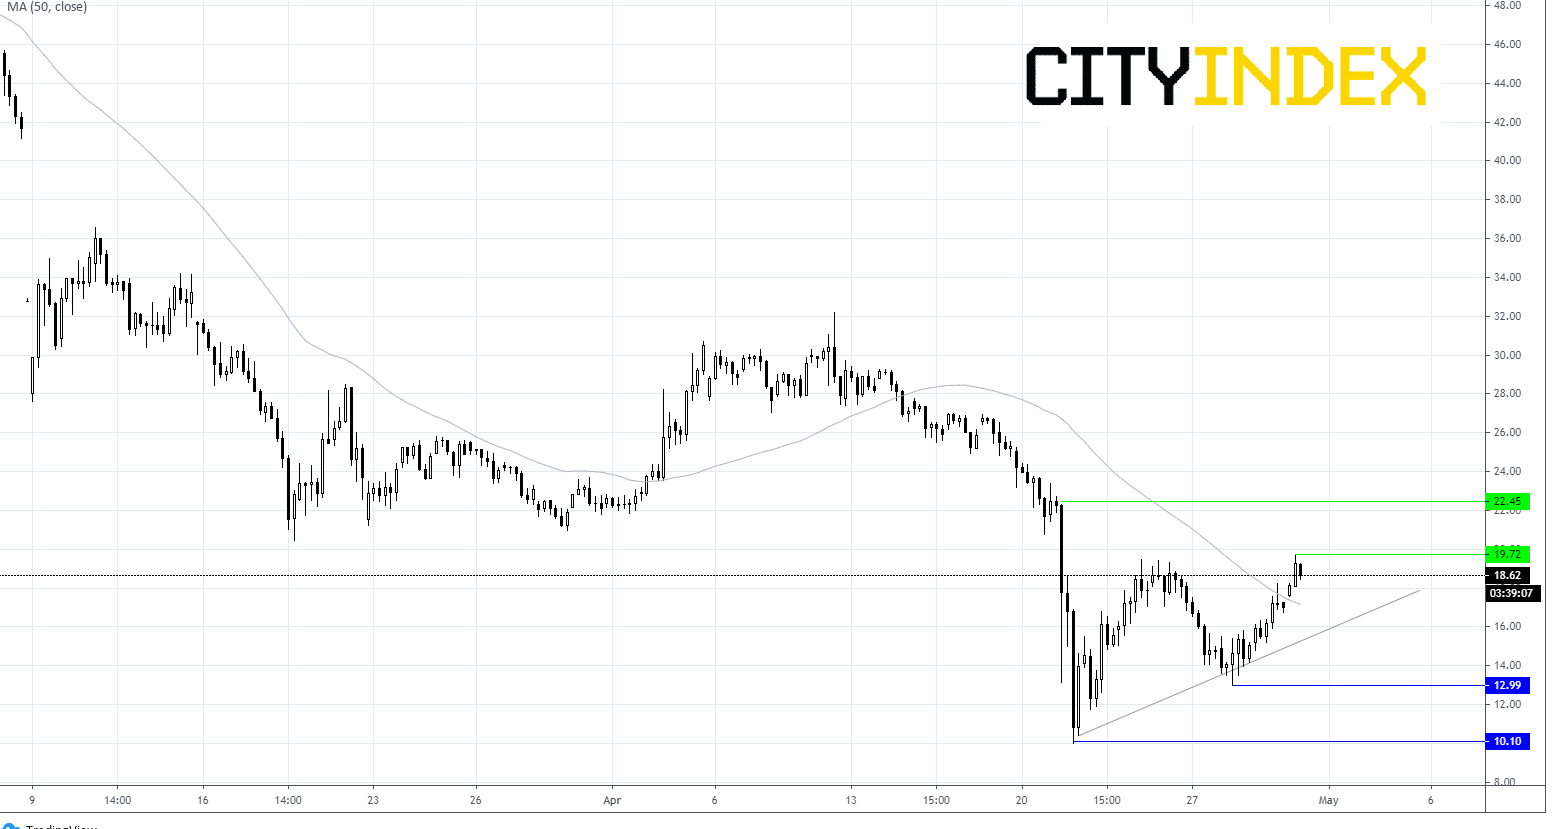
Oil prices continue to rise on Thursday, building g on big gains from the previous session amid optimism that the crude glut isn’t as bad as first thought and amid signs that fuel demand is slowing stating to pick up as states and countries ease out of lock down. Crude for June delivery jumped 22% in the previous session and is trading an additional 13% higher in early trade on Thursday, having hit a high of $17.73 per barrel.
Whilst we still expect volatility in the oil market, there is a sense that the worst is over and that there is at least a floor in place. With countries gradually reopening, demand will continue to grind higher. The biggest risk for the price of oil would be a second wave of infections forcing countries back into lock down. Germany faces the prospect of having to restore stricter lockdown measures as its number and rate of coronavirus infections grew again. Whilst this risk remains very real we can expect to see process oscillate around these levels. Any moves to increase storage in he US, or further output cuts by OPEC could see the floor that is forming raised.
EZ GDP & ECB under the spotlight
Today is a busy day on the economic calendar with a slew of data from the eurozone due, including German retail sales, Eurozone inflation and German unemployment numbers. However, the most closely watched with be Eurozone GDP figures and the ECB monetary policy announcement.
EUR/USD is holding steady ahead of Eurozone Q1 GDP, which is forecast to reveal a -3.3% contraction, following 1% growth in Q4 2019. The data will reflect the beginning of lock down which started in Italy in the second week of March. Recently data has had a tendency to surprise to the downside so a weaker reading could well be on the cards.
Following the failure of EU leaders to agree to an economic recovery plan for the bloc, the ball is firmly back in the ECB’s court. The ECB are expected to expand the PEPP QE programme, most likely with “fallen angels” and possibly going as far as the Fed to include junk bonds. Expectations are rising high. Failure to act could drag on the Euro dragging it back towards $1.08
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.