






Crude Oil Week Ahead: China, OPEC, and US Inflation
Crude Oil Week Ahead: Crude oil remains on a bullish track this year, reaching 4-month highs. Next week, key inputs such as Chinese economic data, shifts in Fed rate expectations, and OPEC and IEA monthly reports are expected to shape the still range-bound direction of oil prices.
Share this:
Article Outline
- Key Events: Chinese Data, OPEC Monthly Report, US CPI, and Winter Demand
- Technical Analysis: USOIL (3-Day Time Frame)
- Technical Analysis (TA) Tip: RSI Patterns
Oil’s 2025 Uptrend
The 2025 uptrend for crude oil was fueled initially by expectations of Chinese economic growth, further supported by a sharp increase in winter fuel demand. Oil prices climbed back toward October 2024 highs after stronger-than-expected non-farm payroll results on Friday, which added 256,000 jobs and amplified inflation concerns for 2025.
Next week’s U.S. CPI data is expected to influence oil market volatility further, with implications for Fed rate expectations and monetary policy in 2025. Positive oil hedges remain tied to unresolved geopolitical factors, Chinese economic metrics, and reports from OPEC and the IEA.
OPEC Monthly Report
The first monthly oil reports for 2025 are set to be released this week, following the December 2024 Monthly Oil Market Report (MOMR), which reduced the 2025 demand growth forecast to 1.45 million barrels per day (bpd). This revision reflected weaker demand in China and the Middle East.
However, the outlook for 2025 could shift with potential Middle Eastern reforms and notable Chinese economic stimulus. More data on geopolitical resolutions and China’s economic metrics is required to support a more optimistic forecast. The current sentiment remains cautious, with upside potential dependent on key levels and the materialization of these resolutions.
Chinese Economic Data
New Chinese loan data, expected between January 13 and 15, hovers near decade lows as markets await signs of improvement. Foreign Direct Investments, also scheduled for next week, are similarly weak, near 2009 levels, with critical hopes for recovery. Loan prime rates are expected on January 20, coinciding with Trump’s return to the White House.
The People’s Bank of China (PBOC) announced moderately loose monetary policies for 2025, and their implementation will be closely monitored alongside loan prime rates. Significant stimulus or improvement in Chinese economic conditions could further bolster oil market gains, while continued stagnation may align with oil’s 2-year bearish trend.
Technical Analysis: Quantifying Uncertainties
Crude Oil Week Ahead: 3-Day Time Frame
Source: Tradingview
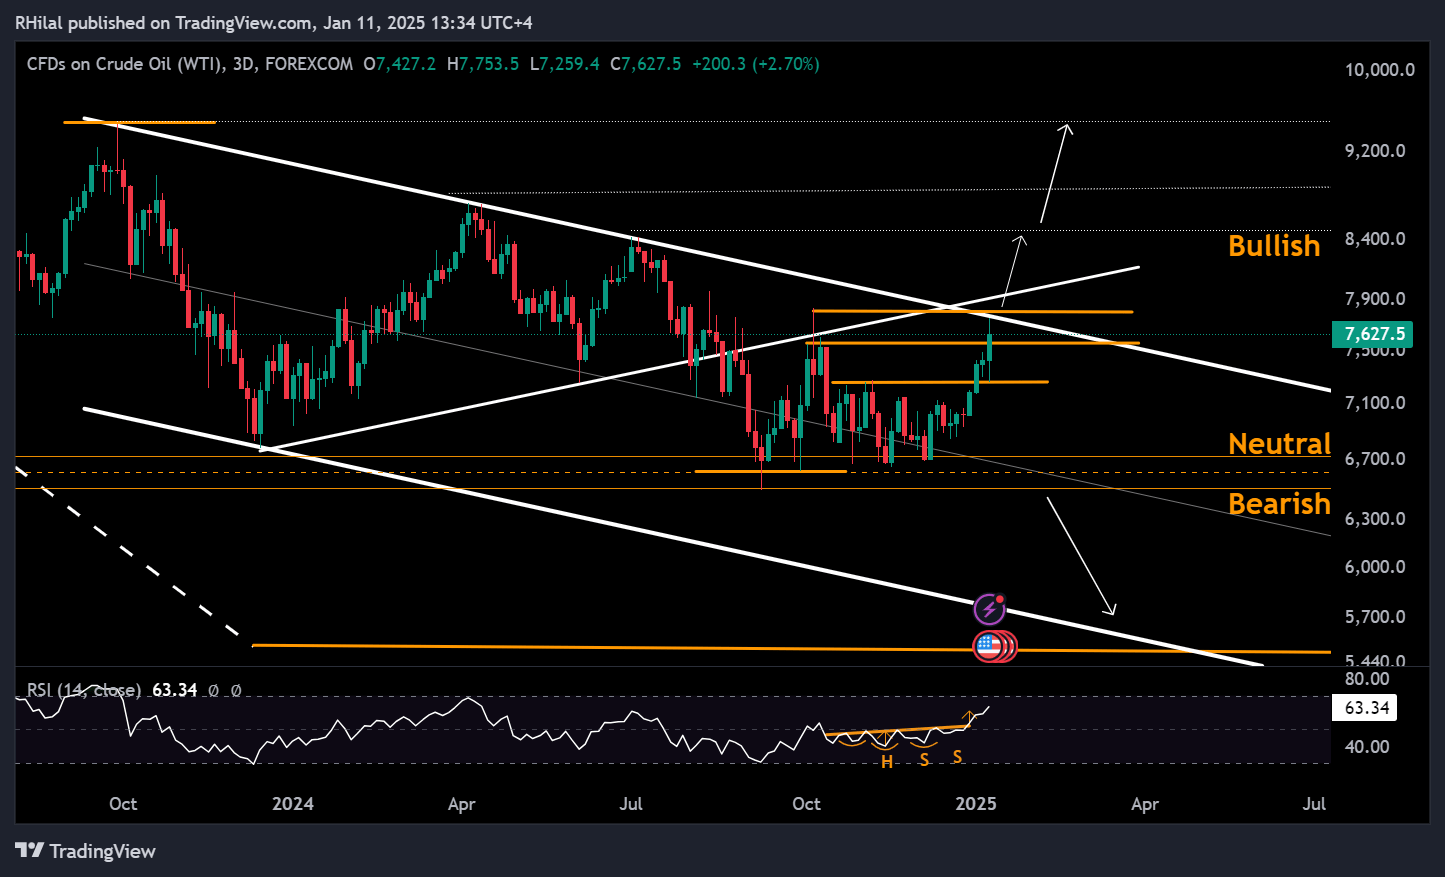
Oil prices recently retested the upper border of the down trending channel at the $77.50 high following stronger-than-expected U.S. non-farm payroll data. As long as prices remain below the triangle pattern and within the down trending channel, the outlook remains neutral to bearish.
A firm close above $78.30 could strengthen bullish sentiment, potentially driving oil prices back into the $80 range, with key resistance levels at $84, $87, $90, and $95. On the downside, short-term support is near $72, with further support at $68 and $64. A confirmed bearish trend continuation could target lower levels around $55 and $49.
Economic developments in China and the U.S., alongside global geopolitical factors, remain critical to determining oil’s directional sustainability. Policies stemming from Trump’s presidency and OPEC decisions carry significant weight, necessitating alignment among multiple factors for a clearer directional outlook.
Technical Analysis (TA) Tip: RSI Patterns
Crude Oil Week Ahead: 3-Day Time Frame
Source: Tradingview
Similar to identifying chart patterns and establishing breakout directions and targets, RSI trends can offer valuable insights. Forecasting RSI trends helps predict momentum targets between extreme levels, reversals, and continuation patterns, providing an additional layer of analysis for market direction.
Example: the breakout from the inverted Head and Shoulders continuation pattern on the RSI aligned with the oil’s 2025 uptrend towards October 2024 highs near 78$ per barrel.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves
You Tube: Forex.com
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.


Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.