



Crude Oil Weekly Outlook: Is Russia the Next Risk Premium for Oil Prices?
Crude Oil Weekly Outlook: Will attacks on Russian energy infrastructure offset oversupply risks? Key support, resistance, and price scenarios for oil this week.
Share this:
Crude oil prices have largely unwound the geopolitical premium built during the Middle East conflict, returning close to pre-conflict levels. While the broader trend remains bearish due to oversupply concerns, oversold technical conditions and renewed attacks on Russian energy infrastructure could trigger a short-term rebound. Here are the key scenarios to watch this week.
Crude oil markets remain focused on fading geopolitical risks and growing supply surplus expectations heading into year-end. As shipping through the Strait of Hormuz normalizes, inventories recover from an 8-million-barrel draw to approximately a 3-million-barrel draw, Gulf exports resume, and OPEC+ continues increasing production, adding another 188,000 barrels per day in July, the market is increasingly pricing in abundant supply.
However, an emerging risk has begun attracting attention.
Extended attacks on Russian energy infrastructure and oil refineries have created localized supply shortages within Russia, raising questions about potential disruptions to refined product availability and exports if attacks intensify. According to Reuters, refinery disruptions have, at times, reduced Russian refining activity by nearly 20%, contributing to domestic fuel supply stress.
Meanwhile, crude oil has declined more than 40% from its 2026 highs, leaving daily momentum indicators in oversold territory. While this supports the case for a short-term rebound, a sustained return toward this year's highs would likely require a fresh geopolitical catalyst, such as:
- Renewed disruptions to Strait of Hormuz shipping.
- Material damage to major Russian export terminals.
- Black Sea shipping disruptions.
- Large-scale production outages.
- New sanctions that materially reduce Russian exports.
Conversely, if oversupply risks continue to build and global demand weakens further—particularly from China—the bearish outlook could strengthen. The International Energy Agency (IEA) expects global oil demand growth to slow to around 1.1 million barrels per day this year. Under that scenario, crude prices could gradually realign with the $55 area, consistent with my second-half 2026 crude oil outlook. Crude Oil Price Forecast H2 2026: Will Oversupply Push WTI Back to $55?
I also discuss the latest crude oil technical outlook in my daily MENA Market Call.
Register here to join the next session.
Another headwind for oil remains lingering stagflation concerns following the Middle East conflict. Slower global growth alongside persistent inflation pressures could continue weighing on energy demand.
The latest US Non-Farm Payrolls report reinforced those concerns, with job creation slowing sharply from 129,000 to 57,000. While part of the weakness may prove seasonal, it remains an important indicator to monitor as softer labour markets could eventually translate into weaker oil demand if economic activity continues to cool.
Crude Oil Weekly Outlook: Weekly Time Frame – Log Scale
Source: Trading view
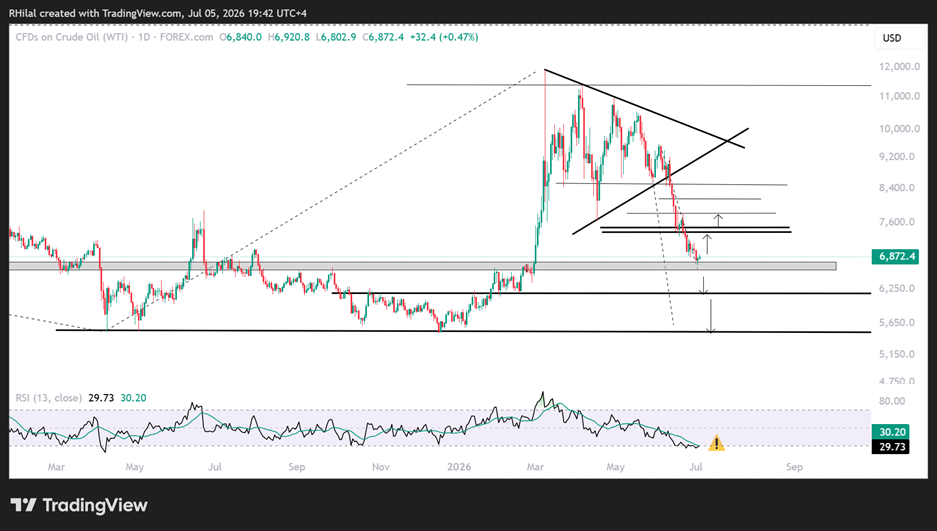
WTI crude oil continues to hold above the $66.50 area, a critical technical support that presents near-term rebound risks. This level aligns with:
- Multi-year support dating back to 2019.
- The 78.6% Fibonacci retracement of the 2026 rally.
- Oversold daily momentum conditions last seen in 2025, when crude traded near the $55 low.
- Renewed geopolitical risks surrounding Russian energy infrastructure.
Key Resistance Levels
Should the rebound extend, the following resistance levels will be closely watched:
- $73.50 – 23.6% Fibonacci retracement of the June–July decline.
- $74.60 – 27.2% Fibonacci retracement.
- $77.80 – 38.2% Fibonacci retracement (high-probability pullback zone).
- $81.20 – 50% Fibonacci retracement.
- $84.80–85.00 – 61.8% Fibonacci retracement (high-probability pullback zone).
Key Support Levels
The broader bearish trend remains intact following the breakdown below the March–June consolidation range.
If $66 fails to hold, downside pressure could initially target the $61 support area before any meaningful rebound develops. A decisive break below $61 would strengthen the case for an eventual move toward the $55 objective outlined in my second-half outlook.
Despite the potential for a near-term technical recovery from oversold conditions, the medium-term trend remains biased to the downside unless a new geopolitical catalyst significantly alters the global supply outlook.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.

Nikkei 225 bear market deepens as volatility surges
The Nikkei has entered a technical bear market following a historic plunge. RSI and ATR stretch readings suggest a bounce may be coming, but history carries a warning for dip buyers.


Nasdaq volatility shock warns against buying too early
An extraordinary sell-off has left Nasdaq 100 futures deeply oversold, but history suggests further downside is common before a sustained recovery takes hold.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.