


DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.
Share this:
EU Market Brief — Friday, 6 November 2026
European equities are under renewed pressure this morning as the global AI-led technology selloff extends into a second day. The DAX is trading close to 26,000.00, down 144 points or 0.55% for the day after opening at 26,150.40 and touching an intraday high of 26,209.80. The index has therefore given back part of Thursday’s late-session recovery and slipped at times back below the psychologically important 26,000 level.
The weakness is broad. The STOXX Europe 600 is down 1.45% at 645.38, France’s CAC 40 has lost 1.11% to 8,114.55, and the UK’s FTSE 100 is 1.57% lower at 10,613.10. The Euro Stoxx 50 is the relative outperformer, up 0.19% at 6,175.20, but that resilience is not enough to offset the broader risk-off tone.
The market digested the midterm elections and is no longer trading the initial relief from the US midterm result. Instead, investors are evaluating the longevity of AI-related capital expenditures, the valuation of technology stocks and the impact of tighter potential regulation on data-centre and semiconductor investment, as the democrats stated.
What drove yesterday’s selloff
Thursday’s session was defined by a sharp rotation away from technology and defence. The STOXX Europe 600 closed 0.38% lower at 654.87, but the damage was much greater beneath the surface: technology stocks fell 3.2% to their lowest level in nearly two months, while defence shares lost 2.6%.
The immediate catalyst was the continuation of the Wall Street technology selloff. The Nasdaq entered correction territory, wiping out an estimated $2.5 trillion in market value, and Asian markets followed lower overnight. That forced European investors to reduce exposure to AI-linked semiconductor, data-centre and industrial-automation names as well.
Oil also turned from tailwind to headwind. Brent crude rose more than 2% on Thursday as markets reassessed the prospects for a resolution in the Iran conflict. For Europe, an energy-importing region, higher oil prices are a direct negative for airlines, logistics, chemicals and consumer-facing businesses.
DAX leaders and laggers
Thursday’s DAX session showed an unusually sharp divide. Zalando, Bayer and Fresenius Medical Care led the index higher, while Rheinmetall, Infineon and Siemens Energy were the main drags.
|
DAX constituent |
Move |
Why it moved |
|
Zalando |
+3.75% |
Strongest DAX performer; consumer-discretionary relief after recent weakness. |
|
Bayer |
+3.65% |
Continued support after its upgraded 2026 profit outlook. |
|
Fresenius Medical Care |
+3.42% |
Defensive healthcare demand attracted rotation away from technology. |
|
MTU Aero Engines |
+3.1% |
Benefited from the broader move out of AI-exposed semiconductors. |
|
Siemens Energy |
+3.1% intraday, later -4.70% |
Early strength reversed as investors reassessed energy-infrastructure and data-centre exposure. |
|
Deutsche Telekom |
-2.9% |
Quarterly earnings rose, but the planned dividend came in below consensus. |
|
Commerzbank |
-2.6% |
Cut its net interest income guidance, weighing on the banking sector. |
|
Siemens Energy |
-4.70% |
Data-centre and energy-infrastructure concerns dominated by the close. |
|
Infineon |
-8.54% |
Semiconductor weakness and AI-capex concerns hit the chipmaker hard. |
|
Rheinmetall |
-16.14% |
Cut its 2026 sales outlook for the second time in three months. |
Why Rheinmetall collapsed
Rheinmetall was the most important single-stock story. The defence group cut its 2026 sales forecast to around €13.2 billion, down from a prior range of €13.7 billion to €14.2 billion, and lowered its operating-margin outlook to about 18.5% from 19%.
The company blamed delays in the Boxer armoured-vehicle programme and slower batch approvals for artillery ammunition. It also said it no longer expected a contract award this year for Germany’s Arminius Boxer vehicle programme.
However, it came at a sensitive moment: investors were already reassessing defence valuations after the Democratic sweep raised questions about the future direction of US defence spending. The result was a 16.1% decline in Rheinmetall and a 2.6% drop across the European defence sector.
Why technology is under pressure
Infineon fell 8.54%, while Soitec dropped 16.7% and Aixtron lost 9.8% across the broader European market. The driver is the fear that a Democratic Congress could slow AI data-centre expansion, tighten regulation and reduce the pace of semiconductor-related capital expenditure.
Germany has a meaningful exposure to industrial automation, energy infrastructure and semiconductor supply chains and therefore influence the DAX. The market is not necessarily pricing in a collapse in AI demand; it is repricing the assumption that AI investment will continue expanding at the same pace regardless of political or regulatory conditions.
Technical picture: 26,000 is the line in the sand
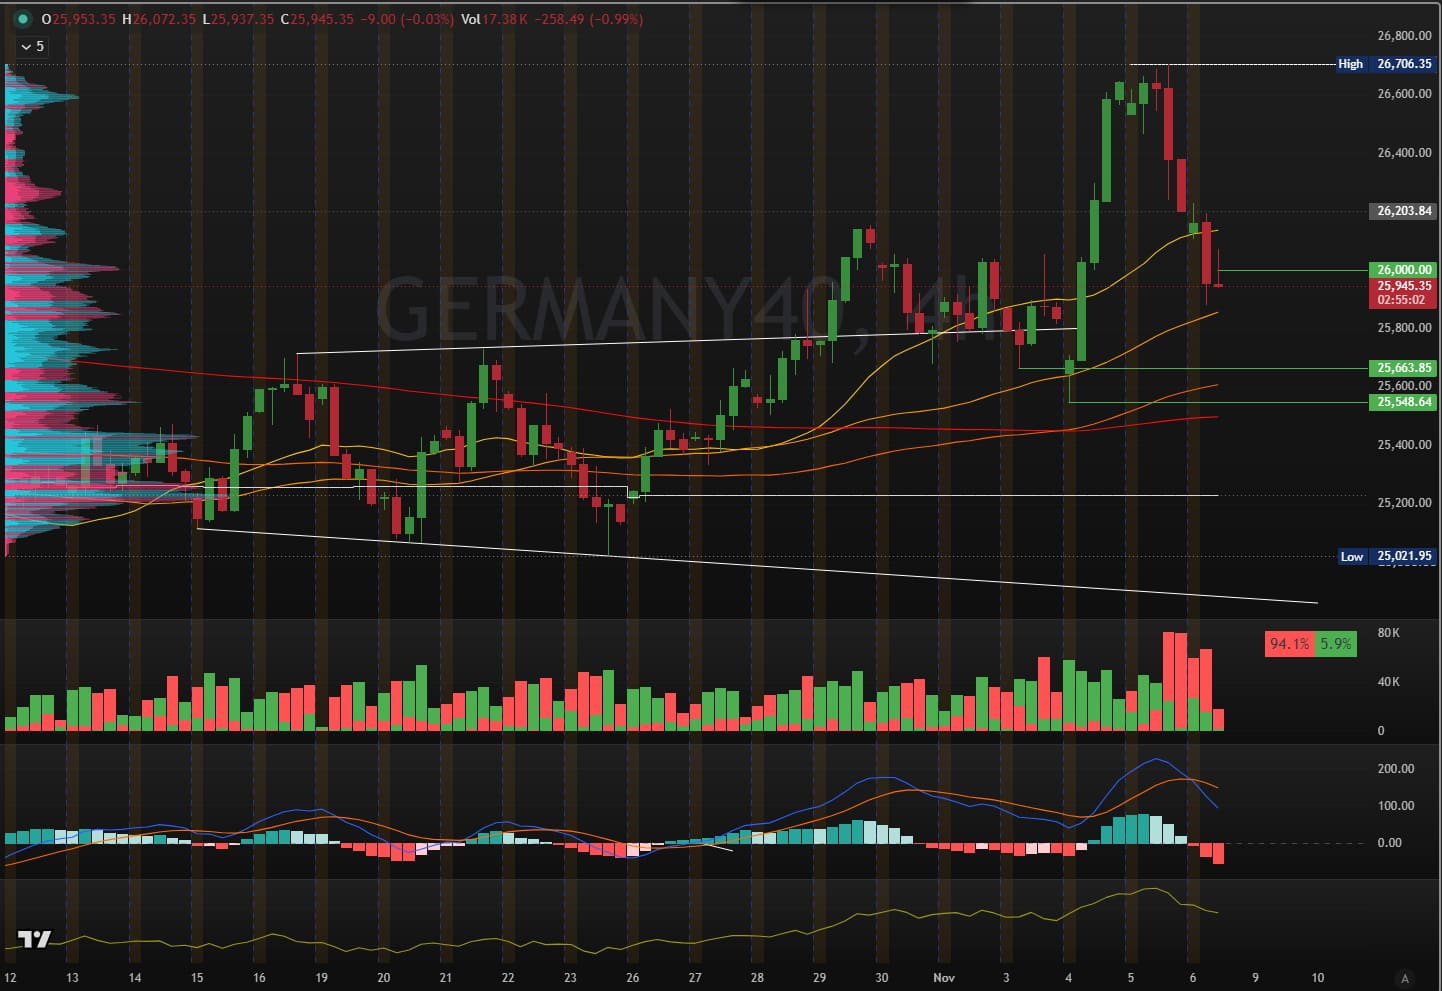
The DAX opened above 26,150, rallied to 26,209.80, then reversed sharply to trade at times below 26,000. That is a bearish intraday reversal and suggests that sellers used the early strength to reduce exposure.
- Immediate support: 25,863.80, this morning’s low.
- Key psychological support: 26,000, now acting as support after the failed breakout.
- First resistance: 26,150.40, this morning’s opening level.
- Major resistance: 26,209.80, today’s intraday high.
- Next major support if 25,863.80 breaks: the 25,700–25,800 area, which was the recovery zone earlier in the week.
The DAX needs to hold 26,000 to neutralise today’s reversal. Until then, the market is vulnerable to further downside, particularly if US technology weakness continues into the European close.
What to watch today
The main macro event is the US jobs report later today. Volatility has already increased ahead of the release, and a stronger-than-expected labour market could reinforce concerns that interest rates will remain higher for longer. A softer report, by contrast, could support bonds and provide some relief for equity valuations.
Oil remains the other key variable. Brent crude recovered above earlier lows after the initial post-election selloff, and renewed geopolitical uncertainty would be a further drag for European airlines, logistics and consumer-facing companies.
For the DAX, the focus should remain on whether technology and semiconductor weakness stabilises. If Infineon and other AI-linked names find buyers at lower levels, the index could recover toward 26,000. If the selloff broadens, the next support zone near 25,800 becomes the more relevant test.
Summary
The market appears in a risk-reduction phase, not yet a confirmed downtrend. The appropriate response is selective rather than defensive across the board.
- AI and semiconductor exposure: Infineon, Siemens Energy and other data-centre-linked names remain vulnerable until the AI-capex narrative stabilises.
- Defense: Rheinmetall: The guidance cut is company-specific, but can amplify sector-wide defence anxiety.
- Oil and US yields: Both are critical inputs for European equity valuations and any increase can pressure the DAX.
Earning: Friday, November 6
Moderna (NASDAQ: MRNA), Before Open: The biotech giant reports earnings after a transformational period for the company. Earlier this year, its personalized cancer vaccine, developed in partnership with Merck, delivered strong results in a late-stage melanoma study, triggering a massive rally in the stock. Shares have surged roughly tenfold over the past year, lifting Moderna’s valuation close to $100 billion. Wall Street expects revenue of around $890 million and a loss of approximately $1.35 per share, but investors are likely to focus far more on updates from the company's vaccine and oncology pipeline than on the headline numbers.
Vistra (NYSE: VST), Before Open: The Texas-based power generator enters earnings season under pressure after shares tumbled by double digits following political concerns over future data center expansion in Texas and a subsequent downgrade from KeyBanc. Analysts forecast third-quarter earnings per share of roughly $3, though attention will center on management’s updated 2027 outlook. Commentary on electricity demand from AI-driven data centers, particularly in Texas, could prove critical not only for Vistra’s outlook but also for broader sentiment across the AI infrastructure and power-generation sectors.
Trade safe.
Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.
Nikkei 225 bear market deepens as volatility surges
The Nikkei has entered a technical bear market following a historic plunge. RSI and ATR stretch readings suggest a bounce may be coming, but history carries a warning for dip buyers.

Nasdaq volatility shock warns against buying too early
An extraordinary sell-off has left Nasdaq 100 futures deeply oversold, but history suggests further downside is common before a sustained recovery takes hold.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.