



DAX Breaks to New Highs — Now Earnings Must Deliver
The market is looking through softer economic data and focusing instead on easing rate expectations, stable oil prices, and the upcoming earnings season. The weaker-than-expected US labor market report has reduced pressure for further rate hikes, while the DAX has technically broken out to new all-time highs. The next leg higher, however, requires confirmation from corporate earnings—not macro optimism.
Share this:
Summary
Markets are entering the trading day with cautious optimism. While Wall Street closed mixed and technology stocks remained under pressure, a weaker-than-expected U.S. labor market report helped stabilize interest rate expectations. European futures point to a slightly positive open, although lower trading volumes and heightened volatility are expected due to today's U.S. Independence Day holiday.
Monetary policy remains the primary market focus. Despite signs of slowing momentum in the U.S. labor market, Fed Chairman Kevin Warsh reiterated the Federal Reserve’s commitment to fighting inflation. At the same time, the weaker employment data led markets to push back expectations for any further rate hikes.
Geopolitics also remains an important factor. The Strait of Hormuz remains open to international shipping and negotiations between the United States and Iran are continuing, helping to keep upward pressure on oil prices contained for now.
Equity Markets
U.S. equity markets delivered a mixed performance. The Dow Jones reached a fresh record high, while the Nasdaq and S&P 500 closed broadly unchanged or slightly lower. Profit-taking in semiconductor and technology stocks once again weighed on sentiment, although market breadth remained positive and defensive sectors such as healthcare, consumer staples, and utilities outperformed.
Asian markets were firmer. South Korean technology stocks led gains after Samsung Electronics and SK Hynix posted strong advances. Chinese equities also benefited from a better-than-expected services PMI reading.
European futures indicate a modestly positive start to trading. However, the U.S. holiday is expected to result in lower liquidity and potentially larger price swings.
DAX Technical Analysis – Daily Chart
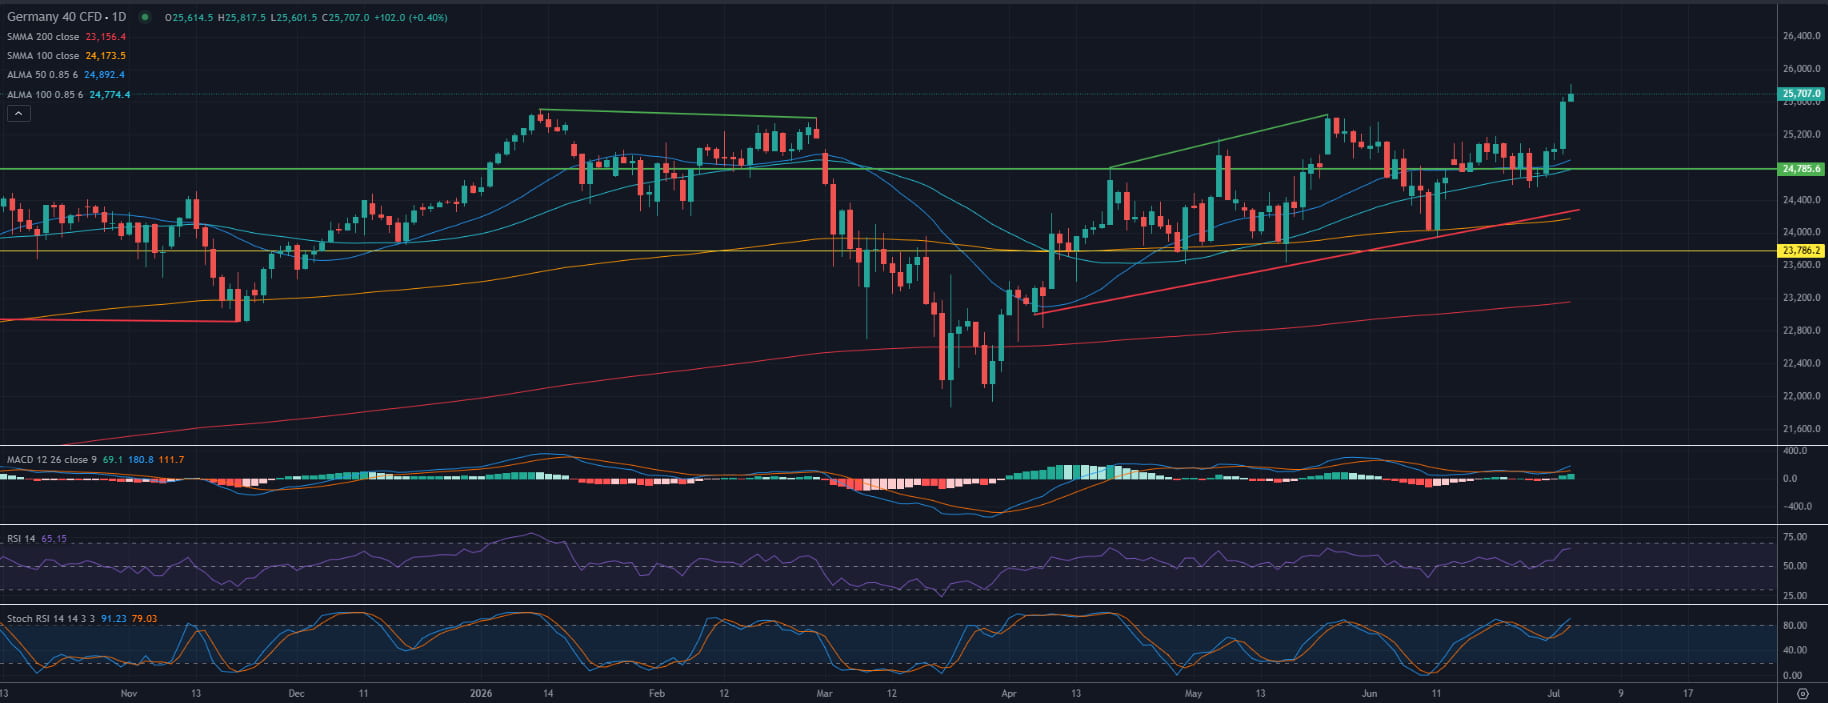
The DAX (Germany 40) remains in a strong uptrend, trading around 25,707 after breaking out to a new all-time high above the 25,300–25,400 resistance zone. The index continues to trade well above its 50-, 100-, and 200-day moving averages, confirming a bullish trend across multiple timeframes. Momentum indicators also support the move: MACD is turning higher again, RSI is near 65 and remains constructive without being overbought, while Stochastic RSI is accelerating toward its upper extreme zone. From a technical perspective, the former breakout area around 25,300 remains the key support level, followed by 24,785. As long as these levels hold, the market structure points toward a continuation of the rally toward 26,000 and beyond. Only a sustained move back below 25,300 would increase the risk of a deeper correction toward the rising 50-day moving average.
Fundamentally, the advance continues to be supported by a global risk-on environment, expectations of an ongoing central-bank easing cycle, and strength across international equity markets. European indices are also benefiting from inflows into technology and AI-related stocks. In the coming days, German industrial and trade data, PMI releases, and key U.S. labor market and inflation reports will likely drive direction. Softer inflation data or signs of slowing economic growth could reinforce expectations for further monetary easing and provide additional support for the recent breakout. Conversely, stronger-than-expected inflation or growth data could push bond yields higher and trigger short-term profit-taking near record highs. As long as key support levels remain intact, the combination of positive technicals and a supportive macro backdrop continues to favor the bulls.
Fixed Income, FX & Commodities
The U.S. dollar weakened modestly following the softer-than-expected labor market report. Investors scaled back expectations for further Federal Reserve tightening, while U.S. Treasury yields stabilized.
The euro gained slightly against the dollar. ECB President Christine Lagarde defended the June rate increase and emphasized that there is still little evidence of significant second-round inflation effects.
Oil prices were little changed. Ongoing U.S.-Iran talks and confirmation that the Strait of Hormuz remains open prevented a renewed geopolitical risk premium from developing. Gold extended its recent rally, benefiting from dollar weakness and declining rate expectations.
Key Themes
Fed Remains Restrictive: Fed Chairman Kevin Warsh reiterated that price stability remains the central bank’s top priority and that monetary policy decisions will remain independent of political pressures. At the same time, disappointing labor market data reduced expectations for further rate hikes. This combination of slowing economic momentum and restrictive monetary policy is likely to shape market conditions in the weeks ahead.
Germany Focuses on Investment: The German government approved a reform package consisting of 34 measures aimed at boosting investment in artificial intelligence, semiconductors, battery technology, and data centers while reducing bureaucracy. In the short term, this may improve business sentiment, while the medium-term impact will depend on whether private-sector investment picks up sustainably.
Earnings Season Moves into Focus: Following an exceptionally strong first quarter, investor attention is increasingly shifting toward the upcoming U.S. earnings season. Analysts continue to expect robust profit growth, particularly in the technology and semiconductor sectors. With many investors still positioned defensively, positive earnings surprises could provide further upside for equity markets.
Outlook
With U.S. markets closed for the holiday, trading volumes are expected to be significantly lower, increasing the potential impact of individual news events.
Bullish Scenario: Continued diplomatic progress in the Middle East, stable oil prices, and expectations of less restrictive monetary policy support further gains in risk assets.
Base Case: Markets are likely to consolidate after the U.S. labor market report and gradually shift their focus toward the upcoming U.S. earnings season.
Bearish Scenario: A renewed escalation in the Middle East or continued weakness in the technology sector could temporarily interrupt the recent strong equity rally.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.


S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.