

DAX Faces Fresh Pressure from Tech Rout and Middle East Risks
The DAX has come under renewed pressure as another technology-led sell-off on Wall Street undermines global risk sentiment. While the index remains above key October lows, the recent recovery is losing momentum as investors reassess AI valuations, rising energy prices and escalating geopolitical risks. With oil climbing and major technology stocks facing renewed selling pressure, the focus has shifted back to support levels rather than fresh highs.
Share this:
The DAX 40 is under renewed selling pressure on Friday, 23 October 2026, following Thursday’s decline potentially led by another technology-led sell-off on Wall Street. The index is currently trading around 25,260, down approximately 0.5% for the day. The key near-term test is whether buyers can gain back the 25,370 region. However, a break lower would open up the 25,175 level (rising trendline) followed by 25,070 (previous cycle Weekly low) and then the psychological 25,000 level.
DAX 40 Technical Analysis: Technology Sell-Off and Geopolitical Risks Weigh on European Markets
Friday, 23 October 2026
Daily chart: The recovery is losing momentum
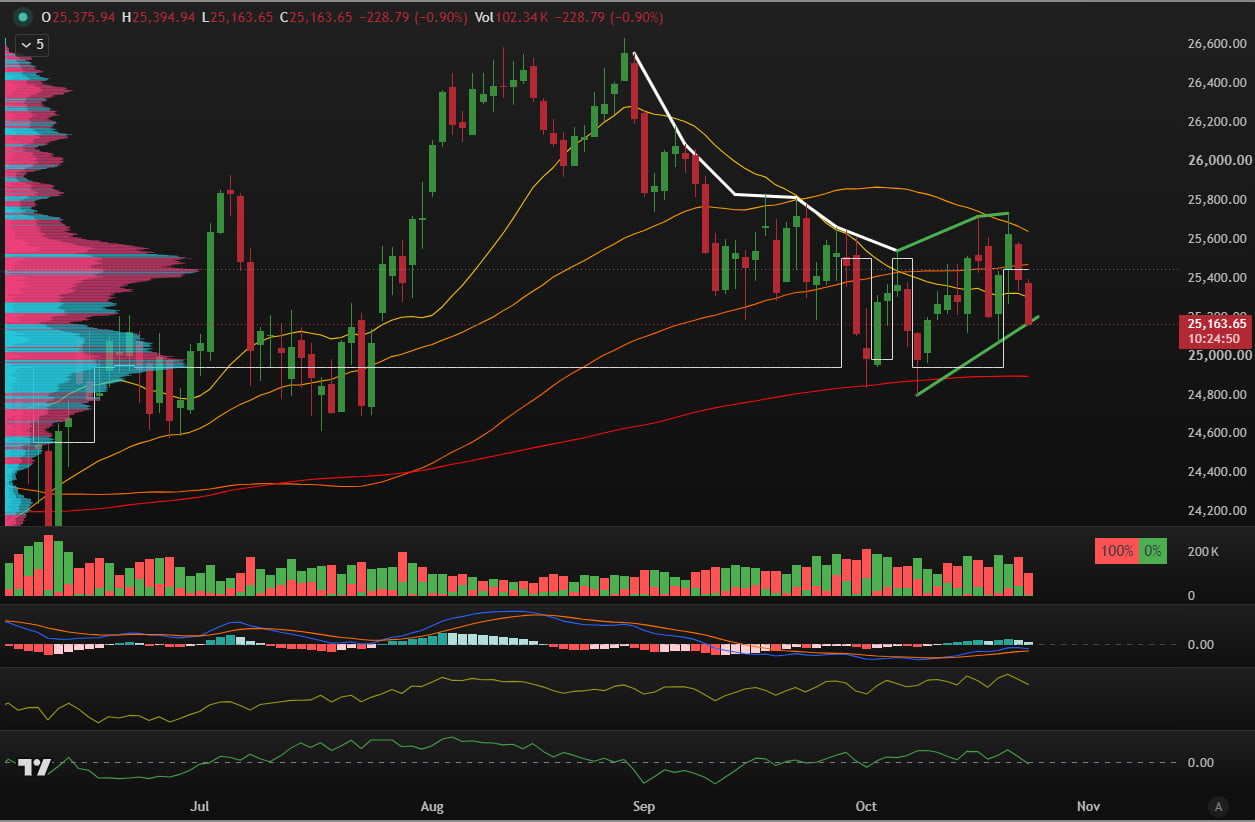
The daily chart shows the DAX that has struggled to sustain its recent rebound. After recovering from the October lows at 24,795, the index advanced towards 25,700 before encountering renewed selling pressure. The subsequent reversal has brought the market back towards the middle of its recent trading range.
The index closed Thursday at 25,371.75, approximately 1.1% lower on the session. The decline also left it below the 50-day moving average, which stood around 25,650 in the latest available daily data. This moving average remains a significant resistance level and indicates that the medium-term recovery has yet to establish a convincing upward trend.
The 20-day moving average, near 25,310, is a more immediate reference point. A sustained break below it would reinforce the deterioration in short-term momentum and increase the risk of a move towards the psychological 25,000 level.
But we are still not decisively bearish over every timeframe, as the DAX remains above its October lows, and the longer-term trend has not been invalidated.
A sustained recovery above 25,600 is still a requirement and would be the first indication that selling pressure is easing.
Four-hour chart: Bearish momentum dominates but attempts to break through are made
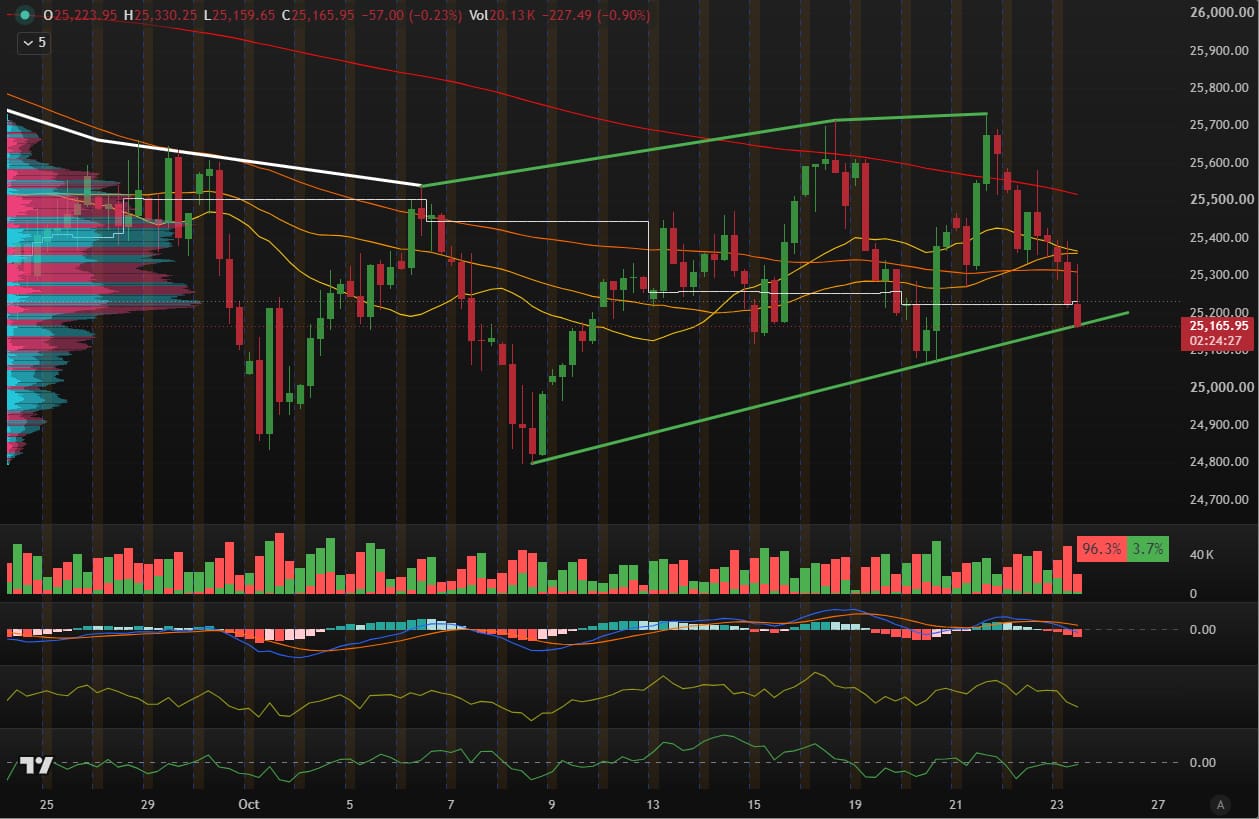
The four-hour technical picture is clearly bearish until the 8th of October. More recently, the DAX is trading slightly below the short-, medium- and longer-period moving averages, but we are supported by the upwards sloping trendline and are not far away.
The MACD is indicating increasing negative momentum without yet showing a clear entry into the bearish levels.
These indicators suggest that the decline is more than a brief intraday fluctuation. However, they do not rule out a technical rebound, particularly if the index reaches the well-established support zone at 25,100.
The immediate pivot level is approximately 25,450. A recovery above this area would improve the short-term bullish picture, but buyers would still need to clear resistance around the 200EMA at 25,520 to establish a more convincing reversal.
On the downside, support is clustered around 25,150 and 25,050. A sustained break beneath these levels would increase the likelihood of a test of the psychological 25,000 level and subsequently the October low at 24,795.
Highlights: The key drivers for Friday’s session
1. Technology weakness triggers renewed selling across global equities
The latest movements are another technology-led decline on Wall Street. The Nasdaq 100 fell 2.90%, while the S&P 500 lost 1.21%. The Dow Jones and the Russell 2000 were broadly unchanged, indicating that the selling pressure was concentrated in large technology and AI-related companies rather than uniformly affecting every segment of the market.
Meta declined 7.0%, with investors focusing on increasing capital expenditures, decreasing profit margins and the continuous financing requirements associated with its AI ambitions. Lam Research also fell 11.8% despite reporting better-than-expected results. Tesla also lost 3.0% and SpaceX declined 9.1%.
These reactions show the divergence between companies delivering strong earnings BUT companies being able to convince investors that their future investment spending will generate adequate returns.
2. Middle East tensions keep oil prices elevated
According to the latest news, President Donald Trump said that the United States had defeated Iran and anticipates further action will follow. US officials have also acknowledged the possibility of a prolonged stand-off.
Also renewed Houthi attacks on Saudi Arabia and reports concerning potential future US and Israeli military action against Iran are raising concerns about further escalation.
Crude prices have therefore been supported, with oil gaining approximately 9 out of the last 12 trading days.
3. Investors move towards safer assets as bond yields decline
Yesterday’s US session also saw increased demand for government bonds while investors are reducing exposure to riskier assets. The seven-year and ten-year yields moved below 5.0% again, which is the months low now.
This deleveraging into Treasury Bonds shows the growing concern about the outlook for technology investment, geopolitical stability and global growth.
4. The US dollar remains firm while European currencies face domestic risks
The US dollar is also edging higher against major currencies. The EURO on the other hand is facing additional uncertainty ahead of Moody’s review of France’s sovereign credit rating and renewed weekend protest activity.
Concerns about French public finances and political stability could place further pressure on French government bonds and widen spreads against German Bunds.
Stay informed,
By Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Faces Fresh Pressure from Tech Rout and Middle East Risks
The DAX has come under renewed pressure as another technology-led sell-off on Wall Street undermines global risk sentiment. While the index remains above key October lows, the recent recovery is losing momentum as investors reassess AI valuations, rising energy prices and escalating geopolitical risks. With oil climbing and major technology stocks facing renewed selling pressure, the focus has shifted back to support levels rather than fresh highs.
Copper Tests 14-Month Support
Copper technical analysis shows prices pulling back from multi-year resistance alongside gold and silver, towards a 14-month uptrend support.
USD/JPY, Nikkei Break Lower as AI Meltdown Spreads
Thursday’s tech tantrum has become Friday’s fire sale. With Nikkei support giving way and the yen strengthening, could the selling start feeding on itself?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.