


DAX outlook: Stock markets resume higher
European markets have started to push higher again, taking their cue from Asia. The Nikkei 225 surged to a fresh record high overnight, with exporters benefiting from recent yen weakness after reports that Japanese PM Takaichi had expressed reservations to BoJ Governor Ueda about further rate hikes. The likes of Germany’s DAX were higher, although the FTSE 100 again stole the show, hitting fresh highs, as it closed in on 10,800. The UK benchmark is now up for the 5th consecutive week, boosted by HSBC earnings and as miners (e.g., Fresnillo) continue good form on metals gains.
Share this:
Update: DAX forecast and analysis on Nasdaq 100
European markets have started to push higher again, taking their cue from Asia. The Nikkei 225 surged to a fresh record high overnight, with exporters benefiting from recent yen weakness after reports that Japanese PM Takaichi had expressed reservations to BoJ Governor Ueda about further rate hikes. The likes of Germany’s DAX were higher, although the FTSE 100 again stole the show, hitting fresh highs, as it closed in on 10,800. The UK benchmark is now up for the 5th consecutive week, boosted by HSBC earnings and as miners (e.g., Fresnillo) continue good form on metals gains. With AI disruption nerves calmer, we are maintaining a positive DAX outlook for now.
Sentiment is positive today
Overall, sentiment has broadly held up since the US open yesterday, after some of the recent AI disruption nerves were soothed by Anthropic unveiling a raft of new partnerships. There was very little immediate market reaction to President Trump’s State of the Union address last night. Elsewhere, oil prices edged lower on renewed hopes of a diplomatic breakthrough in Iran’s nuclear talks. Tehran’s Deputy Foreign Minister said the country is prepared to take the necessary steps to secure a deal with Washington, while Trump struck a mixed tone — insisting Iran wants a deal and reiterating his preference for diplomacy. Bitcoin also bounced, adding to the broader risk-on mood, and boosting the DAX outlook as there are a couple of tech heavy weights such as SAP in the index.
Technical DAX outlook: Bulls remain in control
From a technical point of view, the German DAX index is looking quite bullish. It has managed to hold above a key support zone over the past few days while consolidating its recent gains in a relatively steady manner.
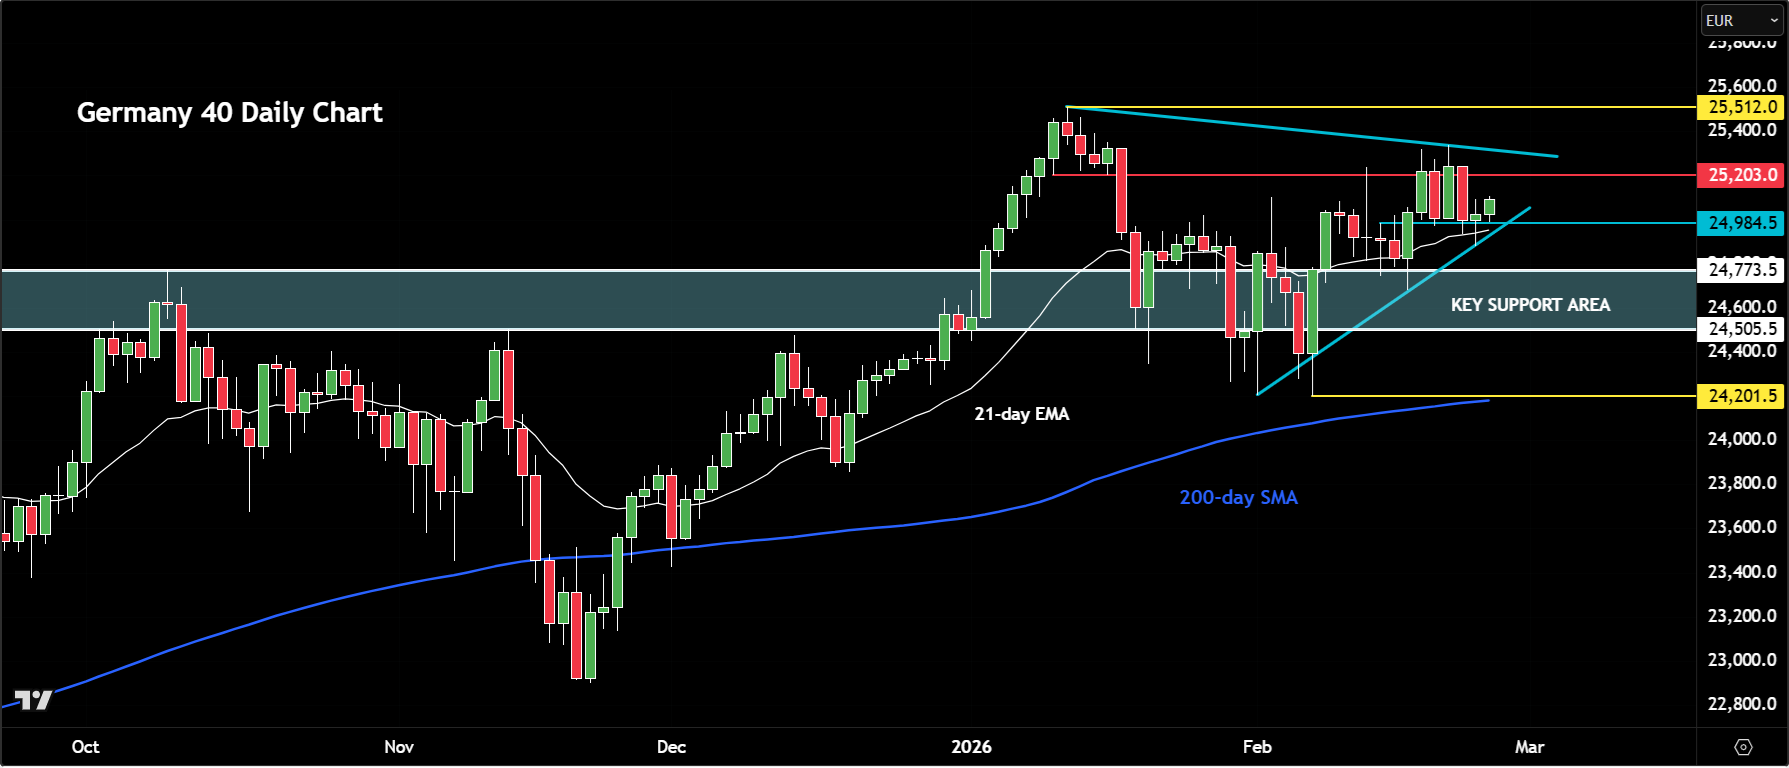
The key support area between 24,500 and 24,770 — the zone highlighted on the chart — is particularly significant. As long as the index remains above this region, the near-term structure stays constructive. Importantly, the DAX is also holding above its rising 21-day exponential moving average and comfortably above the 200-day moving average, which sits considerably lower than the 21-day EMA. This alignment of moving averages reinforces the positive technical backdrop.
Given these signals, the bias remains to the upside. That is why we continue to maintain a constructive DAX outlook from a technical perspective.
In terms of levels to watch, 25,000 to 24,985 is an important near-term support area. It is holding for now and marks today’s lows. On the upside, resistance is seen around the 25,200 area. This level previously acted as support but has since turned into resistance over much of last week and into this week.
The question is whether strength in other European indices — for example, the FTSE — can help lift the DAX further. If momentum across the region continues to build, we could see the German index attempt another push higher. Given the technical factors mentioned, it would be difficult to argue against that scenario.
Keep a close eye on the trendline resistance of the current consolidation pattern. A decisive break above that level would open the door for a move toward the all-time high of 25,512, which was set in early January.

US index futures also gain ground
US equity futures were trading higher following the prior day’s rebound, and after a fairly muted response to Trump’s address, in which he talked up the economy but stopped short of announcing any major new policy measures. Trump delivered a characteristically self-assured defence of the US economy. On tariffs, he described a recent Supreme Court ruling as “very unfortunate” but insisted tariffs will remain in place, claiming most countries are keen to preserve trade agreements and that congressional approval will not be required.
Nvidia could provide next directional move for AI industry
The reversal for stocks started yesterday on Wall Street, where markets recovered from early weakness after Anthropic’s presentation shortly after the open. A number of companies cited as current or future partners saw strong gains, helping to dampen some of the AI disruption fears that had weighed on software names in recent sessions. Consumer Discretionary and Technology led the charge, with AMD jumping sharply on news of a deal with Meta, while Salesforce rose strongly after being singled out by Anthropic as “leading the transformation”.
With tech enjoying something of a calm, the focus now turns to high-stakes Nvidia earnings looming after the close. With unease around AI valuations still bubbling under the surface, Nvidia will likely need not only to beat consensus but also to deliver punchy guidance if it is to properly steady the ship.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.