



EUR/USD Forecast: FOREX Friday | June 5, 2026
The US jobs report is due shortly, before attention turns to US CPI and ECB rate decision next week for the EUR/USD traders. Of course, the bigger issue is oil prices and the Strait of Hormuz. Despite persistent uncertainty surrounding US-Iran negotiations, oil markets have remained remarkably composed, unable yet to generate the upside momentum many would normally expect. That restraint in energy prices is proving important for currency markets, limiting the US dollar’s ability to stage a more convincing rally despite an increasingly supportive domestic backdrop. Will a stronger-than-expected US non-farm payrolls report later today provide another boost to the dollar?
Share this:
The below article was written ahead of the release of the US jobs report.
The US jobs report is due shortly, before attention turns to US CPI and ECB rate decision next week for the EUR/USD traders. Of course, the bigger issue is oil prices and the Strait of Hormuz. Despite persistent uncertainty surrounding US-Iran negotiations, oil markets have remained remarkably composed, unable yet to generate the upside momentum many would normally expect. That restraint in energy prices is proving important for currency markets, limiting the US dollar’s ability to stage a more convincing rally despite an increasingly supportive domestic backdrop. Will a stronger-than-expected US non-farm payrolls report later today provide another boost to the dollar? If the data comes in stronger, it will reinforce the recent shift towards a more hawkish outlook for US monetary policy, keeping the near term EUR/USD forecast tilted to the downside.
Oil holds steady with NFP ahead
Given the uncertainty surrounding supply routes and the absence of meaningful diplomatic progress between Washington and Tehran, traders might reasonably have expected crude prices to move materially higher by now. But they haven’t and this is keeping the dollar retrained for now.
Investors appear confident that tensions will ultimately ease, preventing energy markets from pricing in a more severe supply shock. But do keep an eye on inventories as they continue to run down. For now, though, that optimism is helping to cap further gains in the dollar, even as interest rate expectations have shifted firmly in favour of the greenback over recent weeks.
Attention now turns to the May non-farm payrolls report. Analysts expect a headline print of 85,000 after the above forecast prints of 115K and 185K in the previous two months. Watch out for revisions. Average hourly earnings are seen rising 0.3% month on month, and the unemployment rate is seen steady at 4.3%.
If we see employment growth to modestly exceed market expectations, such an outcome would reinforce the narrative of a resilient US economy and could encourage markets to further reduce expectations of policy easing. A stronger print may provide the catalyst needed for another leg higher in the dollar, while a result closer to consensus would likely preserve existing support levels as investors continue monitoring developments in the Gulf.
EUR/USD holding inside tightening range
For now, the EUR/USD continues to trade within a relatively narrow range, reflecting a market searching for fresh direction. Although the pair has seen periods of volatility, it remains confined to levels that have largely prevailed over the past few weeks.
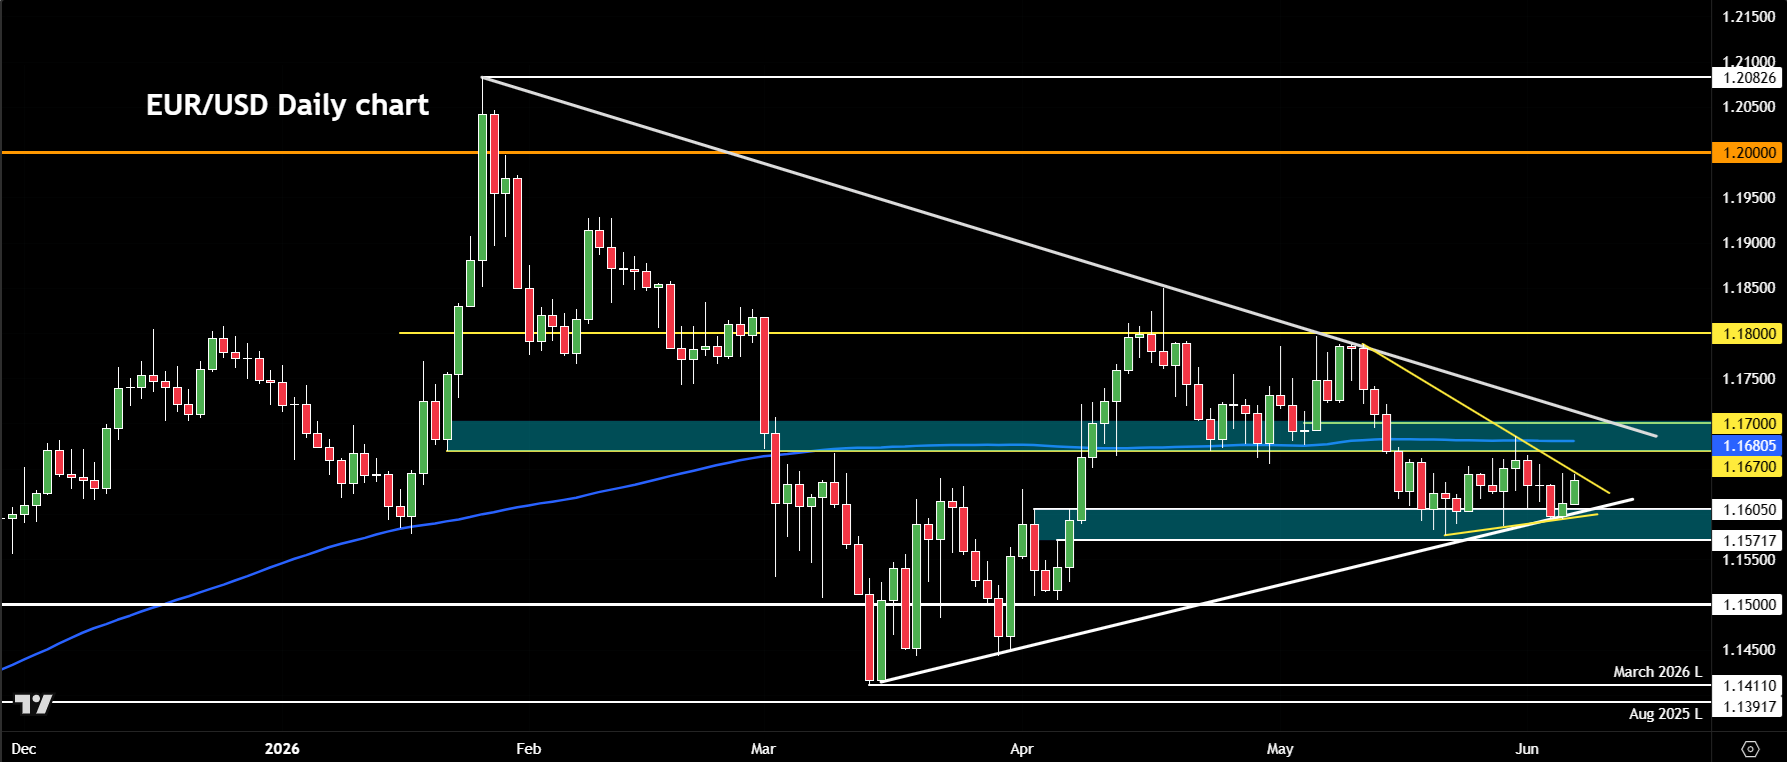
Meanwhile, with oil holding steady, interest rate differentials have reasserted themselves as another driver of the pair. While expectations for the Federal Reserve have become less dovish, investors are increasingly looking ahead to next week’s European Central Bank meeting where an insurance rate hike is expected.
Nevertheless, until there is tangible progress on Middle East diplomacy, downside risks for EUR/USD forecast remain elevated.
EUR/USD forecast: US CPI and ECB rate decision coming up next week
At least two major macro events that are relevant for the EUR/USD forecast are due next week. First up, US inflation data and then ECB’s rate decision.
US CPI - Wednesday, June 10
After surprising to the upside last month with a print of +3.8% year-on-year, CPI is likely to have accelerated further in May amid the energy price spike. If the data comes in above the expected 4.2% reading, it could ignite fresh dollar rally.
ECB rate decision - Thursday, June 11
A 25 basis point hike is fully priced in but the key question is about forward guidance. The ECB is unlikely to disappoint market expectations as that would risk inflation expectations from becoming unanchored. A hawkish increase, with hints that the bank might be ready to raise rates once more, could be mildly positive for euro.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.