



FOMC recap: Fed delivers 75bps, but Powell throws cold water on hawks
On balance, the Fed chief is coming off as relatively dovish...
Share this:

As we noted in our FOMC preview report, the market had already fully “priced in” a 75bps (0.75%) rate hike from the Federal Reserve, with only an outside chance at a full 100bps (1.00%) move, so today’s as-expected 75bps increase, bringing the benchmark Fed Funds rate to the 2.25-2.50% range, has had only a minimal impact on price by itself.
Despite the lack of fireworks from this month’s decision itself, there are still actionable tidbits to glean from the central bank’s monetary policy statement and Fed Chairman Powell’s ongoing press conference:
The FOMC’s monetary policy statement
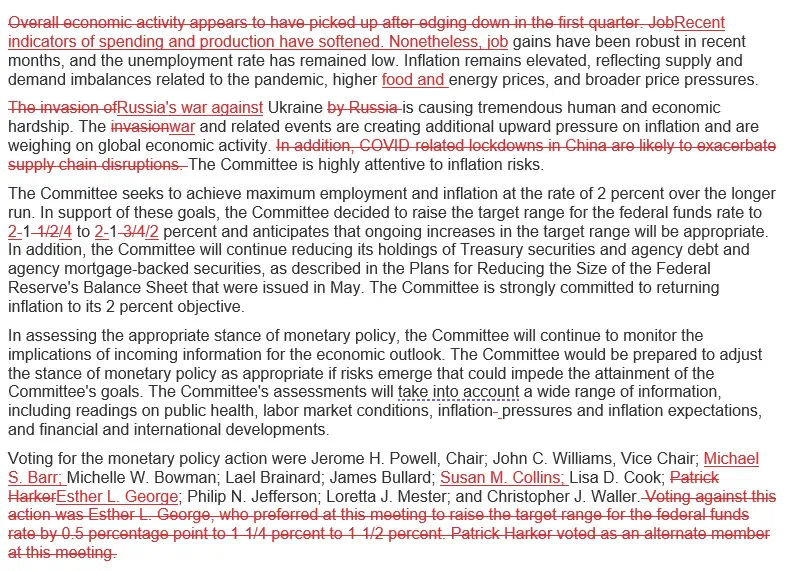
As the “redline” comparison below shows, there were only small tweaks to the central bank’s monetary policy statement:
- Downgraded “Overall economic activity appears to have picked up after edging down in the first quarter” to “Recent indicators of spending and production have softened”
- Acknowledged higher food prices in addition to energy.
- Recharacterized Russia’s “invasion” of Ukraine to a “war”
- Removed the reference to COVID related lockdowns in China and their impact on supply chains.
- The vote was unanimous after Esther George’s dovish dissent last month.
Source: Federal Reserve
Fed Chairman Jerome Powell’s press conference
As all central bankers are wont to do, Fed Chairman Jerome Powell is trying to toe the line between offering useful guidance and avoiding pre-committing to any specific policy path in his press conference. Indeed, he explicitly stated that the committee will go “meeting-by-meeting” and give less clear guidance now that interest rates are “in the range of neutral.”
On balance, the Fed chief is coming off as relatively dovish, and traders have taken that message to heart, driving down the implied odds of a 75bps interest rate increase in September from above 50% to roughly 40% according to the CME’s FedWatch tool.
Other headlines from Powell’s press conference so far:
- FOMC STRONGLY COMMITTED TO BRINGING INFLATION DOWN
- PACE OF RATE HIKES TO DEPEND ON INCOMING DATA
- ANOTHER UNUSUALLY LARGE INCREASE TO DEPEND ON DATA
- LIKELY APPROPRIATE TO SLOW INCREASES AT SOME POINT
- FED TO OFFER LESS `CLEAR GUIDANCE' ON RATE MOVES, WILL MAKE DECISIONS MEETING-BY-MEETING
- POLICY CURRENTLY AT NEUTRAL, NEED TO GET TO AT LEAST A MODERATELY RESTRICTIVE LEVEL
- TAKE EST. FOR RATES NEXT YEAR `WITH A GRAIN OF SALT'
- PATH TO SOFT LANDING HAS NARROWED, MAY NARROW FURTHER
- DO NOT THINK THE US IS CURRENTLY IN A RECESSION
- HAVEN'T MADE DECISION ON POINT WHEN TO SLOW RATE HIKES
- THERE'S SOME EVIDENCE LABOR DEMAND MAY BE SLOWING A BIT
Market impact
Because the monetary policy statement met the market’s expectations almost word-for-word, there was essentially no notable reaction to the initial release. However, as we go to press, traders are clearly acknowledging the dovish tone of Powell’s press conference. Most importantly, treasury yields are declining across the curve, with the 2-year yield dropping 6bps to 3.0% and the benchmark 10-year now yielding 2.74%, down 7bps, to test its lowest level since mid-April.
Not surprisingly, stocks are enthused by the potential for less aggressive interest rate hikes, with major indices rising by between 1.5% (the Dow) and 4% (the Nasdaq Composite). The greenback is seeing major sell pressure come in to fall by nearly 100 pips against most of her major rivals, and gold is testing 2-week highs in the mid-$1730s.
As long as we don’t get any late surprises from Powell, these initial trends could extend further as traders price in the potential for slower rate hikes from the Fed throughout the rest of 2022.
As we noted in our FOMC preview report, the market had already fully “priced in” a 75bps (0.75%) rate hike from the Federal Reserve, with only an outside chance at a full 100bps (1.00%) move, so today’s as-expected 75bps increase, bringing the benchmark Fed Funds rate to the 2.25-2.50% range, has had only a minimal impact on price by itself.
Despite the lack of fireworks from this month’s decision itself, there are still actionable tidbits to glean from the central bank’s monetary policy statement and Fed Chairman Powell’s ongoing press conference:
The FOMC’s monetary policy statement
As the “redline” comparison below shows, there were only small tweaks to the central bank’s monetary policy statement:
- Downgraded “Overall economic activity appears to have picked up after edging down in the first quarter” to “Recent indicators of spending and production have softened”
- Acknowledged higher food prices in addition to energy.
- Recharacterized Russia’s “invasion” of Ukraine to a “war”
- Removed the reference to COVID related lockdowns in China and their impact on supply chains.
- The vote was unanimous after Esther George’s dovish dissent last month.
Source: Federal Reserve
Fed Chairman Jerome Powell’s press conference
As all central bankers are wont to do, Fed Chairman Jerome Powell is trying to toe the line between offering useful guidance and avoiding pre-committing to any specific policy path in his press conference. Indeed, he explicitly stated that the committee will go “meeting-by-meeting” and give less clear guidance now that interest rates are “in the range of neutral.”
On balance, the Fed chief is coming off as relatively dovish, and traders have taken that message to heart, driving down the implied odds of a 75bps interest rate increase in September from above 50% to roughly 40% according to the CME’s FedWatch tool.
Other headlines from Powell’s press conference so far:
- FOMC STRONGLY COMMITTED TO BRINGING INFLATION DOWN
- PACE OF RATE HIKES TO DEPEND ON INCOMING DATA
- ANOTHER UNUSUALLY LARGE INCREASE TO DEPEND ON DATA
- LIKELY APPROPRIATE TO SLOW INCREASES AT SOME POINT
- FED TO OFFER LESS `CLEAR GUIDANCE' ON RATE MOVES, WILL MAKE DECISIONS MEETING-BY-MEETING
- POLICY CURRENTLY AT NEUTRAL, NEED TO GET TO AT LEAST A MODERATELY RESTRICTIVE LEVEL
- TAKE EST. FOR RATES NEXT YEAR `WITH A GRAIN OF SALT'
- PATH TO SOFT LANDING HAS NARROWED, MAY NARROW FURTHER
- DO NOT THINK THE US IS CURRENTLY IN A RECESSION
- HAVEN'T MADE DECISION ON POINT WHEN TO SLOW RATE HIKES
- THERE'S SOME EVIDENCE LABOR DEMAND MAY BE SLOWING A BIT
Market impact
Because the monetary policy statement met the market’s expectations almost word-for-word, there was essentially no notable reaction to the initial release. However, as we go to press, traders are clearly acknowledging the dovish tone of Powell’s press conference. Most importantly, treasury yields are declining across the curve, with the 2-year yield dropping 6bps to 3.0% and the benchmark 10-year now yielding 2.74%, down 7bps, to test its lowest level since mid-April.
Not surprisingly, stocks are enthused by the potential for less aggressive interest rate hikes, with major indices rising by between 1.5% (the Dow) and 4% (the Nasdaq Composite). The greenback is seeing major sell pressure come in to fall by nearly 100 pips against most of her major rivals, and gold is testing 2-week highs in the mid-$1730s.
As long as we don’t get any late surprises from Powell, these initial trends could extend further as traders price in the potential for slower rate hikes from the Fed throughout the rest of 2022.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Analysis: Resilient U.S. Labor Market Continues to Pressure XAU/USD
Recent trading sessions have not been particularly favorable for gold in the short term. XAU/USD has fallen nearly 2.5% over the last three sessions, reflecting that selling pressure is once again gaining relevance and that the metal continues to struggle to regain momentum.


USD/JPY Analysis: Rising U.S. Yields Leave the Yen on the Defensive
As the first week of November progresses, renewed weakness in the Japanese yen is once again becoming evident in the short term. This dynamic can be seen in the recent performance of USD/JPY, which has posted two consecutive bullish sessions and gained more than 0.7%, reflecting a return of buying interest in the dollar while the yen continues to lose momentum.
Have Markets Found a Turning Point Ahead of the Elections?
Fed rate-hike bets topping 70% have pressured markets, including precious metals and U.S. indices, toward key support levels. Could these levels signal a turning point ahead of the U.S. midterm elections?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.