



French election nerves reflected in the market
The first round of the French Presidential elections will be held on Sunday 11th April. The market has woken up to the possibility of a Le Pen win.
Share this:
French Presidential elections
The first round of the French Presidential elections will be held on Sunday 11th April. A candidate needs to win 50% of the votes in order to win straight out. This has never happened, and this year is unlikely to be the first. The second round is held on the 24th of April.
Heading into the election, President Macron is the favourite to win. However, the market has woken up to the prospect of a political shock and a win by far-right candidate Marine Le Pen. Macron faced Le Pen back in the 2017 election, where he won a landslide victory.
In 2017 Macron won by 66% to 34%. Today that difference is much tighter with one poll even pointing to a Le Pen win, but most are looking at 53%, 47%.
While back in 2017, Le Pen was focused on exiting the euro, this time around, she has rebranded herself to focus on economic problems. With consumer prices surging ever higher, there are certainly plenty of economic issues to be focusing on.
Le Pens’ policies are a big concern for the market with expectations for large-scale public borrowing, contravening the Eurozone’s budget rules and challenging the German-led consensus of fiscal stability.
Reflected in the market
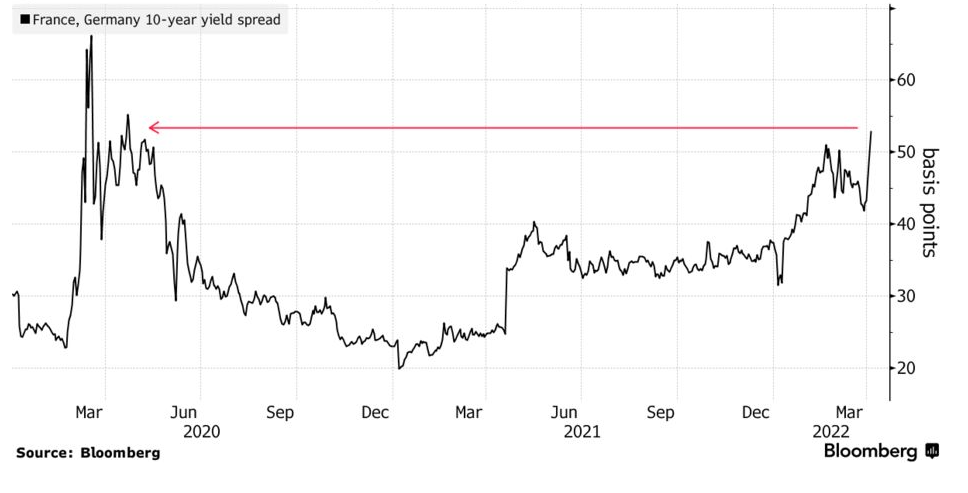
Nerves in the market have started to show up this week. Firstly, the spread between the French and the German 10-year bonds, considered a proxy for political risk, has widened.
The French stocks market has also underperformed, losing over 2% across the week, while the FTSE has risen 0.5%, and the EUR/USD has traded lower for seven straight days. A close first round between Macron and Le Pen could see EUR/USD sink to fresh 2022 lows. Meanwhile a Le Pen win could see EUR/USD sink significantly lower. Currently the odds of a Le Pin sit at around 20%.
The market has started to sweat as Le Pen has closed the gap in the polls. The risks are being priced in, but a Macron victory is still the most likely outcome for now.
Where next for EUR/USD?
EUR/USD rebounded lower from the 50 sma, breaking below 1.10 the key psychological level and the lower band of the multi-month falling channel.
The RSI points to further losses whilst it remains out of the oversold territory. Support can be seen at 1.08 the 2022 low ahead of 1.0730 the April 2021 low.
Any recovery would need to rise above 1.0940 the March 28 low, ahead of 1.10.


How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Short-term Outlook: USD/CAD Plunge Stalls at Pivotal Support—Range Break in Focus 11 5 2026
Friday’s U.S. and Canadian employment reports could trigger a decisive USD/CAD move as bulls and bears battle for control at critical support.

US Dollar Technical Outlook: DXY Bulls Fight to Hold Critical Support Ahead of NFP 11 5 2026
DXY bulls are attempting to defend a pivotal technical threshold, with the next reaction likely to determine whether the broader recovery survives.
Nasdaq 100 forecast: Tech stocks remain under pressure despite mid terms rally
The Democratic sweep in the US midterms delivered the negative dollar reaction I had anticipated, but that upsurge in stocks was not something I or many others had anticipated. Fears that a Democrat-controlled Congress would trigger a broader sell-off in technology stocks proved premature. Nevertheless, the sector remains under pressure. The political outcome may help explain the Nasdaq’s relative underperformance with futures falling 0.8% today. Sharp falls in shares of Arm and Qualcomm following their results are certainly not helping. While the removal of midterm uncertainty provided a broad-based boost to risk appetite yesterday, investors may be starting to price in the prospect of tighter regulatory scrutiny of Big Tech, particularly around AI, under greater Democratic influence in Congress. This could become a headwind for technology valuations, even if the immediate impact on corporate earnings remains unclear.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.