


Global Politics, US Shutdown Risks, and a Precious Metals Rally Shape Market Outlook
Global affairs drive markets as Trump pushes a Gaza peace plan, Moldova advances toward the EU, and Russia warns on US missile data. In the US, shutdown risks rise, while corporate news spans Starbucks closures and cannabis gains. Gold, silver, and platinum hit multi-year highs, while the DAX signals a bullish setup. Investors face a volatile mix of geopolitics, policy shifts, and commodities momentum.
Share this:
Geopolitics & Global Affairs
- Middle East: Trump to host Israeli PM Netanyahu at the White House, pushing for a Gaza peace plan as Israeli forces advance into Gaza City. Iran executed a senior alleged Israeli spy.
- China: Launching a new visa program to attract foreign tech talent, contrasting with Washington’s tighter visa policies.
- Moldova: Pro-EU ruling party won a decisive election, strengthening its bid to join the EU and weaken ties with Moscow.
- Russia–Ukraine: Moscow warns it will assess if US targeting data is used with Tomahawk missiles should Washington approve Kyiv’s request.
- Myanmar: UN-backed probe finds military destroyed Rohingya villages post-2017 expulsions, converting land to security outposts.
- Vietnam: Typhoon Bualoi killed at least 13, injured 46, and caused major damage along the coast.
United States Politics & Economy
- Shutdown risk: Government funding expires Tuesday night, with no bipartisan deal in sight.
- NYC politics: Mayor Eric Adams ends re-election bid after bribery indictment and low approval ratings.
- Drug law enforcement: Federal drug law prosecutions have fallen to multi-decade lows as enforcement shifted toward immigration.
- Trade: Australian beef has largely displaced US beef in China under Trump’s administration, redirecting hundreds of millions of dollars in trade flows.
Corporate & Sector News
- Healthcare/Pharma:
- Morgan Stanley downgraded Novo Nordisk (to underweight, $47 target) on expectations its Alzheimer’s trial will fail.
- US tariff proposals weigh on branded pharma stocks in Europe.
- Consumer: Starbucks to close 1% of North American stores and cut 900 corporate jobs under a $1bn restructuring plan.
- Cannabis: US pot stocks surged after Trump endorsed cannabidiol (CBD) for senior healthcare.
- Tech & Gaming: Reports suggest Electronic Arts (EA) is near a $50bn go-private deal (WSJ, from earlier updates).
Europe
- France: PM Sébastien Lecornu signals 2026 budget targets a 4.7% deficit. He rejects reversing pension reform or reintroducing a wealth tax but faces political hurdles in securing parliamentary approval. Possible snap elections if talks collapse.
- Germany 40: Technical Analysis: 4H timeframe. The price action shows a recovery from early September lows near 23,200, with a rising trendline offering short-term support. The recent bounce has pushed price back toward the 23,800 zone, where it briefly pierced the upper Bollinger Band before easing slightly. This suggests near-term overextension, but the overall structure points to a gradual shift from a sideways consolidation into a potential uptrend. RSI at ~58 remains supportive without being overbought, while the MACD has crossed into positive territory, showing bullish momentum.
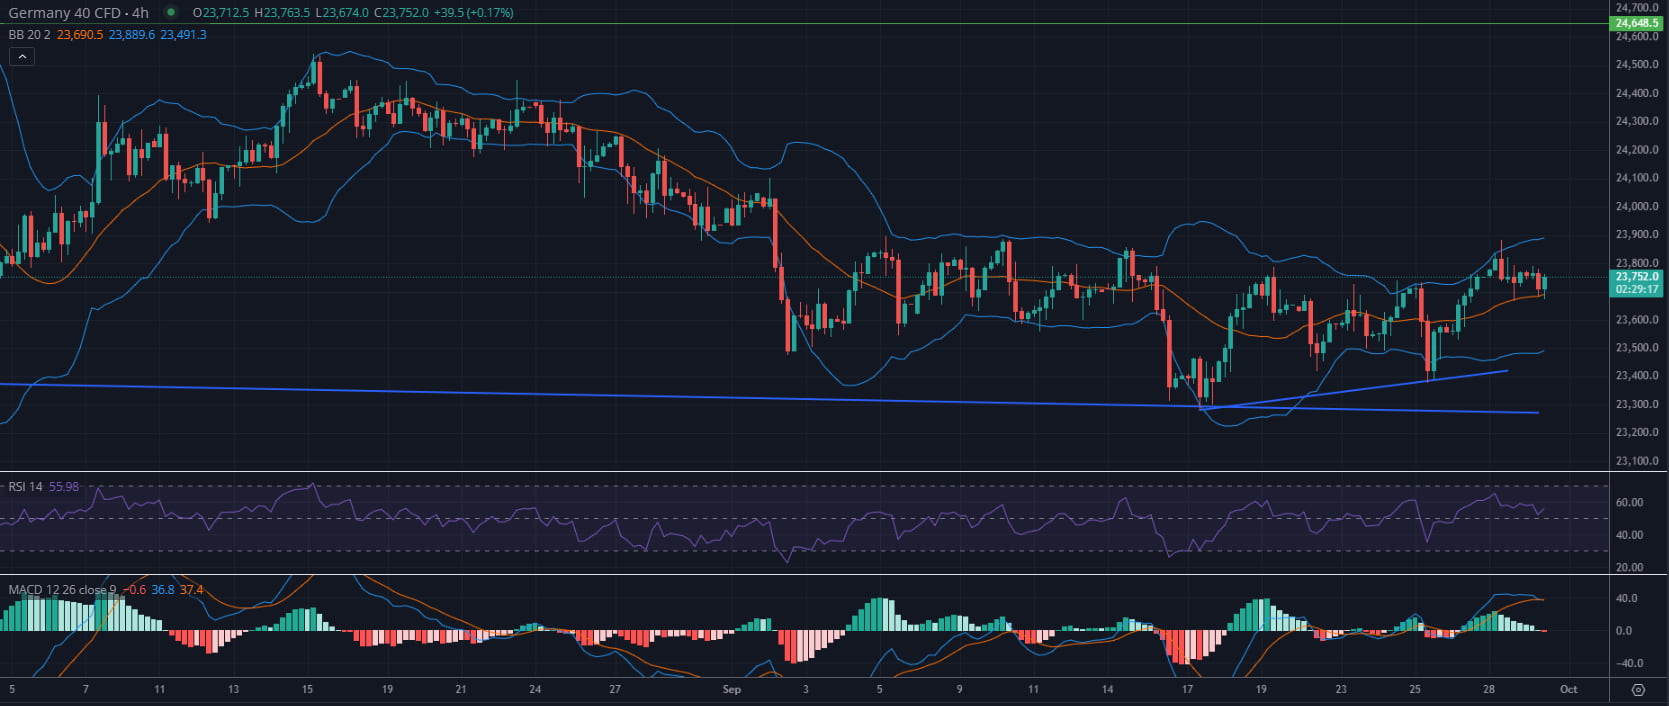
- Key levels are clear: immediate support sits around 23,500 and again near the rising trendline (~23,300), while resistance lies overhead near 24,000–24,100 and more prominently at 24,650. As long as the price holds above the rising trendline, bulls maintain the advantage, with further upside possible on a clean break above 24,000. However, a failure to hold above 23,500 could risk dragging the index back toward 23,200, neutralizing the emerging bullish case.
Macroeconomics
- US PMI: September composite slipped to 53.6 (from 54.6), but still expansionary. Growth cooled in orders and employment, while costs rose sharply due to tariffs. Business optimism improved, with analysts projecting corporate earnings growth of 11% in 2025 and 13%+ in 2026–27, particularly in tech.
Commodities
- Precious metals rally:
- Gold broke $3,800/oz, silver surpassed $47/oz (14-year high), platinum hit $1,630/oz (12-year high).
- YTD gains: Gold +45%, Silver +63%, Platinum +75%.
- Silver demand, especially from solar PV, continues to rise, while inventories are shrinking sharply (London stocks down to 350m oz from 1.18bn in 2021).
- Analysts warn of volatility and correction risks despite bullish fundamentals.
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Nears New Highs as Investors Rotate Back Into Growth
The DAX continues to push higher, trading above 26,500 as investors extend last week's recovery. Falling oil prices, improving sentiment toward technology stocks and stronger-than-expected German industrial production have helped support risk assets globally. Attention now turns to US inflation data and a busy earnings calendar, which will determine whether the rally can continue toward fresh record highs.
DAX Rebounds as Investors Look Beyond the AI Selloff
The DAX has started the week on a stronger footing, recovering from last week's technology-driven selloff and pushing back toward the key 26,000 level. Improving sentiment across global markets, easing oil prices and a positive reassessment of technology valuations have helped support the rebound. Attention now shifts to Tuesday's US inflation report and a busy earnings calendar, both of which will determine whether the recovery can extend further.
DAX Weakens as Tech and Defence Stocks Come Under Pressure
European equities are under pressure as the global technology selloff extends into a second session. Concerns about AI-related capital expenditure, semiconductor demand and regulatory risks are weighing heavily on technology stocks, while rising oil prices add another layer of uncertainty. With the US jobs report due later today, investors are reassessing valuations, growth expectations and the outlook for interest rates.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.