
Gold outlook: Inflation, oil and yields keep downside risks elevated
With inflation still the Federal Reserve’s main concern and elevated oil prices keeping pressure on bond yields, the near-term gold outlook remains tilted to the downside, even if the longer term view remains constructive.
Share this:
Not much has changed in terms of the direction of travel for gold prices. The near-term remains somewhat bearish, while the longer-term bullish story is still quite strong. This leaves gold in a bit of limbo in the near-term. This morning found gold prices a bit higher than Friday’s close, a day when the metal came under renewed pressure despite the weaker US jobs report that had initially provided the metal some support. Weaker employment data may have offered gold that short-lived bounce, but it has not altered the broader macro backdrop. With inflation still the Federal Reserve’s main concern and elevated oil prices keeping pressure on bond yields, the near-term gold outlook remains tilted to the downside, even if the longer term view remains constructive.

Inflation remains the Fed’s priority
The softer US jobs figures do little to resolve the Federal Reserve’s central problem: inflation remains uncomfortably high. While labour-market weakness can strengthen the case for lower interest rates, the Fed is unlikely to respond aggressively if price pressures remain persistent.
That appears to be how the market interpreted the situation after Friday’s jobs report. Gold found buyers initially, but the rebound ran into resistance and failed to develop into a more meaningful reversal.
The dollar also proved relatively resilient. I had my doubts about whether the greenback would fall much further following Friday’s data, and sure enough, it has since resumed its upward move. That is a big headwind for gold.
Oil remains a problem for gold
Elevated oil prices are making the inflation story more complicated. Higher energy costs risk keeping inflation sticky for longer, while simultaneously putting pressure on government bond markets.
For gold, that combination is far from ideal. Higher Treasury yields increase the opportunity cost of holding a non-yielding asset, while a stronger dollar add obvious, direct, pressure.
Unless oil prices begin to fall meaningfully, the macro environment is therefore likely to remain challenging for gold.
The next major test will come from US CPI on 14 October. A hotter-than-expected inflation reading could reinforce expectations that the Fed will keep policy tighter for longer, potentially providing another catalyst for dollar strength and higher yields.
Conversely, a significant downside surprise in inflation could give gold some breathing room.
Technical gold outlook and levels to watch
From a technical analysis point of view, gold remains vulnerable. The metal tested its bearish trend line following the jobs report but failed to break it, although equally it has failed to break its bearish trend as well.
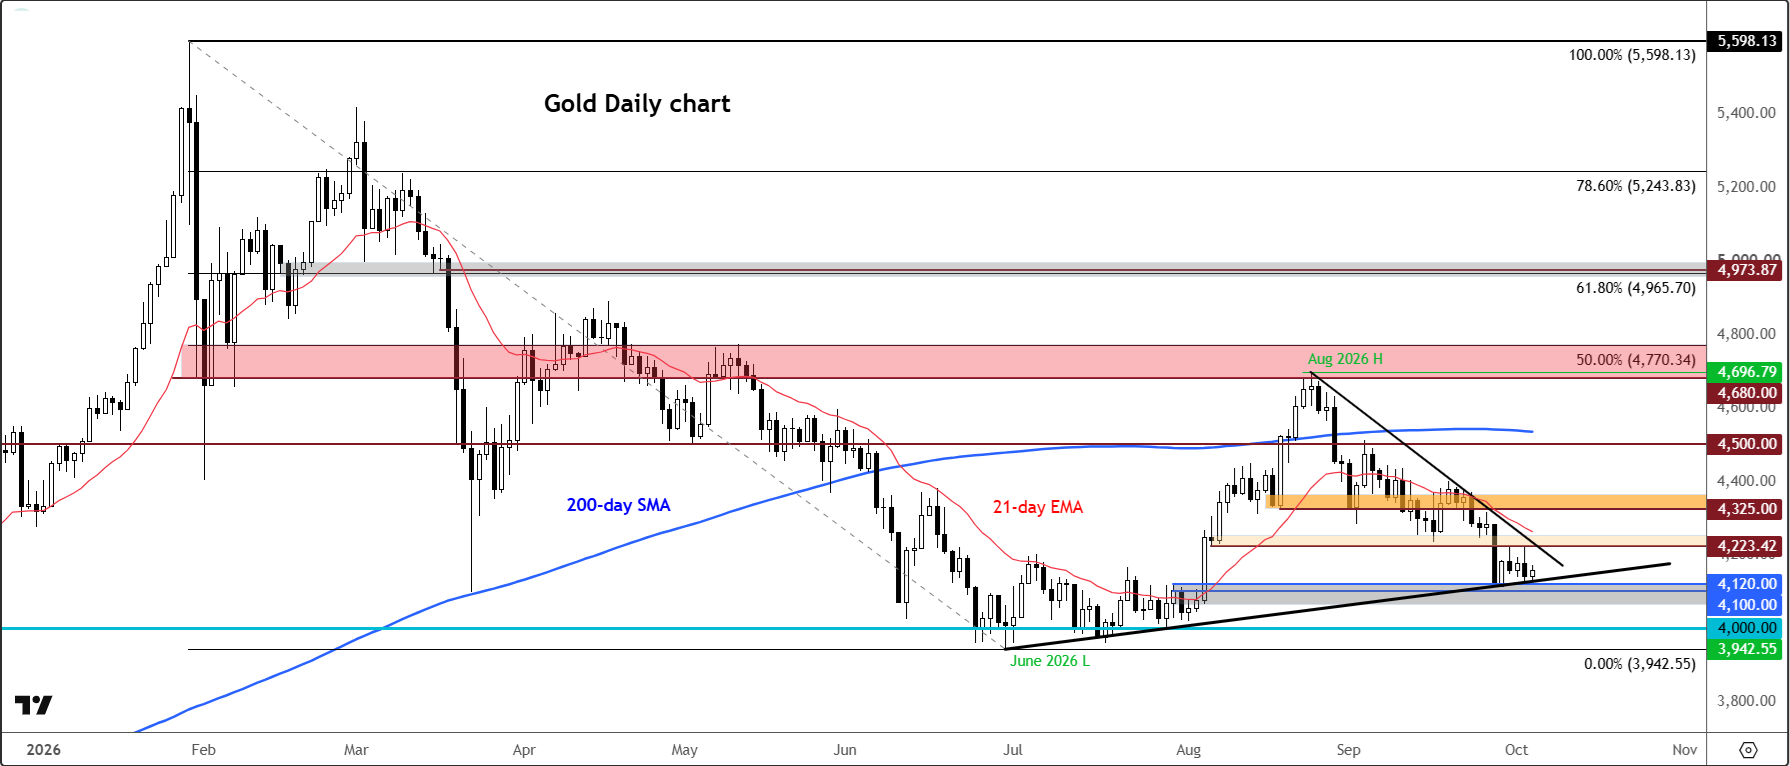
A sustained break above the bearish trend line would be the first indication that the downside bias is losing momentum. More importantly, XAUUSD would need to reclaim the former support zone around $4,220-$4,235 area to potentially trigger a proper short squeeze rally. In that cast, $4,280 - $4,300 would become the first upside target.
On the downside, $4,100 - $4,120 is the most important area of support to watch. This was the base of the early-August breakout and was tested during last week’s sharp decline, and it is where that short-term bullish trend lines comes into focus.
A sustained break below that zone would leave relatively little in the way of major technical support before the psychologically important $4,000 level. Given the recent price action, a move towards $4,000 later this month cannot be ruled out, although buyers could still emerge before then.
Central banks provide a longer-term cushion
The bearish near-term setup does not mean the longer-term case for gold has disappeared. Central-bank demand remains an important structural source of support. Persistent concerns about fiscal sustainability and the heavy concentration of global reserves in US Treasuries could reinforce that trend. Further diversification away from dollar-denominated assets would provide a structural floor beneath gold, potentially limiting the depth of any correction.
If persistent stress in the US bond market starts to undermine confidence in the country’s fiscal position, rising yields could eventually become negative for the dollar rather than supportive. Investors could increasingly look towards alternative stores of value, including gold, silver and Bitcoin.
This is something we have discussed in our Gold Q4 outlook.
Watch: Technical analysis on gold and Dow
Related tags:
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold outlook: Inflation, oil and yields keep downside risks elevated
With inflation still the Federal Reserve’s main concern and elevated oil prices keeping pressure on bond yields, the near-term gold outlook remains tilted to the downside, even if the longer term view remains constructive.

Gold and Silver Broke Their Uptrend but the Floor Held Firm
The gold and silver outlook keeps its long-term bullish structure even after both metals broke below their July to September 2026 uptrend.
Gold Breaks Down on Descending Triangle, Sets Up $4k Test
Gold started last week with a strong sell-off but from that move a bounce developed. Bulls could not hold on through the weekly close, however, and the bearish structure remains in-place for XAU/USD.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.