



Nasdaq 100 forecast: How will Tesla Q3 earnings impact TSLA stock?
All eyes are on how price cuts are impacting margins and whether more reductions will be needed to support demand.
Share this:
Key takeaways
- Tesla delivered far fewer cars than expected in the third quarter
- Production shortfall blamed on factory downtime, but elevated inventory levels suggests demand is more muted
- That is raising fears that more price cuts will be needed, leading to lower margins
- Profitability is already under pressure, leading Wall Street to lower earnings estimates in the near-term and for 2024
- Cybertruck, work on new batteries, Dojo, Full-Self-Driving and Robotaxis all popular topics among investors ahead of update
- Tesla shares have been trading in a wedge that is narrowing, and the results could provide the catalyst needed for a breakout
Tesla Q3 earnings date and time
Tesla is scheduled to release third quarter earnings after US markets close on Wednesday October 18. A live Q&A session will be held with management on the same day at 1630 CT (1730 ET).
Tesla earnings consensus
Revenue is forecast to climb 13.6% year-on-year to $24.37 billion, based on a Bloomberg-compiled consensus. Adjusted EPS at the bottom-line is forecast to fall 29% to $0.74.
Tesla earnings preview
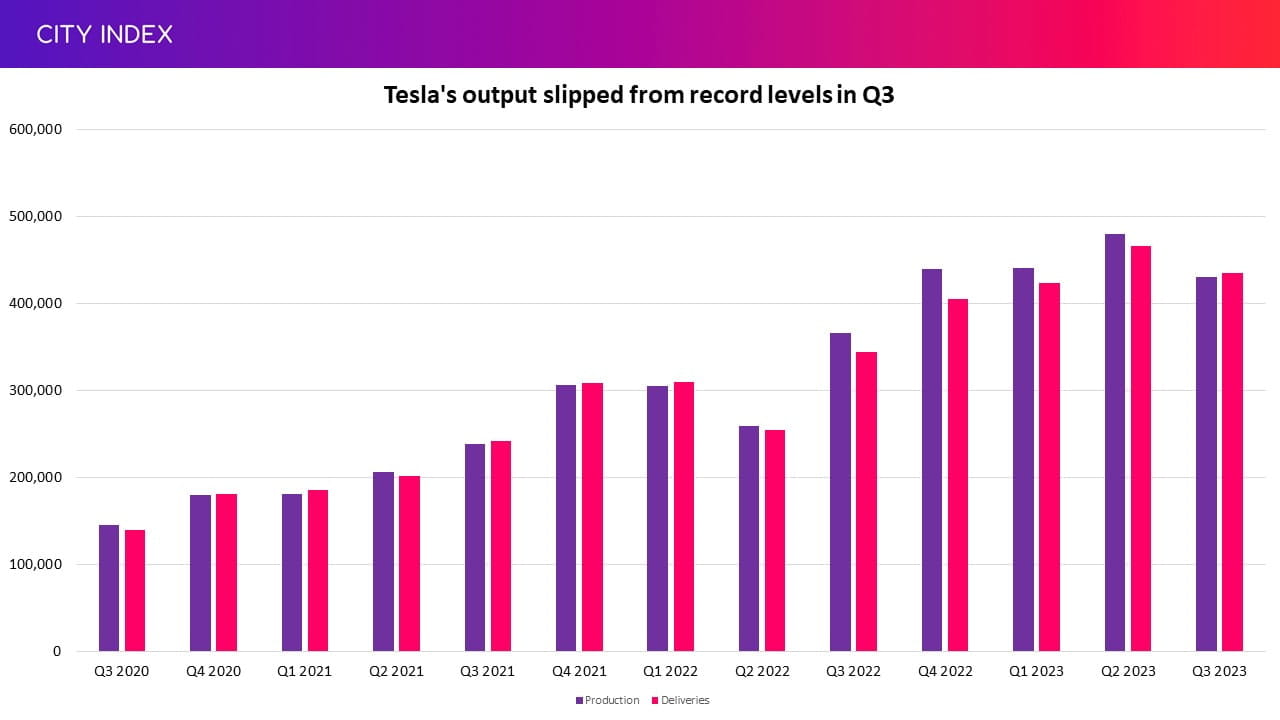
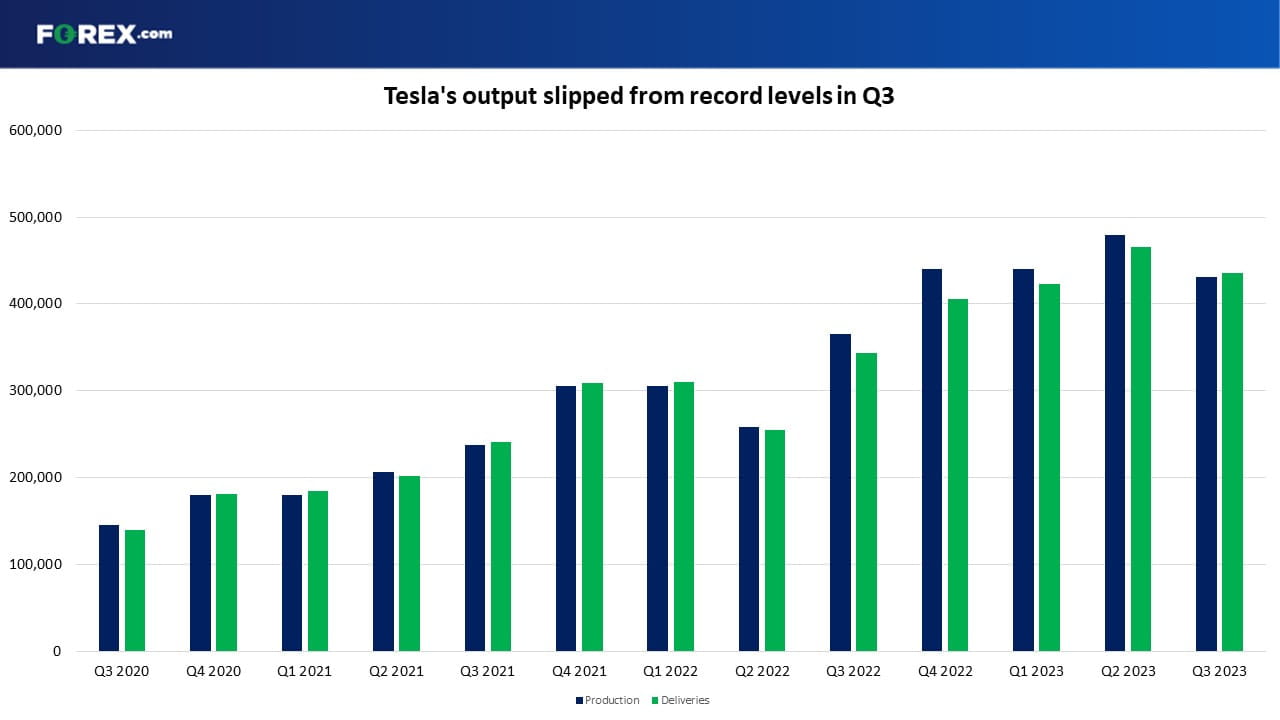
We already know that Tesla delivered far fewer cars in the third quarter than expected. It sold 435,059 electric vehicles in the period, over 20,000 below the Wall Street forecast! That was blamed on factory downtime, including the adjustments that have been necessary to introduce the newly-revamped Model 3 and the upcoming Cybertruck.
(Source: Company reports)
However, there are signs that demand is weakening. Tesla sold more cars than it produced for the first time in 18 months during the quarter, but only just. That means inventory levels remain elevated, which may raise questions about why Tesla didn’t make more sales even if production was disrupted.
With that in mind, Wall Street analysts have understandably become more cautious ahead of the financial results, not only because of the big delivery miss but also over fears that more price cuts will be needed to keep demand growing. That has seen Wall Street lower its earnings estimates in both the near-term and for 2024.
The series of price cuts Tesla has been taking is already hitting profitability. Its operating margin is seen coming in at just 9.5% this quarter compared to over 17% the year before, which is forecast to see operating income plunge 37% to $2.31 billion.
Tesla is aiming to deliver at least 1.8 million vehicles this year. Wall Street remains confident it can achieve that despite the big miss in the most recent quarter, but that leaves little room for error in the final quarter, when analysts believe it can sell over 492,000 vehicles. Regardless, Tesla is set to fail to grow deliveries by an annual rate of 50% for yet another year. It last achieved that goal in 2021, and analysts are becoming less and less convinced that it will ever hit that level of annual growth again.
The update on the long-awaited Cybertruck, which is expected to enter full production before the end of 2023, will also be key as investors hope they will finally see the pickup truck hit the market following years of delays. The most upvoted question submitted for the Q&A session by a country mile is about how many Cybertrucks will be delivered in 2024.
Other popular questions to be posed by investors focus on the outlook for deliveries in 2024, progress with its new batteries and how they can improve performance and lower costs, the ramp-up in capacity at its newest factories and plans to open new sites, and around Full Self-Driving and its Robotaxi.
Where next for TSLA stock?
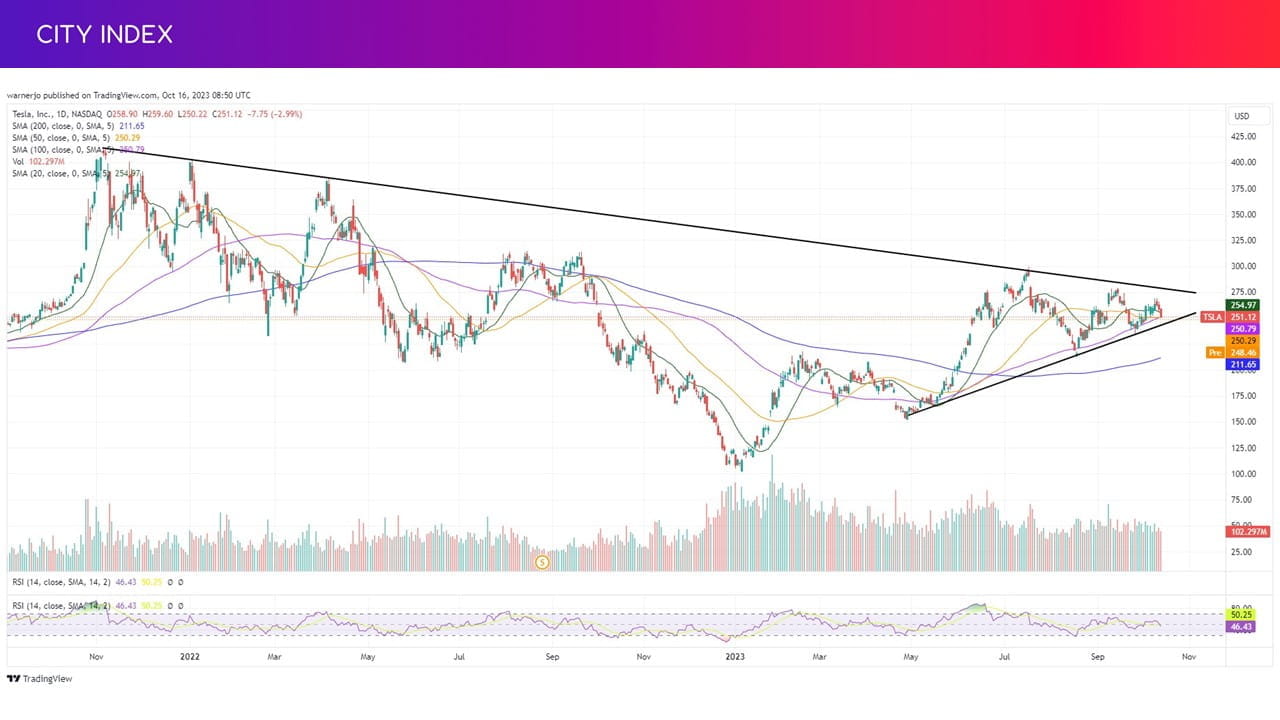
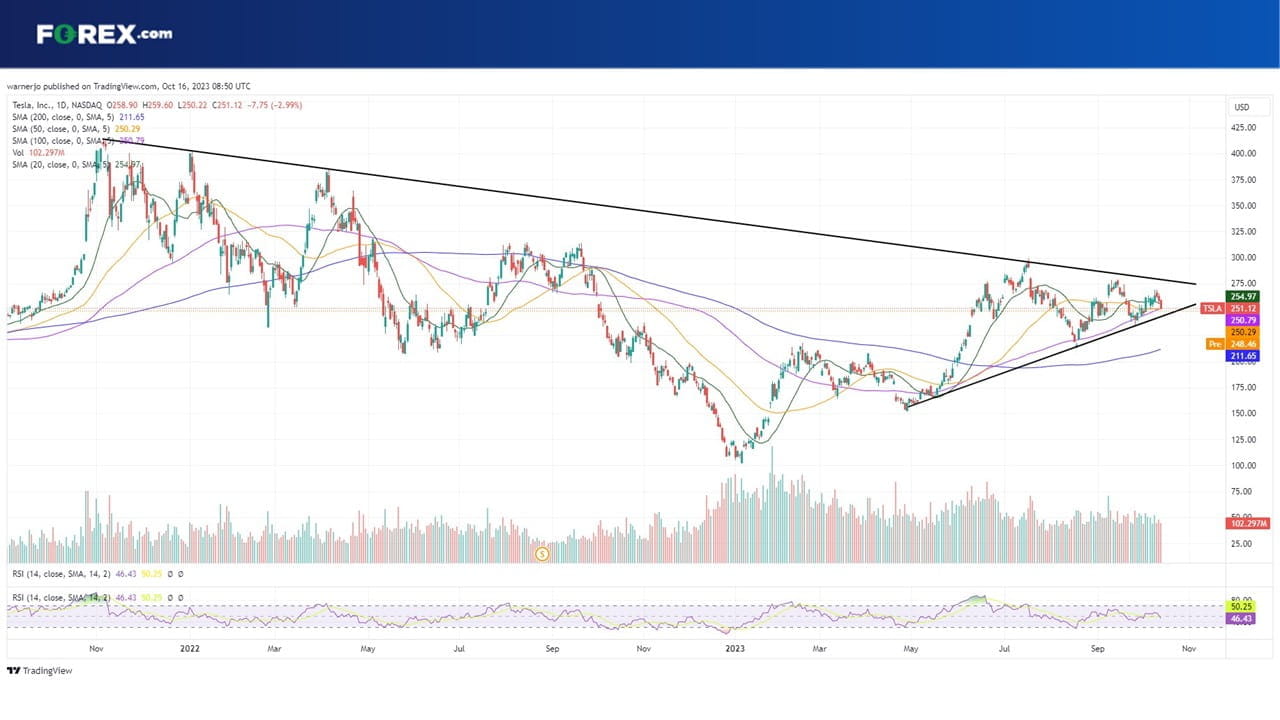
Tesla shares have been pinging between a wedge formed by two dominant trendlines. This wedge is narrowing and the chance of a breakout is therefore rising, and the results have the potential to provide the necessary catalyst.
The falling trendline has been in play since Tesla shares peaked at their all-time high just under two years ago. To break above it, the stock would need to close above around $277 this week.
The rising trendline has been providing support for six months, although the 100-day moving average that is tracking above it, currently at $250.80, has been a reliable source of support in recent weeks. The fact the 50-day moving average has also converged here bodes well.
Wall Street is currently sceptical about how much upside there is over the next 12 months. The 45 brokers that cover the stock currently have an average Hold rating on Tesla and a target price of $237, about 4% below current levels.
Nasdaq 100 analysis: Where next?
Tesla carries a 3.2% weighting in the Nasdaq 100, making it the index to watch ahead of the update. It also has the potential to influence other smaller electric vehicle stocks, such as Rivian and Lucid.
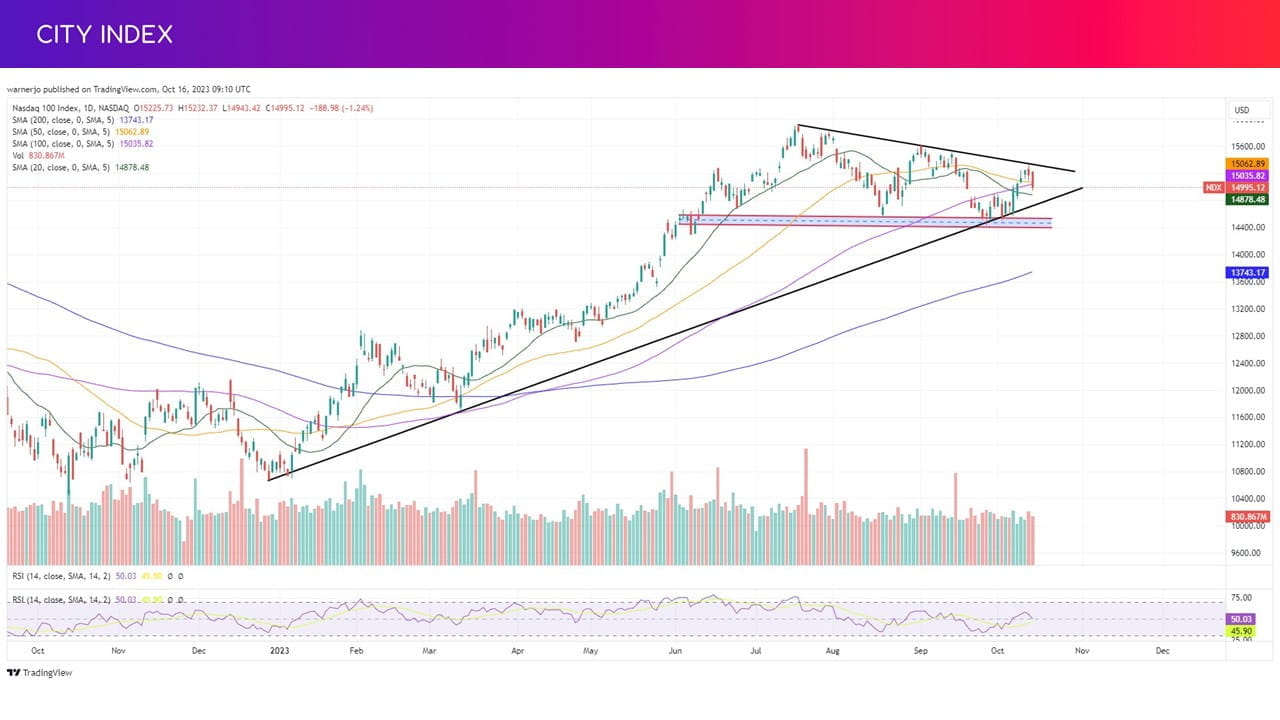
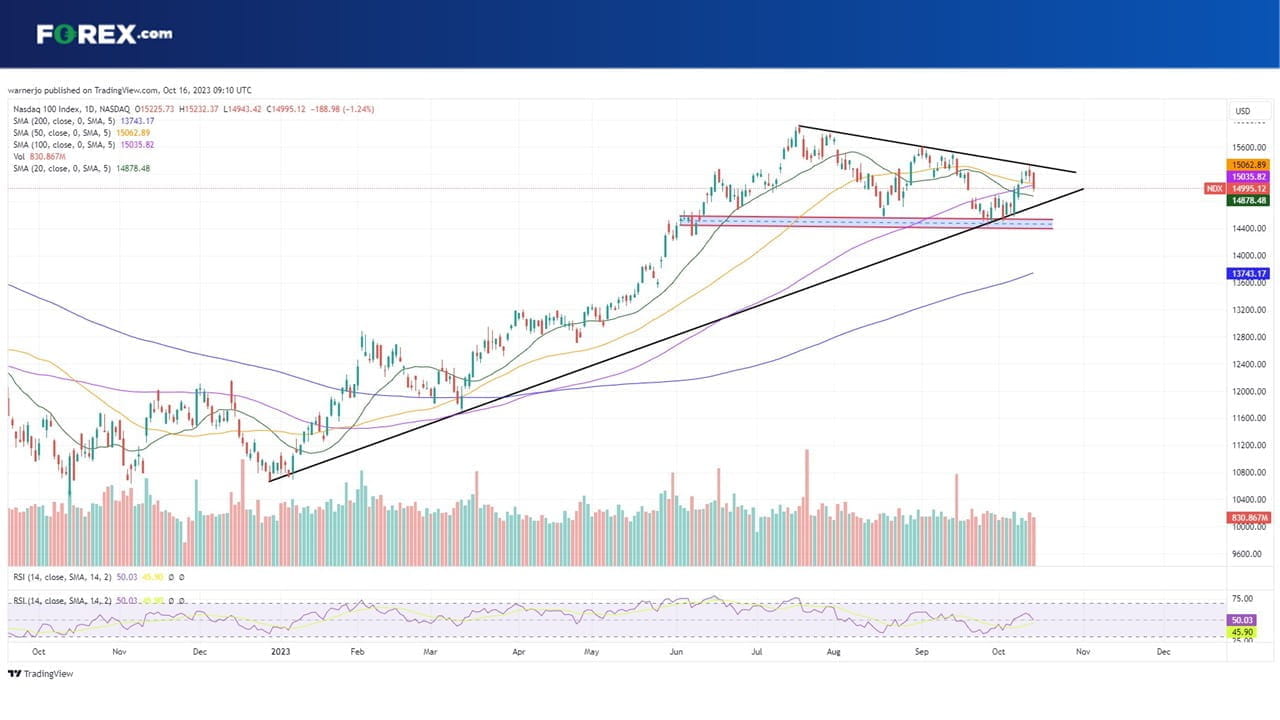
The Nasdaq 100 is also trading within a wedge that is narrowing. The index slipped below 15,000 and below both the 50-day and 100-day moving averages on Friday. Only the 20-day moving average at 14,890 stands in the way of it testing the supportive trendline again. A break below here would bring the support zone between 14,560 and 14,440.
A return above 15,000 is the immediate job and then it can try to close at a new higher-high above 15,265. That would then being the falling trendline into play at around 15,300.
How to trade Tesla stock
You can trade Tesla shares and indices with City Index in just four easy steps:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the stock or instrument you want in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Or you can practice trading risk-free by signing up for our Demo Trading Account.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Short-term Outlook: AUD/USD 3% Plunge Puts Multi-Month Range at Risk 11 6 2026
A sharp equity-led selloff has driven AUD/USD toward critical June-low support, with strong NFP data adding pressure ahead of next week’s U.S. CPI.

Nasdaq 100 forecast: Tech stocks rebound but AI concerns linger
The Nasdaq 100 rebound has run into former support as fears over AI regulation and spending linger. Fawad Razaqzada explains why he maintains a cautious forecast and where the key levels sit.

Dollar forecast: NFP provides dollar, already supported amid tech sell-off, additional boost
The US dollar has found some mild amid the tech rout in recent days, most visibly against risk sensitive and commodity dollars. Today, we have so far seen a bit of a recovery in global indices from their overnight lows. Investors will be watching the markets to see whether fresh losses will be on the again once Wall Street gets going. Ahead of that, we have just seen the release of the October US non-farm payrolls report – and it was much stronger at 165K than expected.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.