



Market Brief New Year cheer has a familiar feel
Thursday’s stock markets are what it looks like when risk appetite hits the ground running
Share this:
Stock market snapshot as of [2/1/2020 2:17 pm]
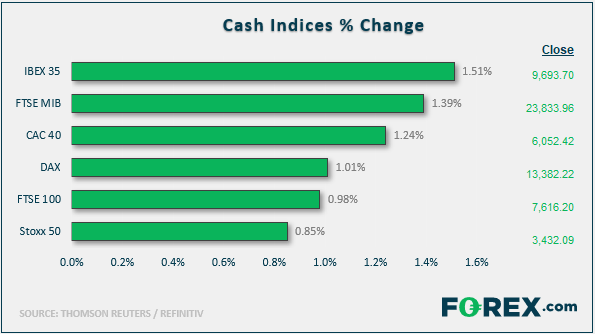
- Thursday’s stock markets are what it looks like when risk appetite hits the ground running for the first session of the decade. European shares, U.S. stock index futures and Asia-Pacific indices have been on an unbroken tear
- The White House’s signal that a phase one trade deal with Beijing is on track—Donald Trump sees the accord signed on 15th January—is one stimulus. China’s planned 50 basis point required reserve ratio cut for large banks that will take effect on Monday, is the other biggie
- As much as investors are keen to ring-in the New Year with sure-footed gains, these influences are of course ‘so 2019’. Not least because predicating a positive risk-asset rally on them continues to ignore a whole host of well-rehearsed reasons to remain cautious. China’s policy easing isn’t even much of a surprise. Official impetus for Beijing to soften monetary conditions is typical at this time of the year ahead of Chinese New Year and Spring Festival holidays. (In 2020 they fall on 24th to 30th January.) Furthermore, the cut was flagged by Premier Li Keqiang late last month. In the context of the PBOC’s well-telegraphed aim to keep downward pressure on rates, there are also good reasons to see future policy reductions as already priced in to an extent
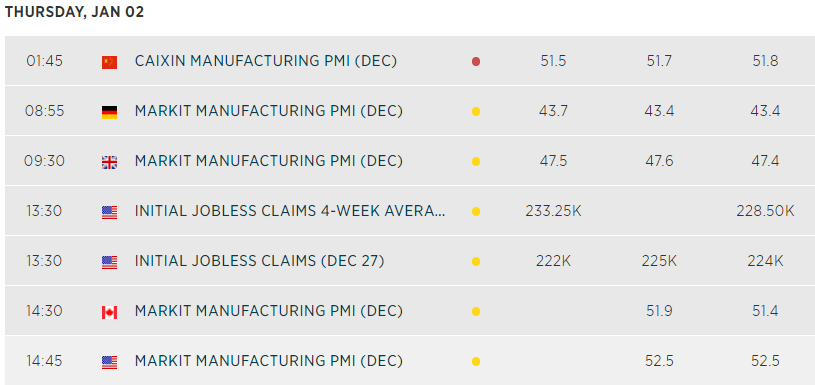
- As for trade, at best ‘phase one’ caps the bottle, but the genie’s long gone. Major uncertainties remain as to when comprehensive agreements on the most tortuous aspects of U.S.-China commercial relations will be possible, if ever. An end of escalation counts for much, sure. Unfortunately though, risk appetite looks set to remain vulnerable to further discouraging developments on the trade front and beyond. Europe has already been delivered of a timely reminder that Eurozone economy remains in less-than-solid shape, judging by a sobering set of PMI readings out earlier. For today though, optimistic sentiment is probably most of what you need to know
Stocks/sectors on the move
- Spot the China themes but also note the implied reversion plays: Materials led Europe’s sectors ahead of Wall Street open, rising 2% predictably aided most by metal and mining firms. Poland’s KGHM, up 2%, stood out, partly tracking strong futures on that industrial metal and also nickel
- Financials are also spot lit, mostly on the back of insurers but also of course on banks. A Polish theme emerged there as well as lenders in that country were another sector sharply ahead, enabling Warsaw’s market to rise higher than most of the region’s indices. The WIG 20 was up 1.8% gain, matching the ISEQ All-Share’s move in Dublin, but below OMX Stockholm’s 2% advance. Polish shares were among 2019’s worst performers at the index level
FX snapshot as of [2/1/2020 2:17 pm]
View our guide on how to interpret the FX Dashboard
FX markets
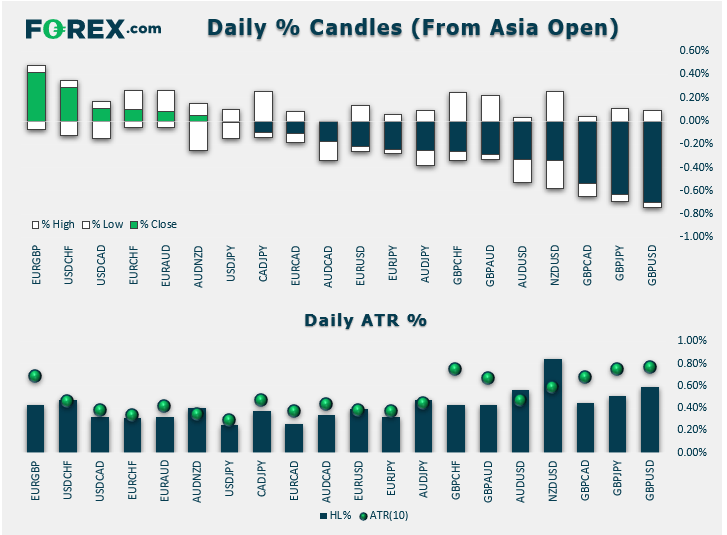
- The pound had a good holiday whilst most participants were away, so perhaps, we shouldn’t read too much into a standout retracement by sterling. GBP/USD was second-biggest faller among majors just now. Sterling implied volatility is lower than December’s fever pitch, but high enough above the G10 average to signal that things are still not particularly normal
- Meanwhile, the dollar joins the reversion theme, breaking a four-day slump with a 0.2% bounce for the Dollar Index. That adds pressure across the board
- The euro managed to muffle the downside though: data out earlier were weak, but they were better than expected
- USD/CHF saw 0.9647 highs; recovering from a 16-month low in the middle of last month
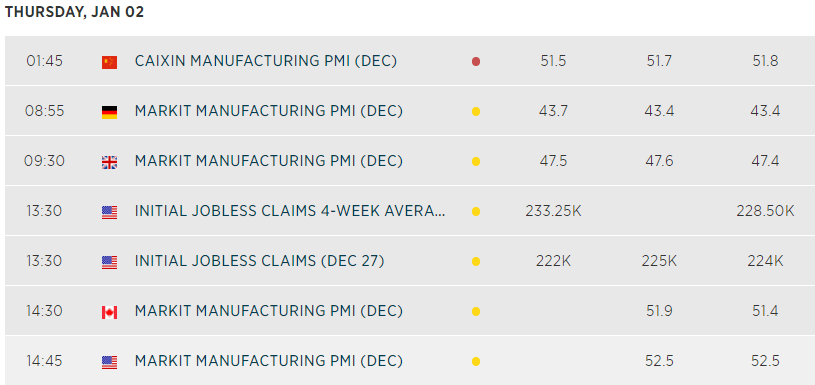
- Aussie and Kiwi bear the brunt. News out of China wasn’t all gravy. Caixin’s manufacturing PMI fell to 51.5 vs. 51.8 in November
Economic highlights
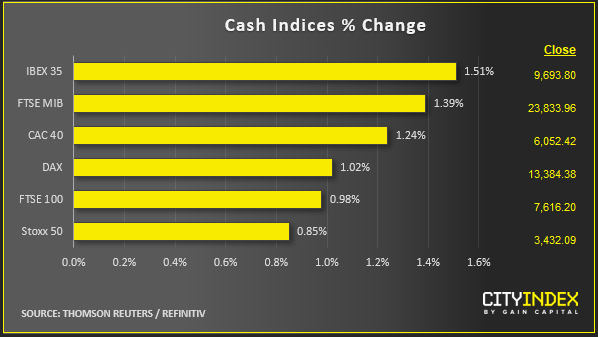
Stock market snapshot as of [2/1/2020 2:17 pm]
- Thursday’s stock markets are what it looks like when risk appetite hits the ground running for the first session of the decade. European shares, U.S. stock index futures and Asia-Pacific indices have been on an unbroken tear
- The White House’s signal that a phase one trade deal with Beijing is on track—Donald Trump sees the accord signed on 15th January—is one stimulus. China’s planned 50 basis point required reserve ratio cut for large banks that will take effect on Monday, is the other biggie
- As much as investors are keen to ring-in the New Year with sure-footed gains, these influences are of course ‘so 2019’. Not least because predicating a positive risk-asset rally on them continues to ignore a whole host of well-rehearsed reasons to remain cautious. China’s policy easing isn’t even much of a surprise. Official impetus for Beijing to soften monetary conditions is typical at this time of the year ahead of Chinese New Year and Spring Festival holidays. (In 2020 they fall on 24th to 30th January.) Furthermore, the cut was flagged by Premier Li Keqiang late last month. In the context of the PBOC’s well-telegraphed aim to keep downward pressure on rates, there are also good reasons to see future policy reductions as already priced in to an extent
- As for trade, at best ‘phase one’ caps the bottle, but the genie’s long gone. Major uncertainties remain as to when comprehensive agreements on the most tortuous aspects of U.S.-China commercial relations will be possible, if ever. An end of escalation counts for much, sure. Unfortunately though, risk appetite looks set to remain vulnerable to further discouraging developments on the trade front and beyond. Europe has already been delivered of a timely reminder that Eurozone economy remains in less-than-solid shape, judging by a sobering set of PMI readings out earlier. For today though, optimistic sentiment is probably most of what you need to know
Stocks/sectors on the move
- Spot the China themes but also note the implied reversion plays: Materials led Europe’s sectors ahead of Wall Street open, rising 2% predictably aided most by metal and mining firms. Poland’s KGHM, up 2%, stood out, partly tracking strong futures on that industrial metal and also nickel
- Financials are also spot lit, mostly on the back of insurers but also of course on banks. A Polish theme emerged there as well as lenders in that country were another sector sharply ahead, enabling Warsaw’s market to rise higher than most of the region’s indices. The WIG 20 was up 1.8% gain, matching the ISEQ All-Share’s move in Dublin, but below OMX Stockholm’s 2% advance. Polish shares were among 2019’s worst performers at the index level
FX snapshot as of [2/1/2020 2:17 pm]
View our guide on how to interpret the FX Dashboard
FX markets
- The pound had a good holiday whilst most participants were away, so perhaps, we shouldn’t read too much into a standout retracement by sterling. GBP/USD was second-biggest faller among majors just now. Sterling implied volatility is lower than December’s fever pitch, but high enough above the G10 average to signal that things are still not particularly normal
- Meanwhile, the dollar joins the reversion theme, breaking a four-day slump with a 0.2% bounce for the Dollar Index. That adds pressure across the board
- The euro managed to muffle the downside though: data out earlier were weak, but they were better than expected
- USD/CHF saw 0.9647 highs; recovering from a 16-month low in the middle of last month
- Aussie and Kiwi bear the brunt. News out of China wasn’t all gravy. Caixin’s manufacturing PMI fell to 51.5 vs. 51.8 in November
Economic highlights
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Update: Euro Weakness Returns Ahead of Central Bank Decisions
A new trading week is underway and the euro continues to show signs of weakness in the short term. This can be seen in the recent performance of EUR/USD, which has fallen nearly 0.5% over the last three trading sessions, reflecting a relatively consistent loss of momentum in the European currency.

EUR/USD Analysis: Is Euro Indecision Becoming More Evident?
Recent trading sessions have not been particularly eventful for EUR/USD price action in the short term. In fact, recent moves have been limited to roughly 0.2%, highlighting a clear lack of direction within the market.
Iron ore bulls face a perfect storm as price tests major support
Deteriorating steelmaker profitability, seasonal weakness and bearish technicals are weighing on iron ore. But with the price testing critical support, there's genuine two-way directional risk despite the substantial headwinds facing bulls.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.