





Market Brief Worries Over Impeachment and Trade Tensions Outweigh China PMI
A summary of news and snapshot of moves from today’s Asia session.
Share this:

- Caixin released their PMI which shows the sector expanded at its fastest rate since February 2018, with production and new orders also rising faster than in August. Whilst NBS manufacturing PMI released earlier contracted for a fifth consecutive month, it was not as bad as feared. In fact, at 49.8 it was the slowest contraction since moving below 50 and above 49.5 as forecast. Whilst this could be seen as a net positive for global growth concerns, FX markets remained quite unresponsive to the data.
- NZD is today’s weakest major after business sentiment fell to a near 11.5 year low. Activity declined for a second consecutive month and costs, pricing intensions and inflation expectations are all weaker, according to respondents. And for the first time in 10 years, no sector reported plans to increase staff. NZD/USD found support just above 4-year lows, NZD/CAD hit a 4-year low and AUD/NZD touched a 5-day high.
- Japan’s retail sales jumped 2%, above 0.9% expected as shoppers rushed to beat the sales tax hike to be implemented tomorrow. Currently at 8% it will be raised to 10%.
- A global trade barometer by DHL expects a further deceleration in trade.
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
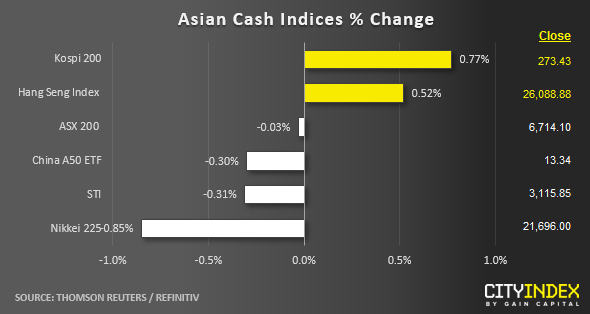
- Mix performances seen on the key Asian stock markets as at today’s Asian mid-session. Market participants now weight the possibility of the U.S. administration to impose restrictions on U.S. capital inflows into China that can escalate the on-going trade tension between U.S. and China. Over the weekend, a U.S Treasury official has been quoted by media that the U.S. still has not plans “at this time” to stop China firms from listing on U.S. stock exchanges.
- The worst performer so far is the Japan’s Nikkei 225 where it has shed by -0.85% to print a 3-week low of 21690 on the back drop of a weakening manufacturing sector. Preliminary Industrial Production for Aug has declined by -4.7% y/y that has came in far below expectation of -1.8% y/y.
- China’s official and Caixin Manufacturing PMIs for Sep has improved slightly; (49.8 versus 49.5 in Aug – official) and (51.4 versus 50.4 in Aug - Caixin). No much impact on the markets and the China A50 has inched lower by -0.30% ahead of the week-long China’s National Day Golden Week holiday where the local China stock market will be shut from 01 Oct to 07 Oct 2019.
- The Hong Kong stock market has managed to shrug off last weekend’s violent crashes seen between protestors and the police force and staged an up move of 0.50%. The main catalyst can be attributed to the positive performance of the mega IPO listing of AB INBev’s Asia Pacific unit (the 2nd largest in the world so far in 2019 after Uber) where it has rallied by close to 6% versus its IPO price of HK$27.
Matt Simpson and Kelvin Wong both contributed to this article


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.