



Markets Rally on Ceasefire Optimism & Fed Cut Hopes | DAX Eyes Record High
APAC equities climbed following Wall Street’s tech-led rebound, as ceasefire progress in Gaza and easing hopes from the FOMC Minutes boosted sentiment. The DAX resumed its uptrend, holding above 24,510 support and eyeing a new record near 24,650. Gold remained firm near $4,000/oz, oil eased on peace headlines, and copper gained as China reopened. With the US shutdown ongoing and global policy uncertainty lingering, risk appetite is cautiously improving.
Share this:
Market Overview
APAC equities were mostly higher, tracking the tech-led rebound on Wall Street where both the S&P 500 and Nasdaq 100 posted fresh record highs. Sentiment improved further after reports that Israel and Hamas agreed to a first-phase Gaza ceasefire, while Chinese traders’ return from the Golden Week holiday added volume.
US indices:
- S&P 500: +0.58% at 6,754
- Nasdaq 100: +1.19% at 25,137
- Dow Jones: Flat at 46,602
- Russell 2000: +1.04% at 2,484
US macro: The FOMC Minutes reinforced a cautious stance, with most participants expecting further easing this year but acknowledging lingering upside inflation risks. Market reaction was muted.
DAX Technical Analysis
The Germany 40 (4H) has retested and held the 24,510 breakout zone, resuming its advance toward the all-time high at 24,648. The index is now trading in a tight bullish range near the upper Bollinger Band, indicating continued strength but also near-term overextension risk. The RSI (66.7) remains in bullish territory but not yet overbought, while the MACD has turned positive again with a subtle uptick in the histogram — signaling renewed upsde momentum after a brief consolidation phase.
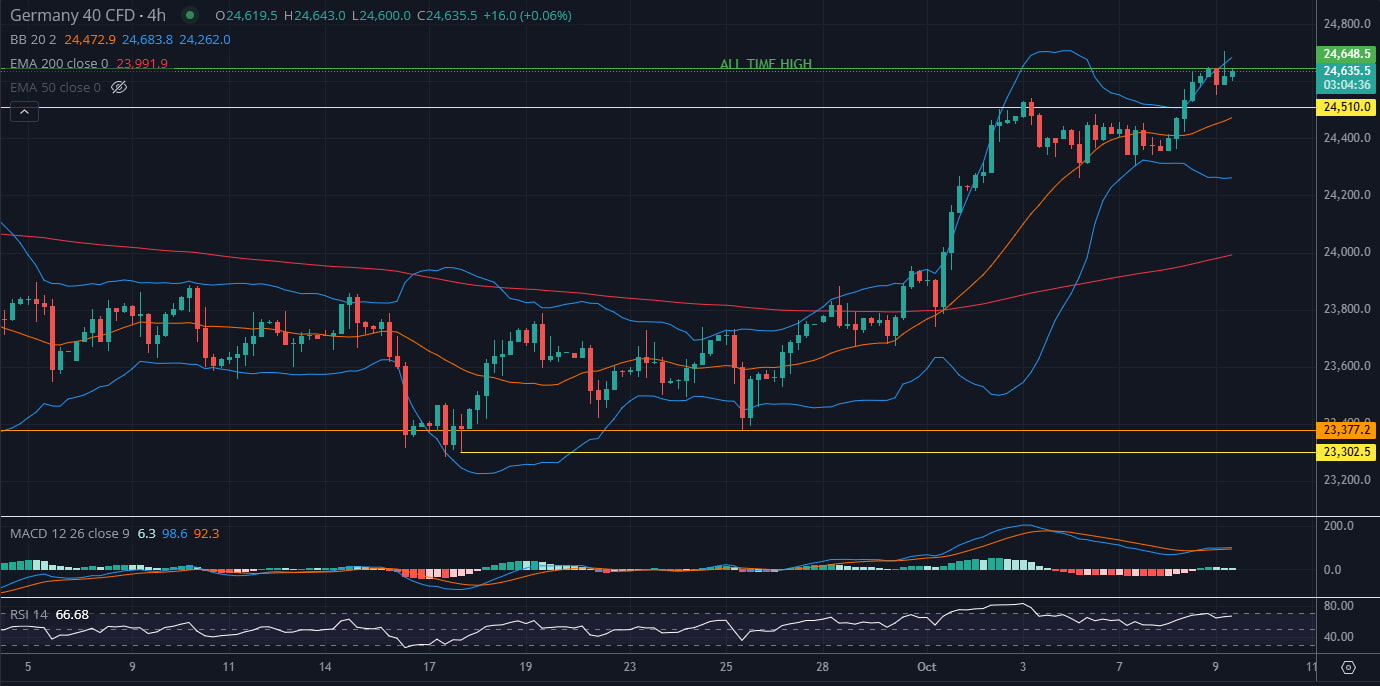
Structurally, the DAX maintains a clean breakout-and-retest pattern: after clearing 24,510, buyers successfully defended that level, establishing it as new support. The next resistance is the all-time high at 24,648, with potential extension toward 24,800 if momentum follows through. On the downside, initial support rests at 24,450 and 24,300 (the 20 EMA), while the 200 EMA around 23,900 remains a key trend-defining floor. Overall tone: bullish continuation, with momentum building for a potential new record high if the 24,650 level is decisively cleared.
Key Developments
Monetary Policy
- FOMC Minutes: Majority supported a 25bps rate cut in September; one member (Miran) preferred 50bps. Most saw growing downside risk to employment and diminishing upside risk to inflation. Several judged policy as not overly restrictive, warranting a gradual and data-dependent approach.
- Fed participants remain cautious about further moves amid uncertainty on inflation dynamics.
Trade & Tariffs
- The Trump administration may exclude generics from its proposed pharma tariffs (WSJ).
- China introduced export controls on rare earths effective December 1, requiring export licenses for dual-use materials and banning shipments tied to WMD or military uses.
- Vietnam to continue trade negotiations with the US through October and November.
- Canadian PM Carney met President Trump, noting a “meeting of minds” on steel and auto industries and suggesting bilateral deals alongside the USMCA.
US Political Developments
- The government shutdown continued as both Democrat and Republican bills failed in the Senate.
- President Trump said most federal workers will receive back pay and that military personnel will likely continue to be paid.
- The IRS will furlough 34,000 employees.
- House Minority Leader Jeffries supports a standalone bill to pay troops.
Regional Market Summary
APAC
- Nikkei 225 extended its rally, led by tech strength mirroring US peers.
- ASX 200 marginally higher, supported by miners but held back by tech and financials.
- Hang Seng and Shanghai Comp diverged: Hong Kong lagged while Mainland China outperformed after reopening; Hang Seng Bank surged >26% as HSBC proposed to take it private.
- US futures steady; Euro Stoxx 50 futures -0.3% indicate a softer European open.
FX
- DXY paused its recent rise; FOMC Minutes added little new information.
- EUR/USD rebounded from 1.16 amid French political stabilisation.
- GBP/USD recovered from sub-1.34 despite limited BoE policy impact.
- USD/JPY steady above 150.00; Takaichi-related optimism fading as policy timing uncertain.
- NZD/USD retraced RBNZ-related losses amid improved risk sentiment.
- PBoC fixed USD/CNY at 7.1102 (stronger than expected).
Fixed Income
- USTs flat after weak 10-year auction and hawkish Fed tone.
- Bunds steady near 129.00 ahead of German Trade Data and ECB Minutes.
- JGBs slightly firmer post 5-year auction results in line with prior.
Commodities
- Oil eased on Gaza ceasefire optimism and hostage-release reports.
- Gold dipped from record highs but remained supported near USD 4,000/oz.
- Copper gained modestly as China trading resumed.
- UK grid operators confident in winter energy supply; peak gas demand seen at 182 MCM vs. 565 MCM supply.
Crypto
- Bitcoin declined below USD 122k after recent highs.
Geopolitics
Middle East
- US President Trump confirmed Israel and Hamas have signed the first phase of a peace plan, including hostage releases and troop withdrawals.
- Israeli cabinet to ratify the deal Thursday; first releases expected this weekend.
- Hamas and Qatar confirmed the agreement covers a ceasefire, prisoner swaps, and aid entry.
- Trump suggested potential visits to Israel and Egypt after a routine health check.
- US Secretary of State Rubio will not attend France’s post-war Gaza conference.
Asia-Pacific Security
- Taiwan Defence Ministry warned that China is escalating hybrid warfare, using AI-driven cyberattacks and botnets to undermine public trust and digital infrastructure.
- UN plans a 25% reduction in peacekeeping due to funding shortfalls.
Europe & UK
- France: Caretaker PM Lecornu declared his mission complete; President Macron expected to appoint a new PM within 48 hours. Budget path likely by year-end.
- UK: RICS Housing Survey (Sep) came in at -15.0, better than expectations (-18.0).
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

GBP/USD, DAX Forecast Two trades to watch 220926
GBP/USD struggles as UK government borrowing exceeds forecasts, putting pressure on Healey ahead of the Budget. DAX eases back after yesterday's gains as oil prices and political headwinds rise.

USD/CAD Analysis: Is the Canadian Dollar Running Out of Support?
A new trading week is underway, and the Canadian dollar continues to show signs of weakening momentum. This can be seen in recent USD/CAD price action, with the pair gaining nearly 0.7% over the last four trading sessions.

DAX Climbs After Fed Move, Eyes Break Above 26,000 Resistance
The DAX has opened significantly higher following the Federal Reserve's delivery of its first interest rate hike since 2023. Although the Fed signaled further tightening, the market reaction was surprisingly positive, as much of the hawkish expectation had already been priced in. Attention now shifts to the 25,900–26,000 point range, which will likely determine whether the current recovery evolves into a new upward wave or remains merely a short-covering rally.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.