



Markets in holding pattern as traders eye US CPI
…once again the focus is going to be on inflation and central bank speech.
Share this:

The first half of today’s session saw the European indices push higher and this weighed on the dollar as the likes of GBP/USD and AUD/USD staged a modest bounced on improved risk sentiment, following last week’s falls. However, there was no fundamental justification for the improved risk appetite, as we haven’t had any major macro data or news. Attention is going to be on US CPI, due to be released on Tuesday, as market participants assess the likelihood of more rate hikes from the Fed beyond the 25 basis point rate hike expected in March.
What has been driving the markets?
Investor sentiment has been boosted in recent months by hopes that inflation has peaked. As a result, we have seen a big upsurge in risk sensitive asset prices in recent months, causing the dollar to slide. However, there was a bit of a pullback in stock prices and the dollar bounced back following the conclusion of key central bank meetings a couple of weeks ago.
Last week, if you remember, all the attention was on a speech by the Fed chair Jerome Powell. Traders were looking for comments from Powell on the much stronger than expected jobs report and whether this meant anything in terms of monetary policy adjustment. As it turned out, Powell caused a bit of volatility, but stuck to the FOMC’s view that the disinflationary process has begun. However, he pointed out that the inflation recovery will be a bumpy road, and that the 517,000 jobs added to the economy in January is evidence of that.
So, he appeased both the bulls and the bears, but ultimately didn’t cause any major shifts in sentiment.
Initially, the market interpreted his comments as being less hawkish than expected, causing stocks to rise and the dollar to fall. Those moves then quickly reversed, as investors realized that he actually wasn’t too dovish. We saw technology stocks head lower again, causing the S&P to close lower on the week. The dollar index finished higher for the second consecutive week.
So, as we transition into the new week, once again the focus is going to be on inflation and central bank speech.
US CPI is the highlight of week’s macro data
Luckily, we have plenty of inflation data to provide us direction. CPI data will come out from both the UK and US, which is likely to be the key macro event of the week.
In addition, we have Australia’s employment report, which should move the Aussie dollar sharply, especially if we see a beat after the RBA provided markets with a hawkish hike last week
But the key macro data is going to be Tuesday’s publication of US CPI. Expectations are for the headline print to fall to 6.2% YoY vs. a previous reading of 6.5% YoY. Core CPI is expected to fall to 5.5% YoY vs a previous reading of 5.7% YoY.
My colleague Matt Weller has a more in depth preview for US CPI, HERE.
My colleague Matt Weller has a more in depth preview for US CPI, HERE.
So, CPI is expected to continue falling, in line with the recent trend. However, if we see an above-forecast reading, or worse, a reading above last month’s print, then this may lead to a renewed strength in US dollar while stocks may head lower on anticipation of even tighter policy for longer. Inflation needs to be weaker than expected to put any real pressure on the dollar again.
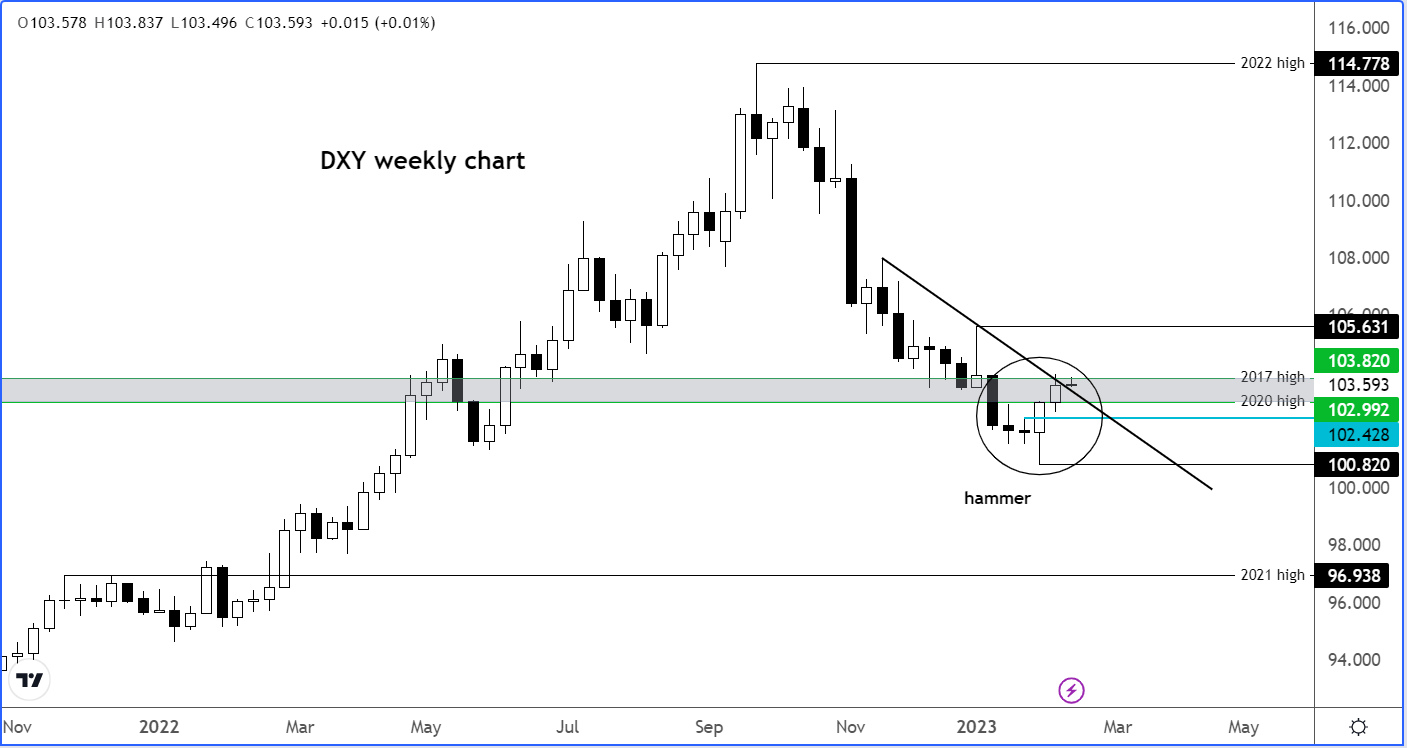
Dollar Index shows bullish price action
The dollar index has started to print bullish price action of late again. It completed another bullish candle last week, adding to the hammer candle that it had formed the week before. A clean break above 103.80 is now needed to trigger fresh technical buying.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.