


Nasdaq 100 Forecast: “Magnificent Seven” Q3 2025 Earnings Preview
Key themes for the Magnificent 7 Earnings season include the AI CapEx boom, digital ad spending, the divergence between enterprise and consumer spending and the regulatory backdrop.
Share this:
Nasdaq 100 Key Points
- Within the Magnificent Seven, laggards like Apple and Amazon have fallen so far this year despite generally bullish conditions and standouts like Nvidia and Alphabet have gained more than 30% year-to-date
- Key themes include the AI CapEx boom, digital ad spending, the divergence between enterprise and consumer spending and the regulatory backdrop.
- The bias for the Nasdaq 100 remains tilted toward the topside as long as this season’s earnings results at least meet analyst expectations.
Magnificent Seven Earnings Preview – MSFT, AAPL, GOOG, AMZN, NVDA, META, TSLA
Throughout most of the last few years, the “Magnificent Seven” big technology stocks (Microsoft, Apple, Nvidia, Alphabet/Google, Meta/Facebook, and Tesla) broadly moved as a monolithic unit, rising and falling in unison with the (mostly) ups and (fewer) downs of the broader market, albeit to differing extents.
Since flipping the calendar to 2025, the individual differences between these massive entities have become more stark, with laggards like Apple and Amazon falling despite generally bullish conditions and standouts like Nvidia and Alphabet gaining more than 30% year-to-date:
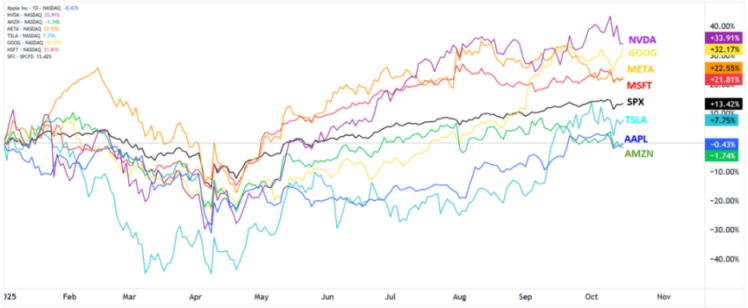
Source: StoneX, TradingView
Each of the Magnificent Seven stocks faces its own set of opportunities and challenges, but with Q3 earnings season just around the corner, it’s worthwhile to identify some common themes that are relevant to all the Magnificent Seven (and many other of the largest technology stocks as well).
Magnificent 7 Earnings “Cheat Sheet”
|
COMPANY |
Report date / time |
CONSENSUS EPS ESTIMATE* |
|
Tesla (TSLA) |
22 October |
$0.41 |
|
Alphabet (GOOGL) |
29 October |
$2.29 |
|
Microsoft (MSFT) |
29 October |
$3.65 |
|
Meta (META) |
29 October |
$6.58 |
|
Apple (AAPL) |
Thu 31 Jul |
$1.74 |
|
Amazon (AMZN) |
30 October* |
$1.58 |
|
NVIDIA (NVDA) |
19 November* |
$1.17 |
*estimated earnings date
Key Magnificent Seven Themes to Watch This Earnings Season
- AI CapEx: Spending Big, Demanding More
The hyperscaler capex arms race continues to define this earnings season, but the tone is shifting from scale to scrutiny. After investing an estimated $345 billion in AI and datacenter infrastructure in 2024, hyperscalers are projected to lift that figure to $414 billion in 2025, and upwards of $430 billion in 2026, according to BofA and McKinsey estimates. AWS, Microsoft Azure, Google Cloud, and Meta lead the charge, with all four pushing aggressive build-outs to support inference, training, and monetization of their AI models and platforms.
But some analysts are wondering whether the days of “capex at any cost” may be behind us. Morgan Stanley cautioned in a recent note that AI investments now carry heightened risk: rising power and real estate costs, rack overbuild risk, and a maturing monetization curve are forcing CFOs to justify infrastructure ROI more rigorously. In earnings calls, the Street will be listening closely for any cracks in the supply-demand balance - particularly from Nvidia, which remains sold out of its high-demand Blackwell chips - and whether hyperscaler executives are willing to blink on spend levels heading into 2026.
- Digital Advertising: Growth Still Intact, But Watch the Margins
Digital ad revenue continues to grow, but not without friction. According to GroupM and Dentsu, global ad spending is expected to grow ~5–8% in 2025, with digital commanding nearly 75% of the pie—roughly $678 billion in spend. That would mark another record, but also a slowdown in growth from the pandemic-era boom.
Crucially, the companies within the Magnificent Seven are dependent on digital ad spending to differing extents. Google and Meta are grappling with flattening search and feed ad pricing, while Shorts and Reels inventory continue to scale with relatively lower CPMs. Amazon, by contrast, is still gaining share via its high-margin retail media network and could again surprise to the upside. Forward guidance will be absolutely critical for GOOG, META, and AMZN in particular, where a pullback in Q4 holiday bookings could overshadow any solid Q3 results.
- The Two-Speed Economy: Enterprise Strength, Consumer Strain
This quarter may further entrench the bifurcation between consumer and enterprise demand. Apple and Tesla, two of the more consumer-sensitive names in the Mag 7, continue to show signs of strain as the chart above shows. iPhone volumes in China slipped nearly 9% YoY in Q1 2025, while Tesla’s auto gross margin declined from 16% in 2024 to 13.6% in Q2, with potential for more downside moving forward as Model 3 and Y price cuts bite.
Enterprise tech, meanwhile, remains healthy. Microsoft’s cloud business is expected to post 13–15% YoY growth, with Azure retaining its AI attach-rate tailwind. Amazon Web Services remains on track for 20%+ YoY gains, and Alphabet’s cloud unit is slowly expanding margins while gaining share in enterprise AI. This divergence explains much of the year-to-date performance and will remain a key theme through this reporting cycle as investors reward infrastructure-centric firms with strong cloud positioning, while discounting those exposed to discretionary consumer tech.
- Policy & Geopolitics: The Unrelenting Overhang
Regulatory and trade overhangs are again in the spotlight. The U.S. Department of Justice has moved into the remedies phase of its antitrust victory against Google, with analysts now debating whether the government will push for meaningful business separation or behavioral shifts. Apple, meanwhile, remains entangled in EU Digital Markets Act compliance and is appealing a €500 million fine tied to alleged anti-steering practices.
On the geopolitical front, Nvidia’s workaround GPUs including the much-discussed H20 are helping it maintain China sales despite tightening U.S. export controls. But the situation remains fluid with the US government increasingly getting involved both as a policymaker and outright investor in rival firms.

Nasdaq 100 Technical Analysis – NDX Daily Chart

Source: TradingView, StoneX
As the chart above shows, the Nasdaq 100 remains within a 5-month bullish channel for now, showing relative resilience against its major US index rivals.
Against that technical backdrop, the bias remains tilted toward the topside as long as this season’s earnings results at least meet analyst expectations. To the topside, the next level of resistance to watch is the round 25,000 handle, followed by the 161.8% Fibonacci extension of the “Liberation Day” swoon near 25,900 after that.
However, if weak earnings reports start to accumulate and the index breaks down from its channel to fall below the 50-day EMA, a deeper retracement toward the 200-day MA near previous resistance at 22,150 could be in the cards.
-- Written by Matt Weller, Global Head of Research
Follow Matt on Twitter: @MWellerFX
Related tags:
Latest market news

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Reaches 27,000 While Markets Watch Anthropic IPO
The DAX has pushed above the psychologically important 27,000 level as investors continue to reward strong earnings, improving industrial demand and renewed confidence in AI-related investment themes. Results from Siemens and Allianz, combined with growing anticipation surrounding the upcoming Anthropic IPO, are helping sustain risk appetite across European markets. The focus now shifts to whether earnings can continue supporting valuations as the index trades in record territory.
DAX Near Record Levels as Earnings Strength Supports Bulls
The DAX remains firmly positioned near record highs after reclaiming the 26,000 level and extending its recovery toward 26,700. Strong earnings momentum, improving industrial activity and renewed confidence in semiconductor and energy-transition stocks continue to support sentiment. With Siemens Energy and Infineon delivering upbeat signals for 2027, investors are increasingly focused on corporate fundamentals rather than macroeconomic uncertainty.
Nvidia Holds Support Ahead of Earnings as Nasdaq 100 Rebounds
Nvidia shares approach major support as selling pressure eases, while the Nasdaq 100 rebounds. Could upcoming earnings fuel a broader recovery?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.